


Earnings Beat Might Change The Case For Investing In Accenture Stock
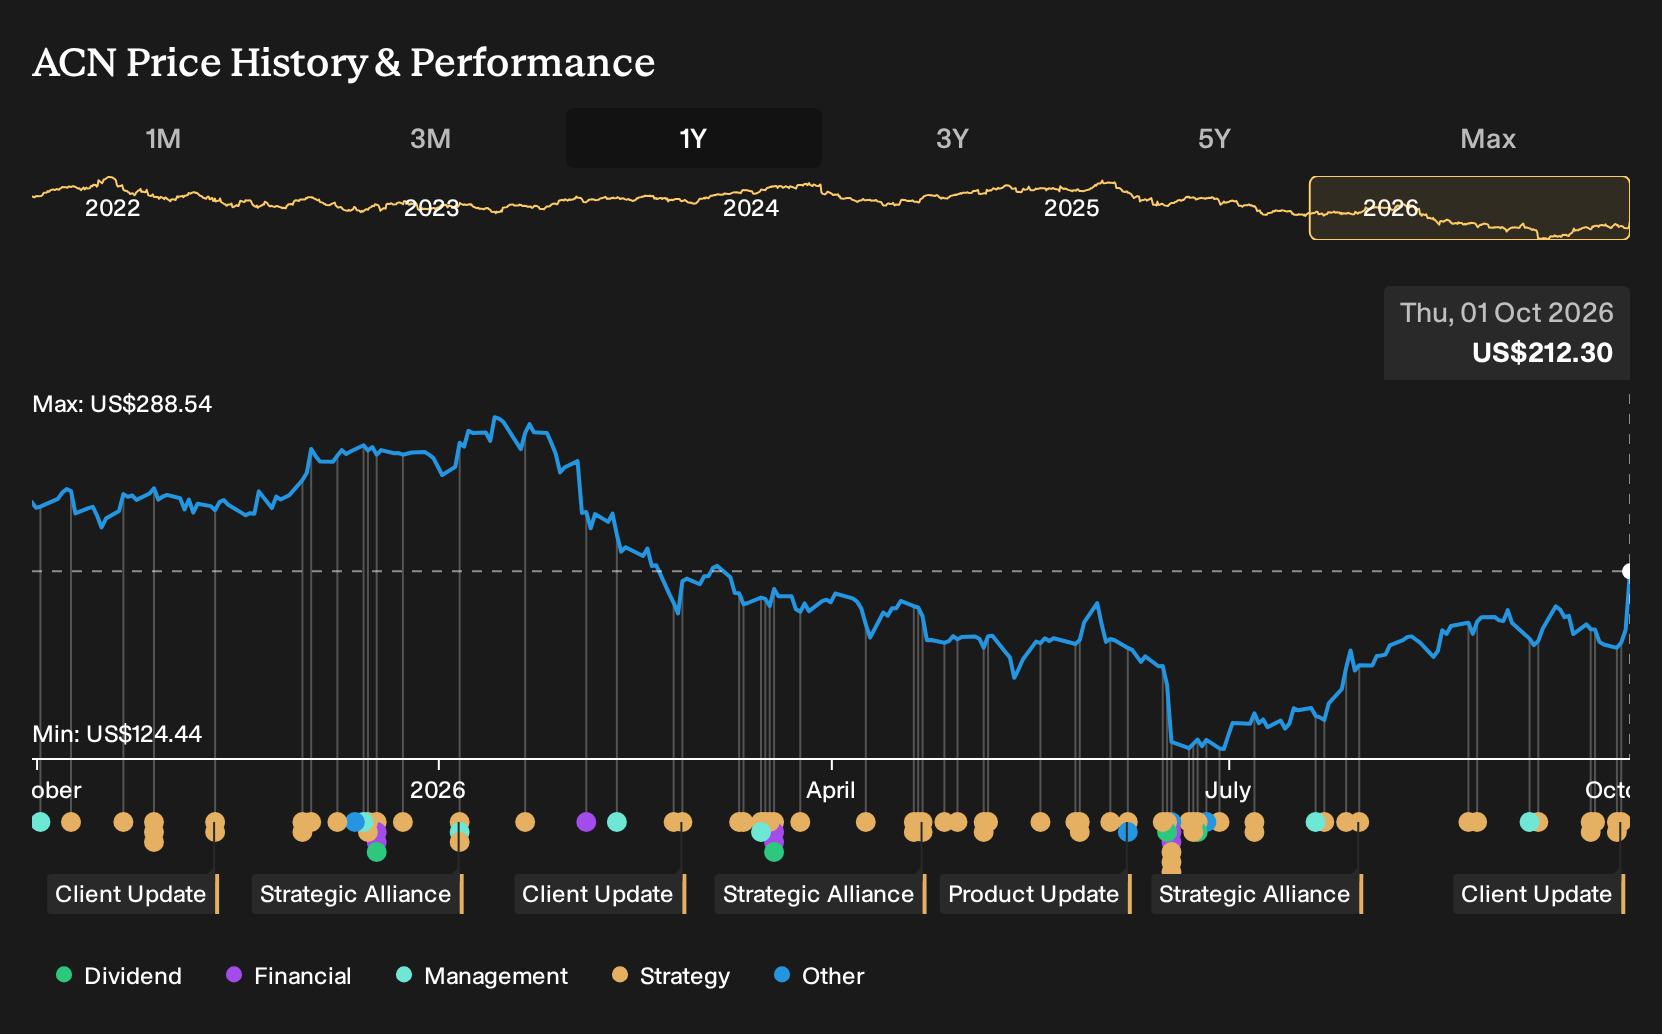
- Accenture reported fourth quarter 2026 sales of US$18,679.11m and net income of US$1,991.27m, with full year revenue of US$74,183.45m and net income of US$8,367.06m, alongside fiscal 2027 guidance for 3% to 6% local currency revenue growth and GAAP diluted EPS of US$14.39 to US$14.81.
- The firm paired these results with disciplined capital returns, completing a long running US$52.15b buyback program and signaling at least US$9.5b of cash planned for shareholders in fiscal 2027, while continuing to invest in AI focused services and acquisitions.
- This article examines how Accenture's investment narrative is affected by strong Q4 earnings alongside management's 2027 revenue and EPS guidance.
Scan how Accenture’s earnings, guidance and AI work compare with peers by lining up similar IT and software consultancies against the 90 AI infrastructure stocks.
Accenture Investment Narrative Recap
To own Accenture, you need to believe its push into AI heavy consulting, managed services and platform style work can keep offsetting slower or lumpier areas such as federal contracts and more cautious EMEA consulting demand. The fresh Q4 and full year numbers, plus 2027 guidance for 3% to 6% local currency revenue growth and higher GAAP EPS, keep that execution story intact rather than transforming it.
The main near term swing factor is whether the current AI and cloud project pipeline converts into sustained bookings while clients remain selective on discretionary projects. Federal and geopolitically exposed work still looks like the key drag risk. The latest results and guidance do not remove that exposure, but they suggest it is currently being managed rather than driving the overall narrative.
Among the recent announcements, the new Accenture Construct business around large capital and infrastructure projects is most relevant to the current earnings story. It ties directly into the managed services and long dated transformation work that helped deliver Q4 revenue ahead of guidance and supports the fiscal 2027 outlook.
Construct concentrates Accenture’s advisory, engineering and delivery capabilities for data centers, utilities, transport, advanced manufacturing and process industries into a single global unit. For you as an investor, the operational question is whether this scale up can deepen recurring style project work while the group continues to juggle risks from slower federal spending, elongated sales cycles in some regions and the heavy lift of executing AI centric programs well.
Accenture's narrative projects forecast revenue of US$84.2b and expected earnings of US$10.5b by 2029, based on analyst assumptions of 4.8% yearly revenue growth and an earnings increase of about US$2.7b from current earnings of US$7.8b.
Uncover why Accenture's fair value indicates a 12% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts frame Accenture’s AI and data center exposure as a major upside catalyst. Before this earnings release, the bullish camp was penciling in about US$87.6b of revenue and US$10.8b of earnings by 2029. That is far above the consensus path. Treat it as one of several narratives to test against the new numbers.
Explore 8 other Accenture fair value estimates, including one that suggests as much as 42% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Accenture research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Accenture. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Accenture's overall financial health at a glance.
Looking for more Accenture-like investment ideas?
If the Accenture story has sharpened your thinking, you can use that momentum to widen your watchlist with other companies that fit clear, fundamentals driven themes.
- For investors who want quality and value in the same place, filter for companies that pair strong balance sheets with attractive valuations using the 27 high quality undervalued stocks.
- If capital preservation sits near the top of your priorities, focus on resilience first by scanning the 31 resilient stocks with low risk scores to see businesses that screen well on Simply Wall St's risk checks.
- When you want to get beyond the usual large caps, broaden your opportunity set with the 19 high quality undiscovered gems and spot less followed stocks with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com