


DSM-Firmenich (ENXTAM:DSFIR) Could Be 3% Overvalued After Its €540 Million Buyback
DSM-Firmenich (ENXTAM:DSFIR) has completed its €540 million share repurchase program, which included buybacks for share-based compensation and capital reduction. Around 2.6% of issued shares are scheduled for cancellation by Q1 2027.
DSM-Firmenich shares trade at €96.1 after a sharp 39.6% year-to-date share price return and a 36.99% total shareholder return over the past year, while the recent buyback completion comes as shorter-term momentum has cooled, with a softer 7-day share price move and a modest 1-day decline.
Compare DSM-Firmenich's buyback driven share story with a curated group of companies that pair strong fundamentals with resilient balance sheets through our list of solid balance sheet and fundamentals (206 results)
DSM-Firmenich appears to be a solid operator in nutrition, health and beauty, and the recent buyback has supported a strong run. The key question is whether the quality of the business is already fully reflected in the current price.
Most Popular Narrative: 3% Overvalued
DSM-Firmenich last closed at €96.1 while the most followed narrative implies a fair value of €93.62. As a result, the current quote sits modestly above that central estimate and puts more weight on how the growth story and buybacks play out.
The successful integration of legacy DSM and Firmenich is delivering targeted cost and revenue synergies (€200 million plus €200 million vitamin transformation). These synergies are expected to continue to flow through in coming quarters, providing further support to both revenue and EBITDA margin improvement. Increasing sales contribution from local and regional customers, especially in emerging markets, diversifies revenue streams, reducing the company's exposure to volume volatility at large global clients and supporting more stable, long term top line growth.
See why 30 investors see DSM-Firmenich as 3% overvalued.
Result: Fair Value of €93.62 (OVERVALUED)
Still, DSM-Firmenich’s story could change quickly if foreign exchange swings continue to hit reported profit, or if weaker demand from large global customers persists.
Find out about the key risks to this DSM-Firmenich narrative.
Another View on DSM-Firmenich’s Value
Analysts using the SWS DCF model reach a very different conclusion on DSM-Firmenich. On their numbers, the shares at €96.1 trade below an estimated future cash flow value of €141.72. That frames the stock as undervalued on cash generation even though the consensus fair value narrative flags it as 3% overvalued.
This kind of gap puts the focus on your own assumptions about growth, margins and discount rate rather than any single price target. The real question is which framework you trust more when the story around DSM-Firmenich evolves: the multiples on current earnings, or the long-range cash flow view that underpins the SWS DCF output.
Look into how the SWS DCF model arrives at its fair value.
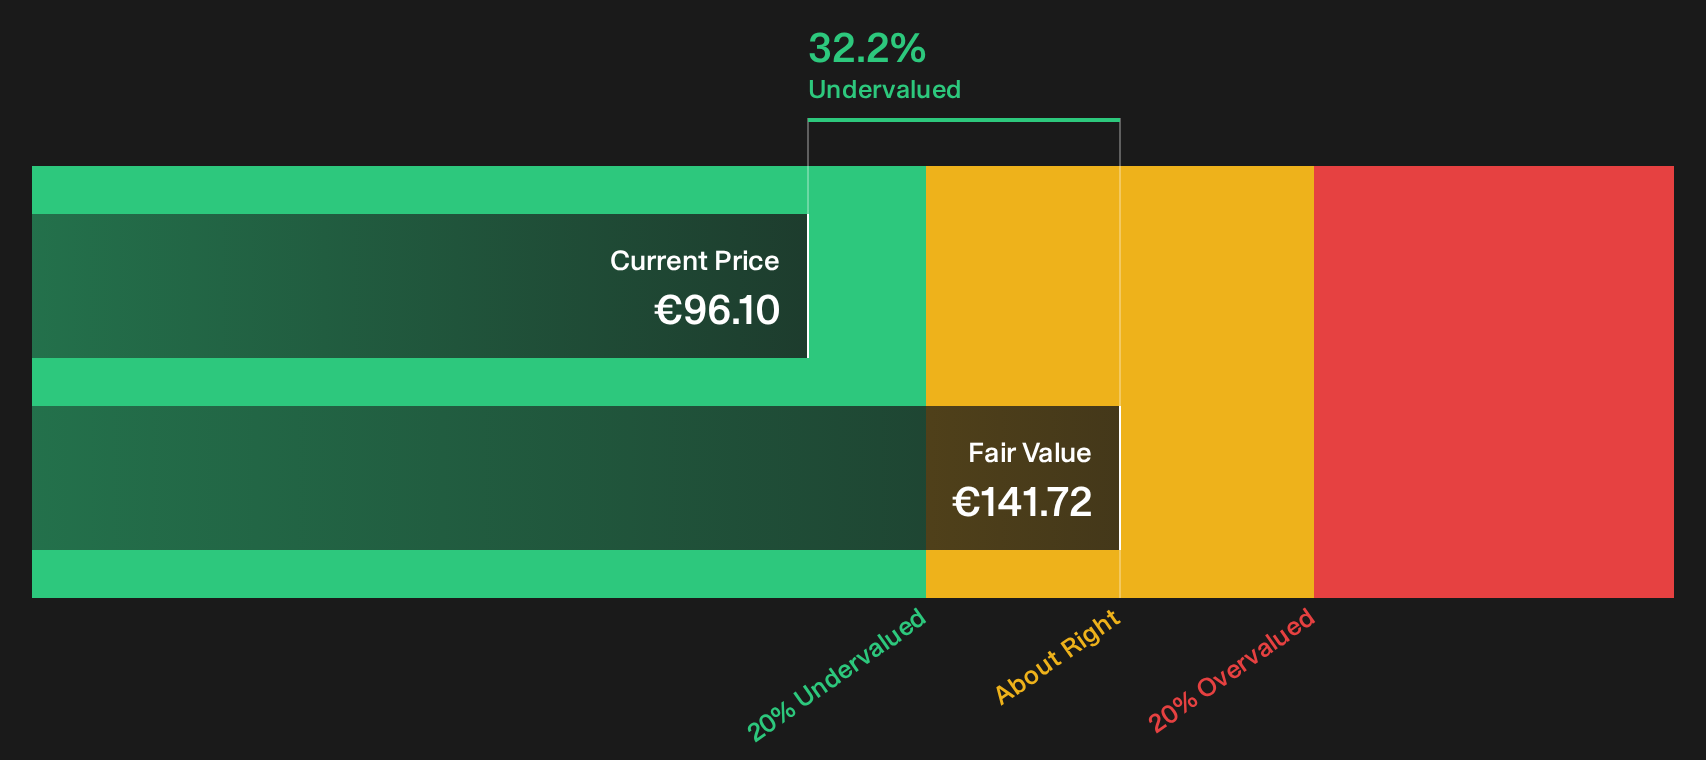
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DSM-Firmenich for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on DSM-Firmenich’s value story so far. If you want to move quickly and reach your own view, line up the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond DSM-Firmenich?
Do not stop at DSM-Firmenich. Use curated screeners to quickly spot fresh opportunities and avoid missing companies that might better match your goals and risk limits.
- Target strong fundamentals and valuation discipline by scanning a diversified pool of candidates through the 196 high quality undervalued stocks.
- Prioritise resilience and sleep-at-night comfort by filtering for companies with sturdier finances using the 222 resilient stocks with low risk scores.
- Review the 616 high quality undiscovered gems to identify companies that may align with your view of future potential.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com