


How New Air Defense Orders At Kongsberg Gruppen (OB:KOG) Have Changed Its Investment Story
- Kongsberg Gruppen has recently announced a series of large defense orders, including about NOK 1.5b for expanding the Netherlands’ CITADEL air defense programme and NOK 10b for NASAMS deliveries to Belgium, alongside a long term USMC frame agreement and a supply deal with Advanced Navigation.
- These contracts point to solid demand for Kongsberg Gruppen’s air and missile defense portfolio. They also increase execution, supply chain and program delivery demands across multiple long duration government projects.
- We will now look at how Kongsberg Gruppen's investment narrative is shaped by these sizeable NASAMS and CITADEL defence contracts.
Scan how Kongsberg Gruppen fits into the broader defence and security theme by comparing it with a curated list of 222 resilient stocks with low risk scores benefiting from resilient demand for critical systems.
Kongsberg Gruppen Investment Narrative Recap
For an investor to stay with Kongsberg Gruppen, the core belief is that long running defense and maritime programs can translate into steady contract flow and disciplined project execution. The fresh NASAMS and CITADEL orders reinforce that narrative on the ground. In the short term, the key swing factor is how efficiently the company converts this larger backlog into delivered systems without eroding margins.
The biggest risk right now sits in program complexity. Multiple large European contracts, the USMC frame agreement and the Polish PROTECTOR deliveries all compete for the same engineering capacity and suppliers. Any slippage in schedules, cost control or export approvals could turn today’s healthy order book into more volatile earnings and tighter cash conversion.
The NOK 10b NASAMS contract for Belgium looks particularly relevant to the current story. It deepens Kongsberg Gruppen’s position in European air defense and connects to the Netherlands procurement channel that already uses NASAMS. This scale of order can influence factory loading, supplier terms and resource planning for an extended period once deliveries start ramping.
That same agreement also magnifies execution risk. Integrating Belgium into an already busy NASAMS pipeline raises coordination demands across production, software, training and lifecycle support. For investors, this contract becomes a live test of whether Kongsberg Gruppen can handle higher throughput while maintaining quality, timing and profitability, which are central to the existing growth and margin expectations.
Kongsberg Gruppen's current analyst narrative points to NOK 92.0b revenue and NOK 14.8b earnings by 2029. That profile assumes revenue expands at 37.1% per year and that earnings rise by about NOK 9.5b from NOK 5.3b today to the 2029 consensus level.
Uncover why Kongsberg Gruppen's fair value indicates a 27% potential upside to its current price that could narrow quickly.
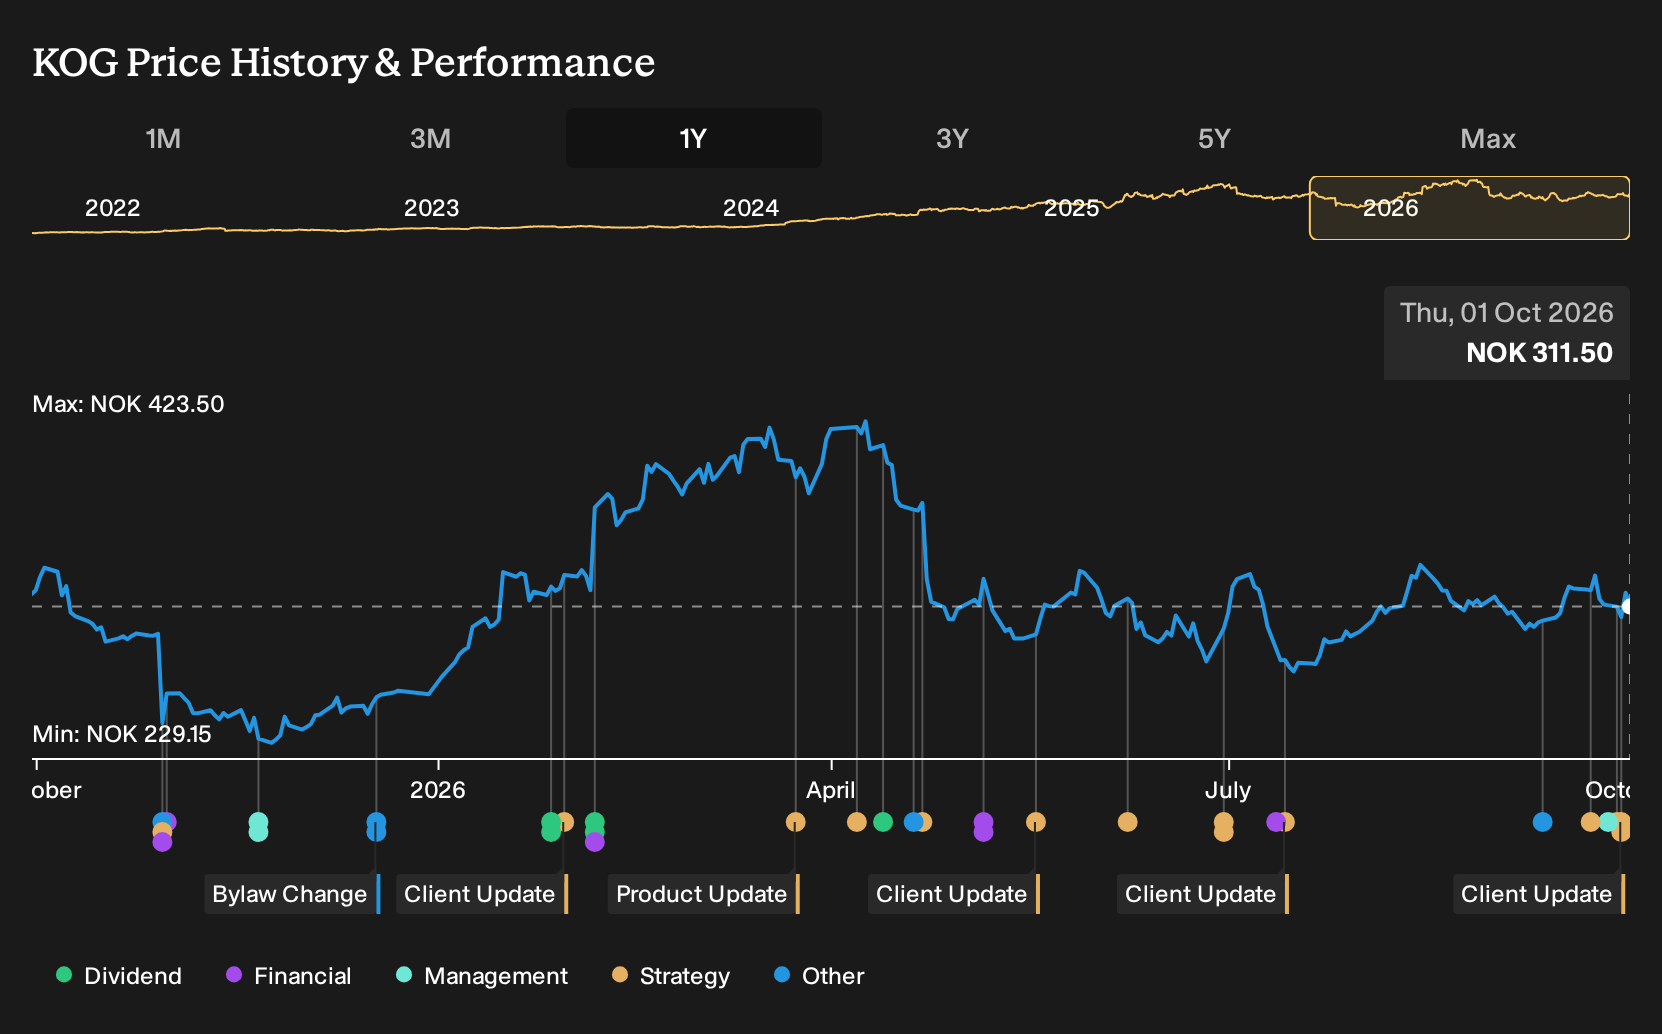
Exploring Other Perspectives
One upbeat twist on Kongsberg Gruppen focuses on upside from recurring NATO work. The most optimistic analysts were already pencilling in NOK 107.3b revenue and NOK 19.7b earnings by 2029, well above the NOK 92.0b and NOK 14.8b baseline. You can now ask whether these fresh CITADEL and NASAMS deals push that optimistic story even further or prompt a rethink.
Explore 4 other Kongsberg Gruppen fair value estimates, including one that suggests as much as 241% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kongsberg Gruppen research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Kongsberg Gruppen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kongsberg Gruppen's overall financial health at a glance.
Looking for more Kongsberg Gruppen style investment ideas?
If you want to broaden your watchlist beyond Kongsberg Gruppen, the Simply Wall St Screener can help you quickly filter for different types of opportunities that match your risk profile and income goals.
- If you prefer steadier businesses with stronger cushions against shocks, start with a curated list of solid balance sheet and fundamentals (206 results) that can help you focus on resilience over excitement.
- If value is your priority and you like to hunt for quality at a discount, scan through our 196 high quality undervalued stocks that narrows the field to companies where fundamentals and pricing look more aligned.
- If you are income focused and watching for reliable payouts, use the 157 dividend fortresses to quickly spot higher yielding stocks that may warrant a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com