


Microsoft (MSFT) Stock Looks Fully Valued Despite Fresh AI Liability Warnings
Microsoft has become one of the clearest ways to play the AI buildout, and with the stock around US$512.90 and a 5 year return of 82.3%, the live question is whether the underlying cash flows are enough to support that kind of price.
- An 82.3% gain over 5 years puts a lot of future cash generation into focus, because that move only makes sense if investors see far more value ahead than the recent 1 year decline of 0.5% might suggest.
- Heavy spending on AI data centers, Copilot discounts and long term cloud commitments can support future revenue and operating cash flow, but they also concentrate risk if projects tied to off balance sheet obligations and partner contracts do not earn back their cost as planned.
- If you'd rather focus on earnings, this one's for you. See why Microsoft's 28.5x P/E tells a different valuation story.
For investors, the debate is whether the current share price is broadly in line with what Microsoft’s existing and future cash flows are worth on a Discounted Cash Flow (DCF) basis.
If you want to test the same cash flow question you are asking of Microsoft against a broader set of AI exposed businesses, start with 90 AI infrastructure stocks.
Is Microsoft Fairly Priced on Cash Flow?
The Discounted Cash Flow (DCF) model here looks at what Microsoft can return to shareholders based on its projected cash generation over time. It starts with a hefty latest twelve month free cash flow of about $96.0b, then applies a 2 Stage Free Cash Flow to Equity approach that assumes growing free cash flow rather than a shrinking base.
Those projections build in sizeable future cash flows, including analyst and model estimates that extend into the early 2030s, which helps explain why the DCF output sits broadly in line with the current share price of US$512.90. Michael Burry’s warning about large off balance sheet AI infrastructure obligations helps frame the risk side of that picture, because the DCF treats Microsoft’s AI and cloud cash flows as valuable enough to balance the capital tied up in that buildout. Find out what Microsoft could be worth using our Discounted Cash Flow (DCF) estimate.
The Microsoft Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Microsoft sit between that DCF puzzle and your own thesis. They explain which paths for revenue growth, profitability and earnings would need to hold for the stock to be worth meaningfully more or less than it is today. Each one links its implied value to a concrete view on how Microsoft’s expansion, margins and risk profile could evolve, giving you something you can revisit as fresh information comes through.
Community views on Microsoft are split between AI driven upside and concerns that the price already reflects much of that optimism.
Bull case: 10% undervalued
"The accelerated adoption and integration of AI capabilities across Microsoft's infrastructure and application stack, including Azure AI, Copilot, Dynamics 365, GitHub, and Fabric, are driving new revenue streams and usage intensity…"
Discover why this Narrative puts Microsoft at 10% undervalued.
Bear case: 29% overvalued
"Microsoft just burned $37.5 billion in 90 days…"
Explore why this Narrative puts Microsoft at 29% overvalued.
One more Microsoft check that sits beside the cash flow maths
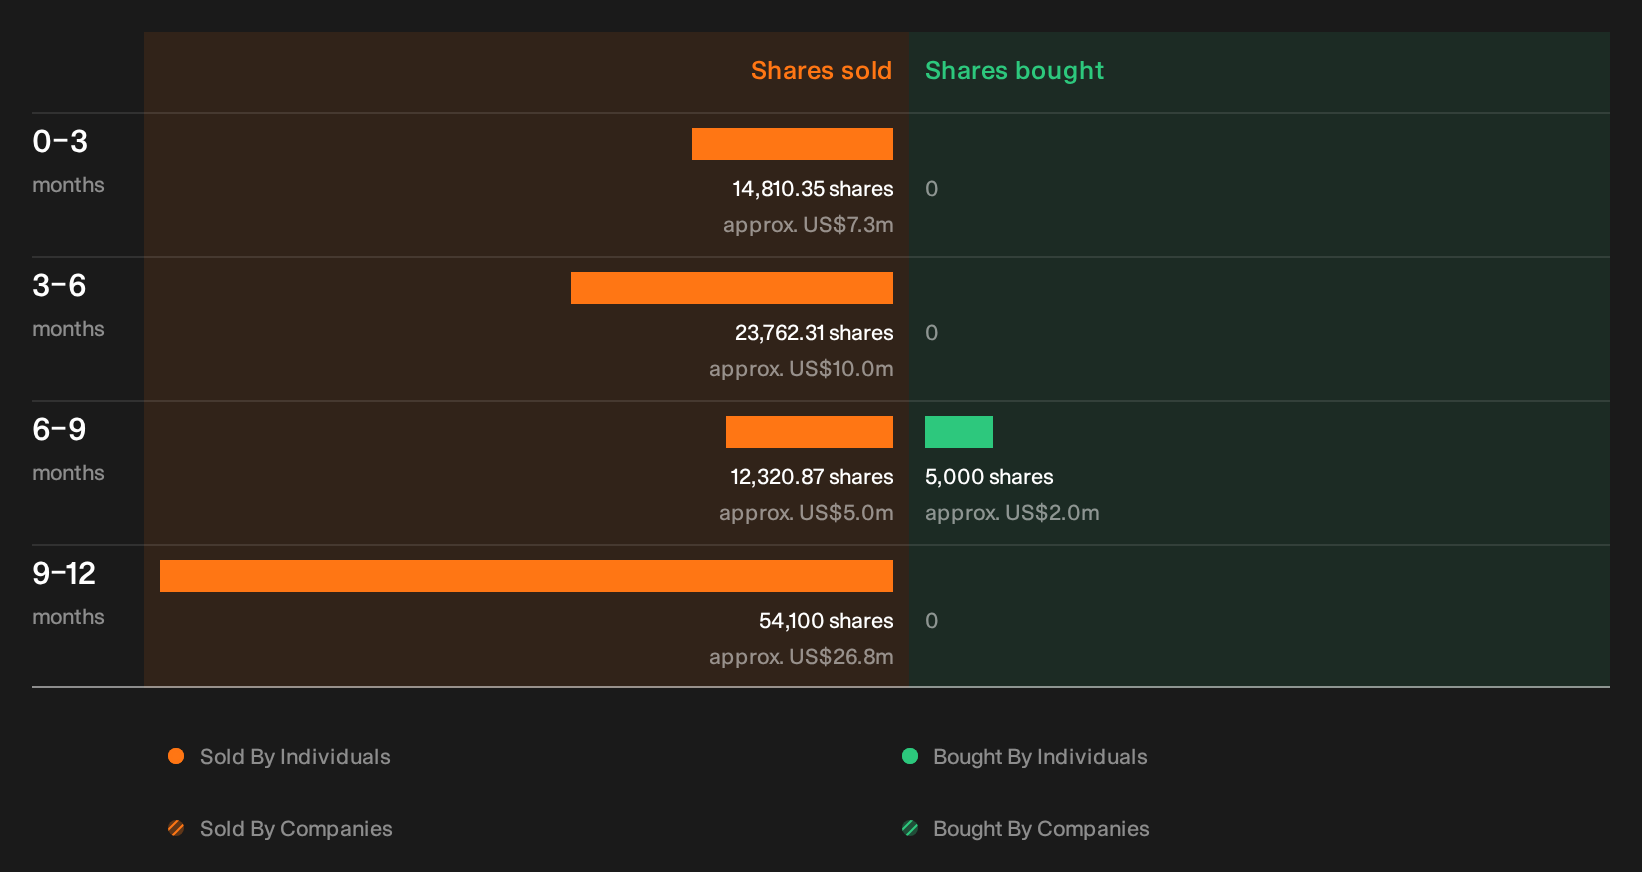
Price and cash generation tell only part of the Microsoft story. Recent insider transactions have also tripped our checks, and the individuals involved, the size of the trades and what they might signal are still for you to unpack. See the recent insider selling flagged for Microsoft.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com