


Is Meitu (SEHK:1357) Undervalued After Its MVLAND 2.0 Studio Mode Release?
Meitu (SEHK:1357) just pushed its AI ambitions further with MVLAND Version 2.0, adding a Studio Mode that links music analysis, shot planning and editing into one production workflow for music videos.
For context, Meitu’s 1-day share price return of 0.93% and 7-day gain of 1.46% come after a much steeper 30-day share price drop of 21.5% and year-to-date share price decline of 48.65%. Total shareholder return is down 57.32% over 1 year but remains strongly positive over 3 and 5 years, suggesting long term holders have still done well even as shorter term momentum has weakened around recent product news like MVLAND Version 2.0.
Scan beyond Meitu's AI push and explore other hand-picked AI-related plays with the 147 AI small caps that could be preparing for their next move.
Meitu now trades at a steep discount to both analyst targets and some fair value estimates after a sharp slide. Is the price gap signalling opportunity, or is the market simply pricing MVLAND risk more realistically?
Most Popular Narrative: 54% Undervalued
Meitu's most followed valuation story pegs fair value at HK$8.24 against a last close of HK$3.82, so the current slide is set against a narrative that sees the stock trading well below that estimate, backed by detailed assumptions for growth, margins and risk.
Successful integration of advanced AI features (AI Wardrobe, AI Flash, and RoboNeo) has significantly improved user engagement and willingness to pay, demonstrated by a 45.2% year-on-year revenue growth in the core Photo, Video, and Design (PVD) segment and a rising subscription rate, pointing to higher future ARPU and improved gross margins.
See why 6 investors see Meitu as 54% undervalued.
Result: Fair Value of HK$8.24 (UNDERVALUED)
Still, the bullish Meitu narrative depends on two pressure points not breaking: competition in AI imaging staying manageable, and third party AI model costs not eroding profitability.
Find out about the key risks to this Meitu narrative.
Another View: Meitu Through The P/E Lens
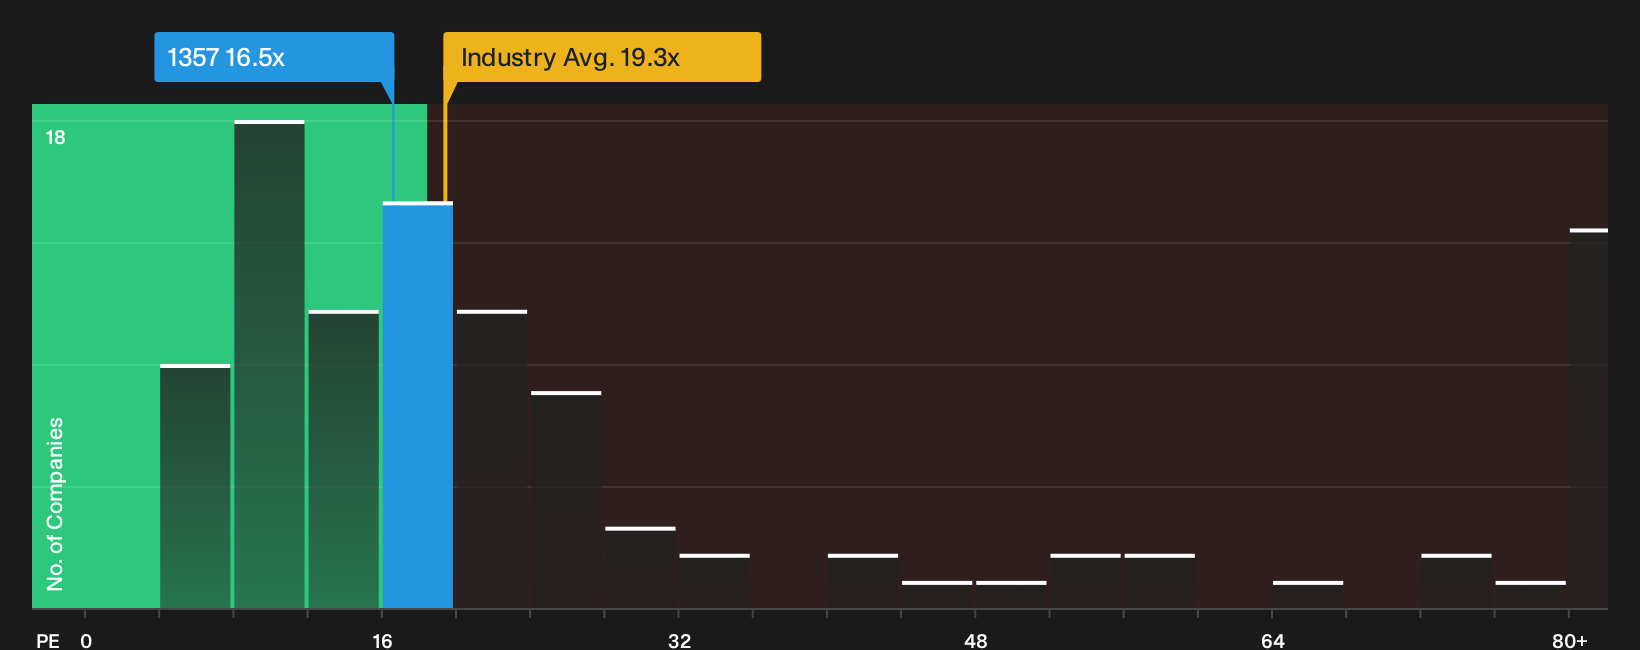
Analysts frame Meitu as undervalued on fair value estimates around HK$8.24, yet the P/E picture is more mixed. The stock trades on 16.5x earnings, richer than a fair ratio of 14.8x and a peer average of 12.9x, but cheaper than the wider Asian industry at 19.3x. Does that blend point to mispricing or simply reflect the risk profile investors already see?
To see how that gap between current P/E, peers and the fair ratio could close over time, and what the numbers imply for valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Here is how Meitu’s current P/E compares visually with the sector and with its own history:
Next Steps
Sentiment on Meitu is clearly split. This is exactly why you should move quickly, review the full picture and weigh both sides of the argument using the 2 key rewards and 1 important warning sign.
Looking for more Meitu-sized opportunities?
Do not stop with Meitu. Use the Simply Wall St Screener to quickly spot other ideas that match your risk tolerance, income needs and value focus.
- Target steady compounding by scanning a 222 resilient stocks with low risk scores that aims to keep volatility contained while still leaving room for upside.
- Hunt for mispriced quality through a 196 high quality undervalued stocks that filters for strong cash flows and robust fundamentals.
- Build your income stream using a 157 dividend fortresses that focuses on higher yielding payouts from businesses with more resilient balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com