


Why Envista Holdings (NVST) Is Back In The Spotlight
Envista Holdings stock reacts to sector leading Q2 performance
Envista Holdings (NVST) is back in focus after its Q2 update showed 7.1% year on year revenue growth, a sector leading outcome that topped analyst expectations and beat full year earnings guidance.
Recent trading shows that Envista Holdings shares have risen 8.21% year to date, even after a 30 day share price decline of 13.52% that has cooled shorter term momentum. Over a longer horizon, the 1 year total shareholder return of 15.28% contrasts with a 5 year total shareholder return that is down 42.01%. This leaves the latest Q2 beat looking more like a potential turning point than the end of a long rally.
Scan beyond Envista Holdings' strong Q2 and track peers with similar momentum by reviewing the hand picked 19 high quality undiscovered gems that may still be flying under most radars.
Envista Holdings now sits between two stories. Recent gains and a strong Q2 point to business progress, while the sharp 30 day pullback hints at sentiment whiplash. Which one does the current valuation reflect?
Most Popular Narrative: 21% Undervalued
Envista Holdings last closed at $23.47, while the most followed narrative pegs fair value at $29.69. This suggests a gap that hinges on execution around growth, margins, and capital allocation.
The growing link between oral health and general well-being, echoed by heightened consumer awareness, supports stable or rising demand for preventive and routine dental care equipment and services, providing resilience to Envista's consumables and recurring revenue, underpinning more predictable earnings and cash flow.
See why 3 investors see Envista Holdings as 21% undervalued.
This storyline uses an 8.2% discount rate and assumes future earnings and cash flows are worth $29.69 per share in today's terms, which is above both the recent price and the analyst consensus target cited in that research. The implied upside depends on revenue building from $2.86b and net income of $95.0m into a higher margin profile over time.
Underlying that view is a mix of growth and risk factors. On one side, Envista Holdings is exposed to expanding dental demand, higher R&D spend on digital tools, and a bigger presence in Dental Service Organizations that can drive recurring usage of its platforms. On the other, the narrative flags pressure from China procurement reforms, tariffs, competition in clear aligners, economic sensitivity around discretionary dental work, and currency swings that have already affected reported profitability.
The same framework spells out explicit hurdles for investors to test. Revenue growth is modelled at 3.29% a year with profit margins rising to 6.16%, while the future P/E embedded in the scenario is 29.99x, higher than the sector average quoted in the commentary. That means a lot of the thesis rests on Envista Holdings improving earnings quality and margin mix enough to justify a richer multiple than many Medical Equipment peers.
Put together, the narrative asks readers to judge whether a company that is currently described as trading 48.9% below an internal DCF estimate of $45.96, and 21% below its own narrative fair value of $29.69, has the earnings power and balance of risks to close that valuation gap over time. The recent Q2 beat and improving net profit margin from 2% to 3.3% are part of the argument, but so are the warnings around tariffs, China and lower forecast revenue growth than the broader US market.
Result: Fair Value of $29.69 (UNDERVALUED)
Still, Envista Holdings faces real swing factors, including ongoing China procurement reforms and tariff costs that could pressure revenue and margins if conditions worsen.
Find out about the key risks to this Envista Holdings narrative.
Another View on Envista Holdings: Earnings Multiple Sends a Different Signal
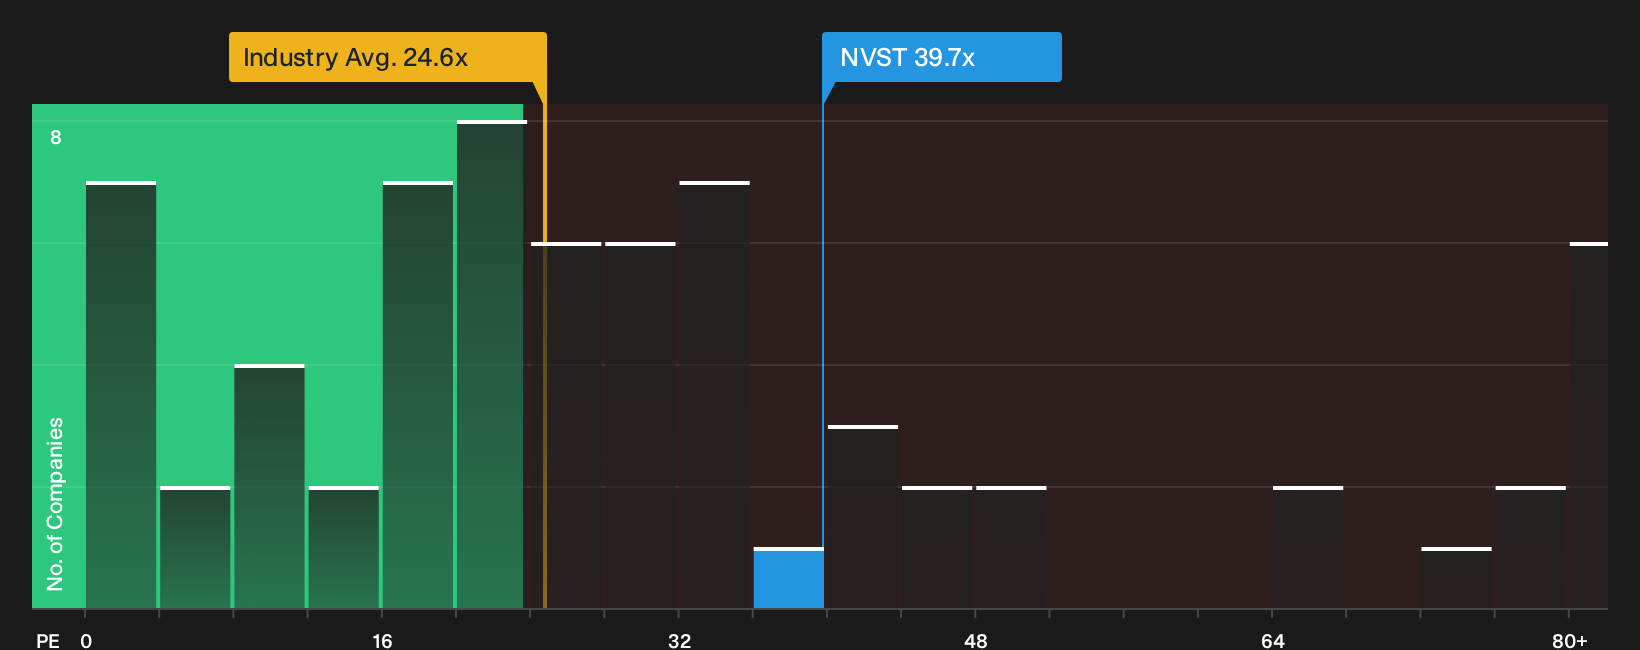
The SWS DCF model points to upside for Envista Holdings, yet the earnings multiple tells a tighter story. NVST trades on a P/E of 39.7x, above both the Medical Equipment industry at 24.7x and peers at 31.1x, and also above the 28x fair ratio. That gap means there is less room for error if the growth narrative slows. Which signal do you trust more right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Envista Holdings has shifted quickly, so it makes sense to pressure test the numbers and form your own take while the Q2 story is fresh. To see what the optimism is built on, review the 4 key rewards.
Looking for more investment ideas beyond Envista Holdings?
If Envista Holdings has you thinking about what else might be hiding in plain sight, this is a good moment to broaden your watchlist before others catch on.
- Spot potential mispricing early by reviewing the 31 high quality undervalued stocks, which combine solid fundamentals with compressed expectations.
- Prioritise capital preservation by scanning the 31 resilient stocks with low risk scores, which show steadier risk profiles when conditions shift.
- Target balance sheet resilience by focusing on the list of solid balance sheet and fundamentals (25 results), which pair financial strength with healthy underlying businesses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com