


PetroChina (SEHK:857) Stock Still Looks Discounted On LNG Canada Expansion News
PetroChina has delivered a powerful 5 year share price run, which puts fresh attention on whether the current valuation is still grounded in what the business earns. With that backdrop, the question for you is how much of the recent story is already reflected in the stock price and how much is being asked of PetroChina’s earnings power.
- Over the past 5 years PetroChina has returned 241.7%, which raises the stakes on whether the market price is now leaning heavily on its earnings profile to keep justifying that move.
- The LNG Canada Phase 2 approval, which doubles that project's planned production capacity to 28 million tonnes per year, can influence expectations for PetroChina's long term earnings potential and capital requirements as its role in the joint venture evolves.
- The analysts covering PetroChina have run their own numbers. See what analysts think PetroChina's shares could be worth.
The issue now is whether PetroChina's recent share price, including a 44.8% gain over the past year, is adequately supported by the earnings performance that underpins it.
If you are questioning whether PetroChina’s earnings fully justify this kind of run, it can help to compare that same earnings lens across 192 high quality undervalued stocks.
Does PetroChina Look Undervalued on Earnings?
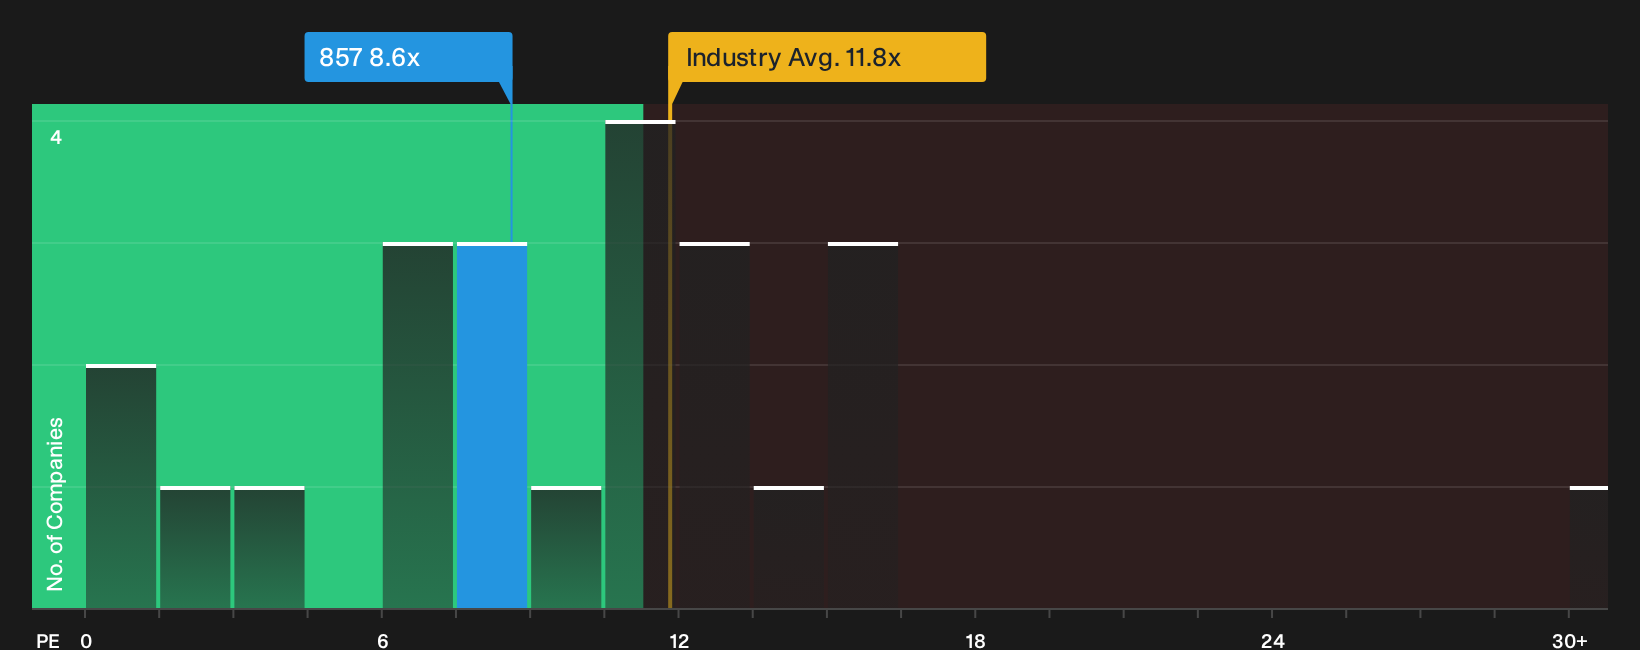
The P/E ratio tends to suit PetroChina because earnings are still a key anchor for how investors judge large integrated oil and gas groups. PetroChina currently trades at about 8.6x earnings, which sits below both the wider oil and gas industry average of roughly 12.6x and a peer group closer to 11.4x. That puts the stock on a lower earnings multiple than many similar businesses you might compare it against.
Because the fair multiple implied by PetroChina’s own profile is higher than the current 8.6x, the shares screen as undervalued on this earnings yardstick. The LNG Canada Phase 2 approval has given the story fresh visibility, yet the stock still trades at a discount to where this model suggests a typical P/E could land for PetroChina’s mix of growth drivers and risks. Explore the numbers behind PetroChina's P/E valuation.
The PetroChina Narrative: What Would Justify Today's Price?
Narratives pick up where PetroChina's P/E puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the share price to sit meaningfully above or below today's level, and they sit on Simply Wall St's Community page. Instead of giving a single output like one multiple or a model line, they describe the future that output leans on, so you can keep checking whether PetroChina's reality still matches it.
A written, number focused Narrative on PetroChina gives you a clear way to spell out what would need to happen for LNG Canada Phase 2 to translate into sustainable earnings power and capital returns that keep supporting today’s valuation. It also creates a record of those assumptions so you can test, refine, or challenge them as new project milestones and financial results arrive over time.
Share your own Narrative for PetroChina and set out the assumptions behind your valuation.
PetroChina’s valuation is only part of the story
Price, earnings and projects are all important, but you also need to know who is steering PetroChina, how their incentives line up with yours, and what that might mean for future decisions. See who runs PetroChina and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com