


Does Pickering Nuclear Contract Win Change The Bull Case For AtkinsRéalis (TSX:ATRL)?
- Aecon Group announced that its long-standing joint venture with AtkinsRéalis and Candu Energy has secured multi-year Pickering Nuclear Generating Station refurbishment work, including a three-year, $1.7 billion Unit 5 contract that will be added to AtkinsRéalis' nuclear backlog in the third quarter of 2026.
- The Pickering life-extension program deepens AtkinsRéalis' role in Canada’s nuclear supply chain, tying its engineering services and project management capabilities directly to long-duration, regulated clean power spending.
- We will now look at how AtkinsRéalis' Pickering life-extension contract could influence the broader investment narrative around its nuclear backlog.
AtkinsRéalis Group Investment Narrative Recap
To own AtkinsRéalis Group, you need to believe its pivot toward higher value engineering and nuclear services can offset lumpier construction exposure and margin volatility. The Pickering refurbishment work ties directly into that thesis by adding long-duration nuclear activity that is scheduled to enter backlog in 2026, although it does not change the near term pressure around lower net margins and recent one off items.
The key short term swing factor is still execution quality on existing large contracts and any further reset to growth expectations in USLA and EMEA. The biggest risk remains revenue concentration in nuclear and large CANDU style projects, where regulatory timing and project delays could disrupt the multi year earnings profile if work is pushed out.
The most relevant update for this Pickering story is the three year, CA$1.7b Unit 5 contract signed by Candu Energy, an AtkinsRéalis company, and Aecon with Ontario Power Generation. That agreement brings engineering, design, project delivery, and program management into one package and is expected to be reflected in the nuclear backlog in the third quarter of 2026.
For you, the link to catalysts is clear. Successful delivery on Unit 5 becomes a reference point for potential follow on activity on Units 6, 7 and 8, subject to approvals. It also tests whether AtkinsRéalis can turn a growing nuclear order book into consistent earnings while managing familiar risks around fixed scope work, cost control, and regulatory driven schedules.
AtkinsRéalis Group's current earnings are CA$2.7b, and analysts forecast earnings of CA$898.7m by 2029. This implies an earnings decline of about CA$1.8b, alongside a projected 6.5% yearly revenue growth rate that underpins a revenue estimate of CA$13.8b and forecast earnings of CA$898.7m in 2029.
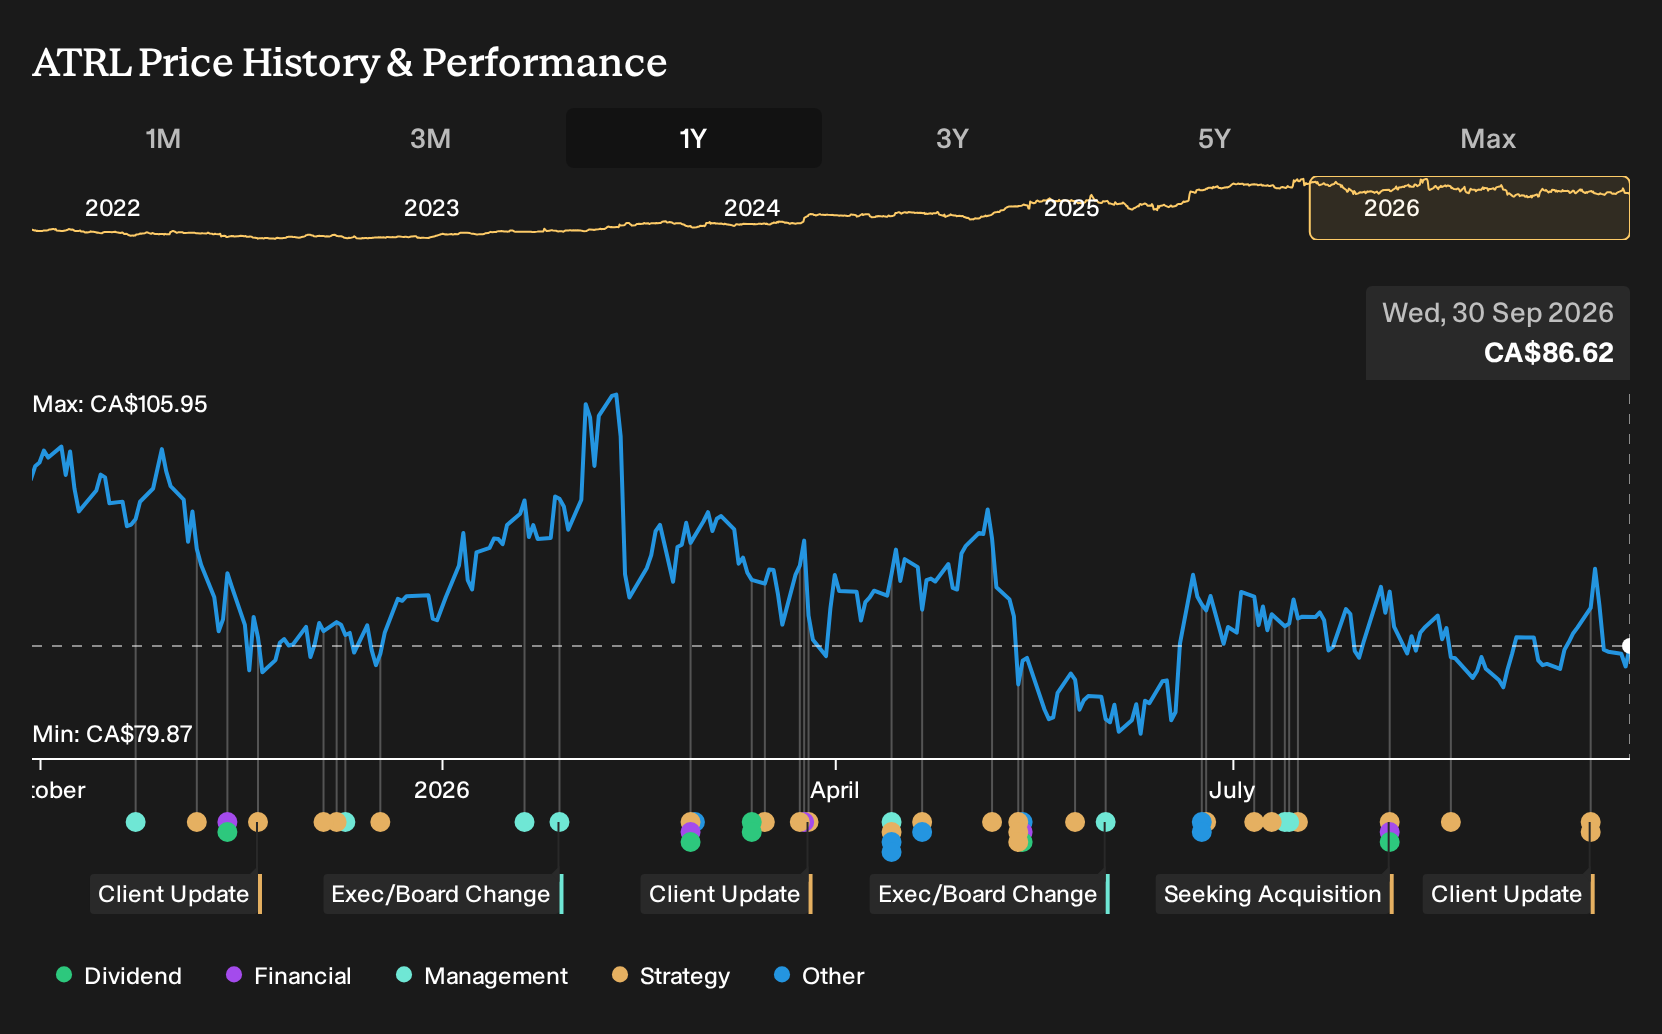
Uncover why AtkinsRéalis Group's fair value indicates a 32% potential upside to its current price, a discount that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster in a tight CA$108.88 to CA$117.29 band, so even retail models disagree only within a narrow range. That was all set before the Pickering refurbishment contracts and nuclear backlog momentum. Consider how project delays, regulatory timing, or further CANDU wins could shift how you view AtkinsRéalis Group’s earnings path.
Explore 3 other AtkinsRéalis Group fair value estimates, including one that suggests as much as 35% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and instincts.
- A great starting point for your AtkinsRéalis Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for AtkinsRéalis Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AtkinsRéalis Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond AtkinsRéalis Group?
If the AtkinsRéalis Group story has sharpened your focus on where long-term projects and balance sheet strength intersect, you can use that same lens across the wider market. The Simply Wall St Screener lets you quickly filter for businesses that better match your risk tolerance, income needs, or preference for under-the-radar opportunities.
- For investors who want undervalued quality with room for rerating, start with a focused set of 7 high quality undervalued stocks that already combine robust cash flows with disciplined capital structures.
- If capital preservation and steadier profiles matter more than chasing every headline, filter for 8 resilient stocks with low risk scores that score well on earnings stability and financial resilience.
- To widen your watchlist with less crowded opportunities, scan a targeted pool of 8 high quality undiscovered gems that pair solid fundamentals with relatively limited current attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com