


Micron (MU) Stock May Be Below Fair Value After Record AI Earnings
Micron Technology has turned into one of the strongest performers in the semiconductor space. The sheer scale of that run now puts a simple question in front of you as an investor: Has the move in Micron’s share price pushed expectations for its earnings to a level that the business can realistically sustain?
- Over the past 3 years Micron has delivered a very large share price gain of about 1,460%, which makes it important to ask how much of that is supported by its current and future earnings power.
- Recent headlines around record profitability, AI driven memory demand and major long term investment plans suggest the company may be entering a phase where earnings can be more closely tied to high capital spending and margin execution.
- There is a second opinion on Micron Technology worth weighing. See what analysts think Micron Technology's shares could be worth.
The issue now is whether Micron’s current earnings, and what the market expects those earnings to become, are enough to justify today’s valuation.
If you want a second reference point alongside Micron Technology, consider using a focused screen of 90 AI infrastructure stocks.
Is Micron Technology a Bargain on Earnings?
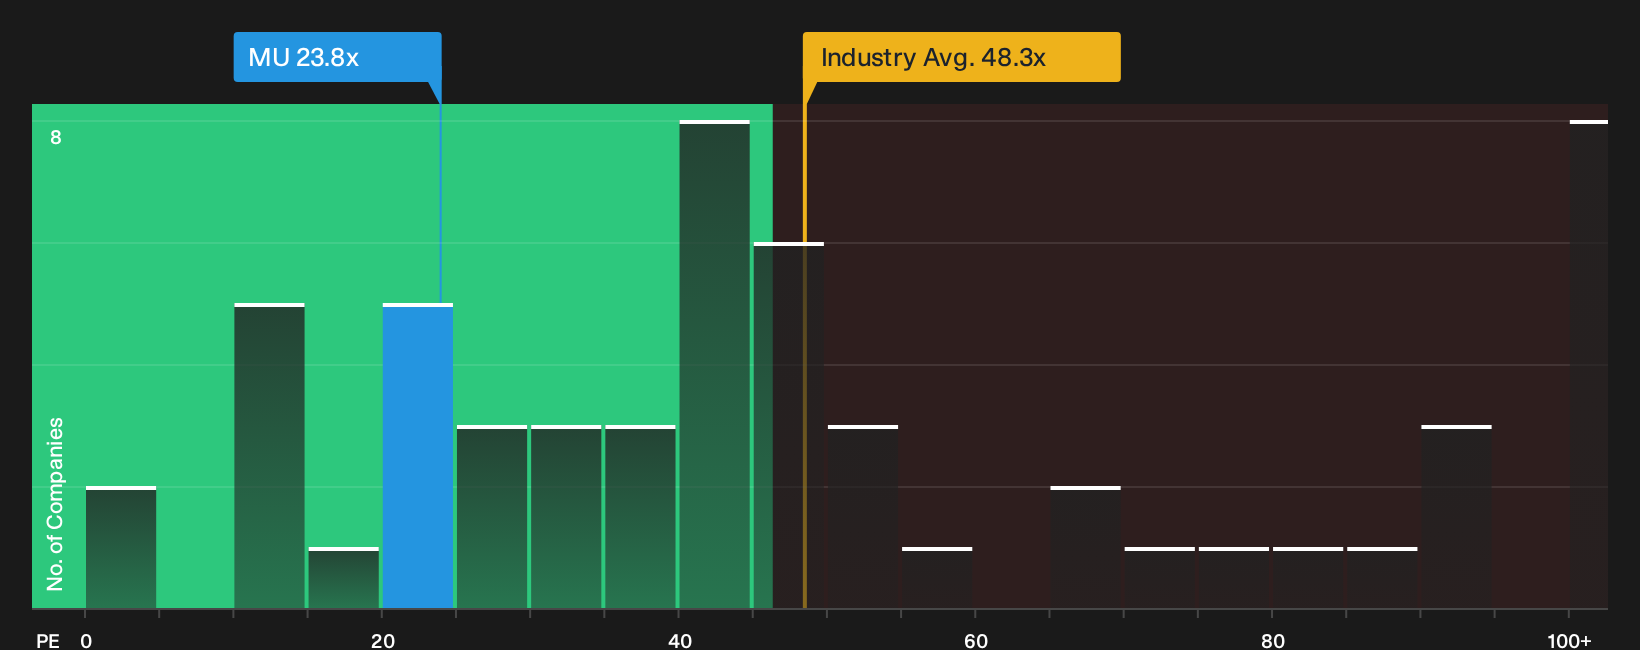
The P/E ratio fits Micron Technology because profit is what ultimately needs to support the huge capital spending that its memory business requires. At about 23.8x earnings, Micron trades well below the broader semiconductor sector on 48.3x and also below a peer group that clusters closer to 78.6x. That gap suggests the market currently prices Micron at a sizeable discount to many chip stocks that also rely heavily on AI related demand.
Record recent results tied to AI driven memory demand have pushed sentiment higher, yet the P/E still sits under the level suggested by a tailored fair multiple that blends Micron’s growth profile, margins, scale and risk. For an investor trying to weigh whether the rally has run too far, the valuation signal here is that the market price does not fully reflect the earnings multiple implied by those fundamentals. Explore the numbers behind Micron Technology's P/E valuation.
The Micron Technology Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Micron Technology pick up where the P/E puzzle leaves off and explain which potential paths for growth, profitability and earnings would need to occur for the share price to appear meaningfully higher or lower than it is today. Each narrative links its valuation outcome to a specific view on how Micron Technology's expansion, margins and risk profile could change, providing a framework you can revisit as new results and guidance are released.
Community views on Micron Technology are split between those who see an AI driven earnings reset and those who are wary of how long that pricing power really lasts.
Bull case: 15% undervalued
"AI has pulled memory from the commodity bucket into the strategic infrastructure bucket, Micron has now signed 16 strategic customer agreements..."
Discover why this Narrative puts Micron Technology at 15% undervalued.
Bear case: 94% overvalued
"The real question is how long pricing power lasts, They are sold out for 2026, but i do not know about '27's status..."
Explore why this Narrative puts Micron Technology at 94% overvalued.
One more Micron Technology signal that deserves a closer look
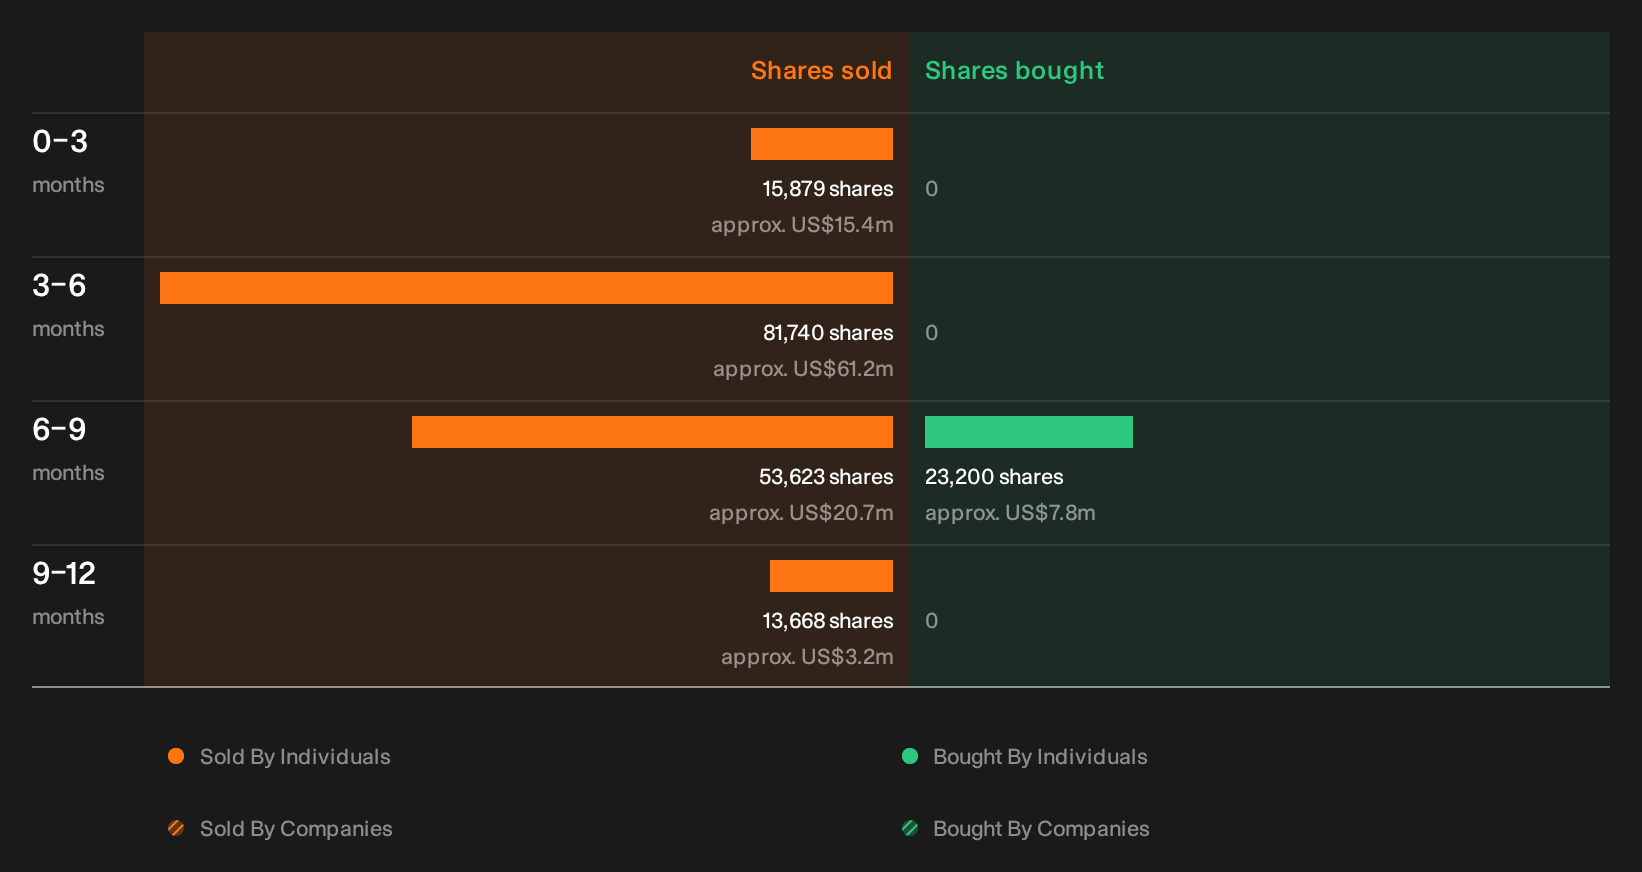
Before wrapping up your work on Micron Technology, it is worth checking what recent trades by senior insiders might hint about how those individuals view the current setup. See the recent insider selling flagged for Micron Technology.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com