


Why Super Micro Computer Stock Has More Room to Run
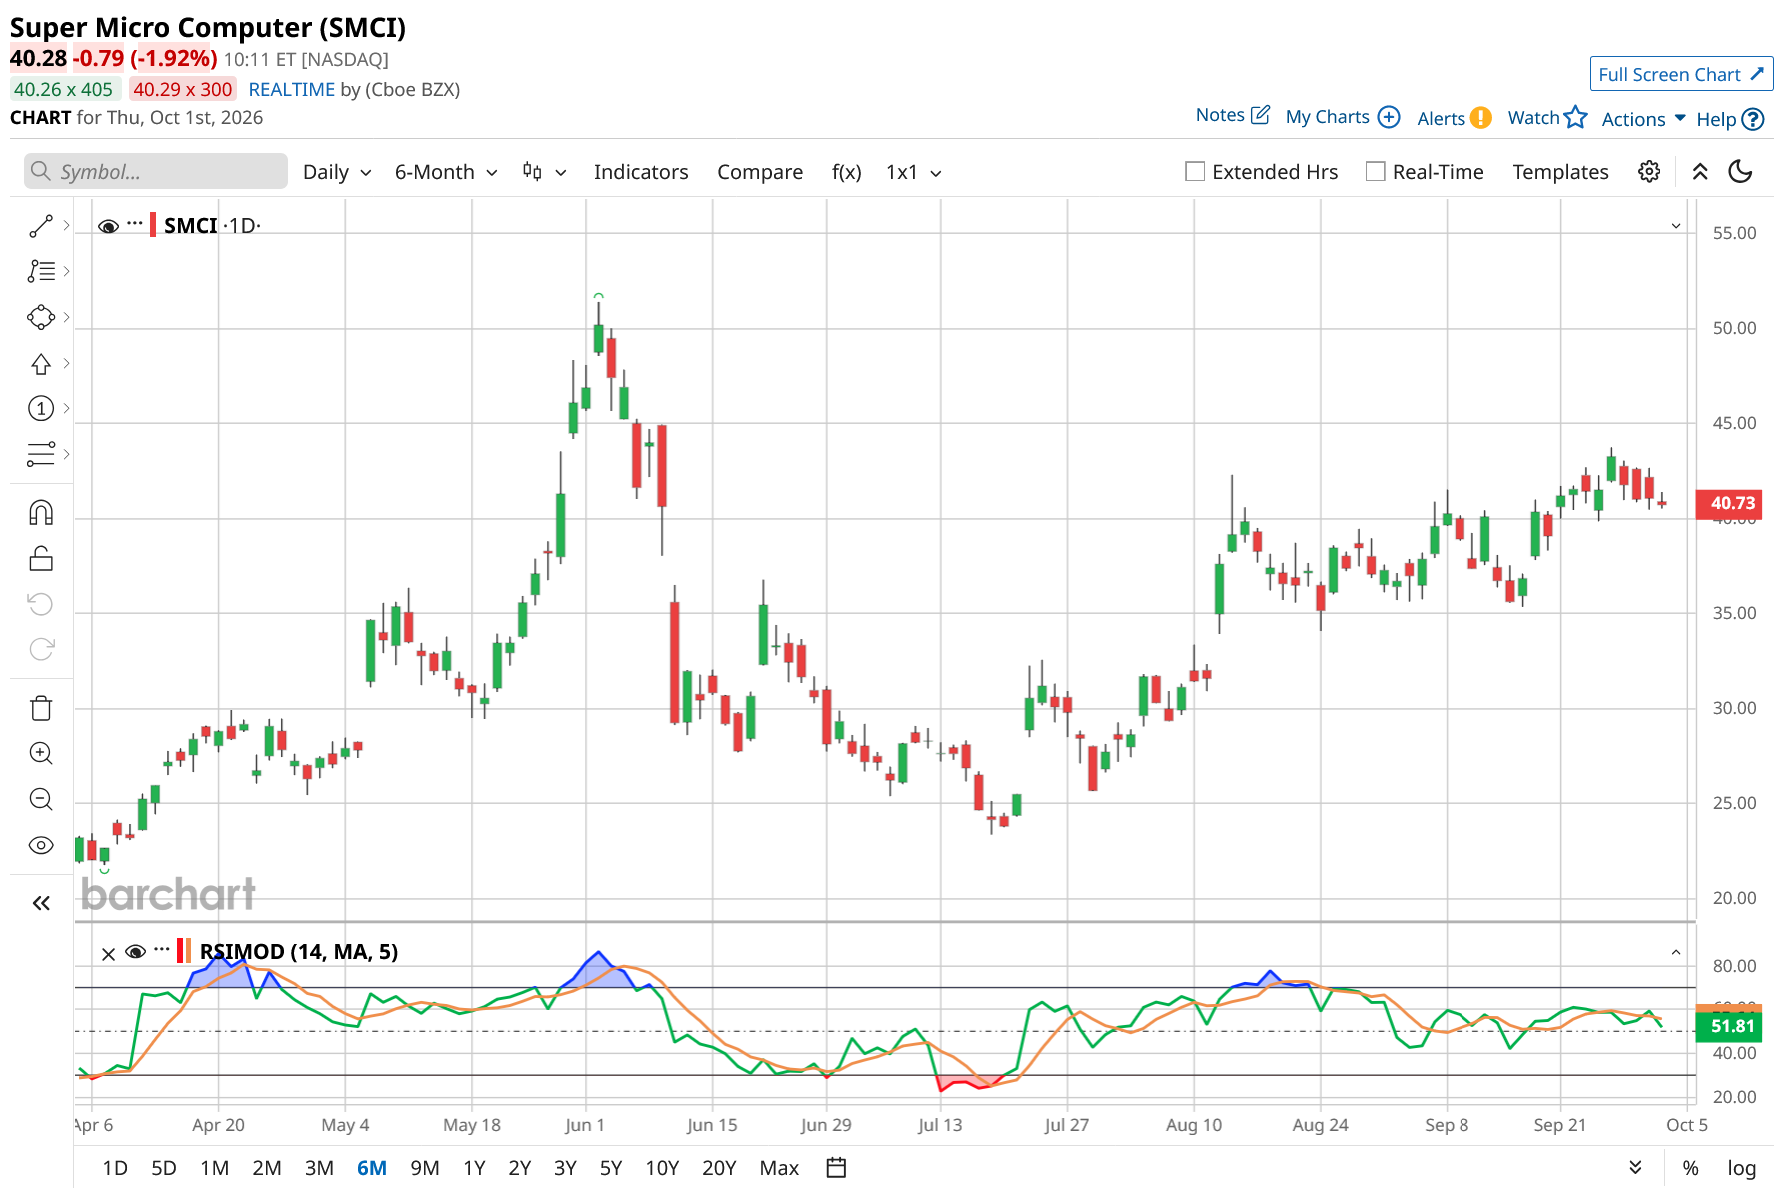
Super Micro Computer (SMCI) has witnessed a significant recovery, with its shares gaining more than 47% over the past three months and nearly doubling over the last six months. While SMCI stock has recovered swiftly, the company’s underlying business momentum suggests it has more room to run.
A key factor supporting the growth outlook is sustained demand for Super Micro Computer’s AI-optimized servers and IT infrastructure solutions. As enterprises and data center operators continue to expand their AI computing capacity, demand for high-performance infrastructure remains an important potential growth driver for the company.
Super Micro’s record backlog further indicates strong customer demand. Valuation is also a significant part of the investment case. Despite the substantial appreciation in SMCI shares, the stock still looks attractive relative to its growth potential.
Super Micro’s Growth Trajectory Remains Solid
Super Micro Computer entered fiscal 2027 with strong growth momentum, driven by sustained AI infrastructure demand, a record order backlog, and a broader enterprise customer base. In FY26, SMCI’s revenue surged 78% year-over-year (YoY) to $39.1 billion, while adjusted EPS increased 76% to $3.63.
Looking ahead, SMCI’s management expects AI-related solutions to represent more than 80% of revenue over the next several quarters, supported by more than $60 billion of new orders secured in Q4. This backlog provides substantial revenue visibility, although the pace at which these orders are converted into sales will remain an important factor.
Enterprise and channel revenue reached $5.6 billion in Q4, representing half of total quarterly sales, compared with 28% in the preceding quarter. Further, the 172% YoY increase and 98% sequential growth point to rapidly increasing adoption among customers upgrading compute, storage, and networking infrastructure. Meanwhile, revenue from OEM appliances and large data center customers reached $5.5 billion, up 50% YoY.
Customer diversification further strengthens the growth profile. SMCI had nine customers generating more than $1 billion in annual revenue during FY26, up from four in FY25. A wider customer base could provide greater resilience as AI infrastructure spending evolves across hyperscale, enterprise, and channel markets.
Super Micro is also improving margins. Adjusted gross margin improved sharply to 17.6% in Q4 from 10.1% in Q3, driven primarily by changes in product and customer mix. While the Q4 margin level should not necessarily be viewed as a sustainable run rate, several factors indicate its margins could improve in the quarters ahead.
These include greater adoption of higher-value inference and Agentic AI systems, increased deployment of Data Center Building Block Solutions (DCBBS), factory automation, design optimization, and improved manufacturing yields. Together, these initiatives could gradually shift SMCI toward a higher-value and more profitable revenue mix.
Overall, SMCI’s growth trajectory remains supported by strong demand for Hyper Servers and GPU & Super Racks, including both liquid-cooled and air-cooled systems, which are more complex and higher-value products.
At the same time, SMCI has expanded its enterprise CPU-based server, storage, and IoT product offerings, positioning the company to capture a broader range of infrastructure demand. Its rapidly expanding portfolio of inferential and Agentic AI-focused products could also contribute to a healthier product mix and support profitability over time.
Taken together, strong AI infrastructure demand, a substantial order backlog, customer diversification, and opportunities to improve product mix and manufacturing efficiency provide multiple potential drivers for SMCI’s continued growth into FY27 and beyond.
SMCI’s Valuation Is Still Attractive
Super Micro Computer stock has recovered swiftly. However, its valuation still looks attractive. SMCI is trading at approximately 10.7 times forward earnings, which is low relative to its EPS growth trajectory. Analysts expect SMCI to deliver EPS growth of 20.8% in FY27 and 24.4% in FY28.
SMCI stock also trades at a discount to its peers. Dell Technologies (DELL) trades at 22.4 times forward earnings, while Hewlett Packard Enterprise (HPE) trades at around 18.8 times.
The Bottom Line: SMCI Stock Has Room to Run
Driven by robust AI-related demand, expectations for double-digit earnings growth, and a relatively modest valuation, SMCI stock has room for further upside.
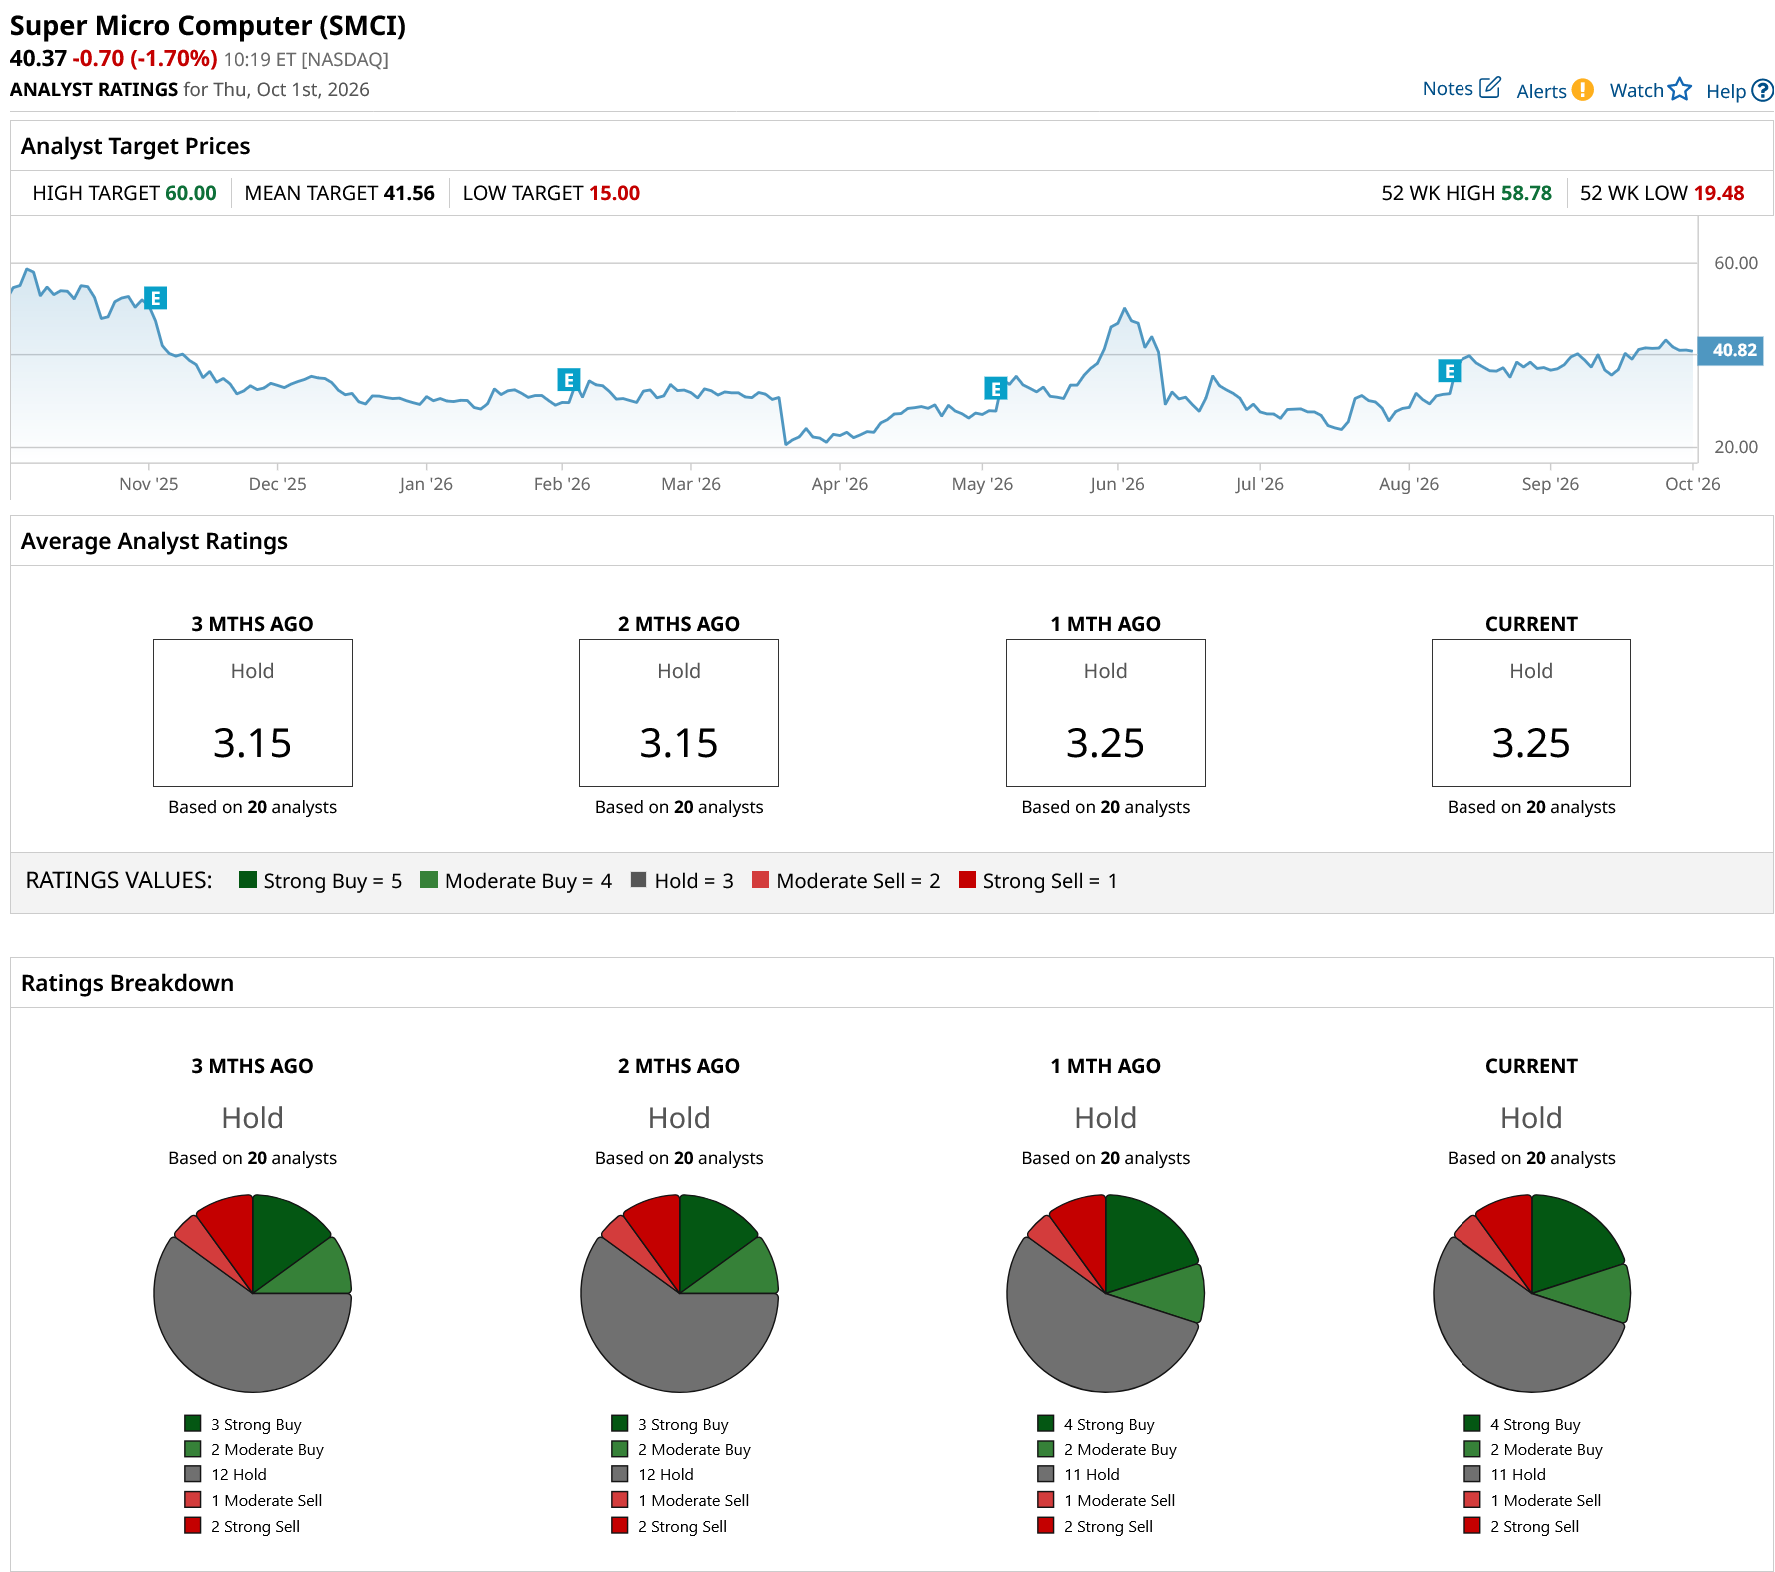
Wall Street currently has a “Hold” consensus rating on SMCI. Meanwhile, the Street’s highest price target of $60 suggests approximately 47% potential upside from its current trading level.
On the date of publication, Sneha Nahata did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.