


Centrus Energy (LEU) Lands A New HALEU Deal, Is The Stock Still Cheap?
Centrus Energy’s new HALEU contract and conference spotlight
Centrus Energy (LEU) has drawn fresh attention after signing a multi-year HALEU supply agreement with Antares Nuclear, followed by a scheduled presentation at the ROTH Critical Mass in Emerging Nuclear Technology Conference in New York.
For context, Centrus Energy shares trade at US$139.49 after a 1-day share price return of 0.95%, yet the stock is down 18.62% over 30 days and 48.81% year to date. The 3-year total shareholder return of 168.51% signals that longer term momentum has been strong, despite a 57.87% total return decline over the past year as investors reassess growth potential and risk around new HALEU contracts and upcoming conferences.
Scan beyond Centrus Energy and see how other nuclear infrastructure players are positioned with the curated 18 nuclear energy infrastructure stocks for this theme.
The sharp one-year slide against a strong three-year gain leaves Centrus Energy looking like either a business mispriced or a mood swing in the chart. The valuation section tests which reading fits better.
Most Popular Narrative: 26.6% Undervalued
Centrus Energy’s most followed valuation narrative pegs fair value at $190 per share, well above the recent $139.49 close. This frames the current pullback very differently from the one year chart.
Centrus Energy (LEU) offers the most direct public-market exposure to U.S. HALEU production, a critical bottleneck for advanced nuclear deployment.
HALEU fuel scarcity could constrain next-gen reactor rollouts, making LEU's enrichment capabilities strategically vital as AI-driven electricity demand surges.
See why 38 investors see Centrus Energy as 27% undervalued.
Result: Fair Value of $190 (UNDERVALUED)
Still, the Centrus Energy thesis could be knocked off course if government HALEU funding slows or if rival enrichment projects ramp faster than expected.
Find out about the key risks to this Centrus Energy narrative.
Another view on Centrus Energy’s valuation
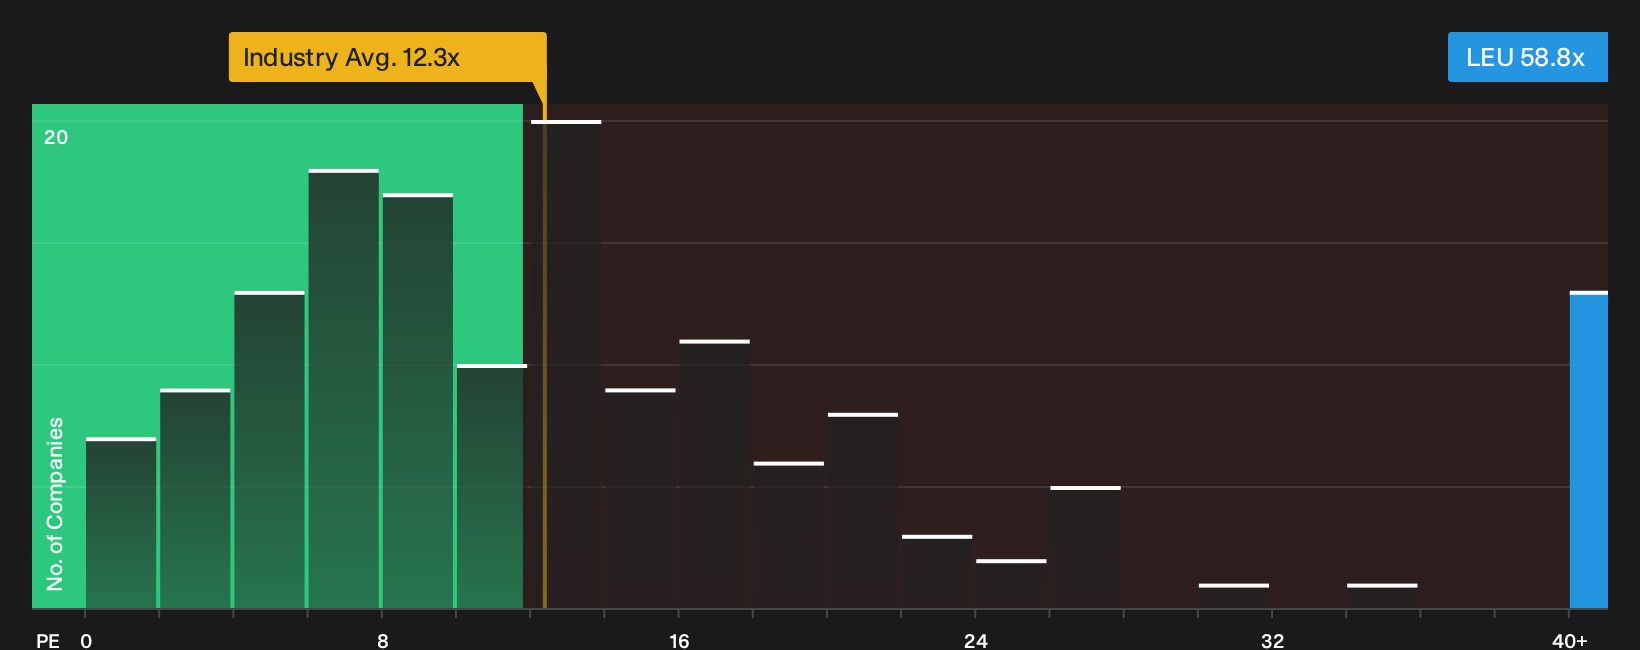
The HALEU narrative presents Centrus Energy as 26.6% undervalued at $190 per share, yet the earnings multiple tells a tougher story. The stock trades on a P/E of 58.8x, compared with 21x for peers, 12.3x for the US Oil and Gas industry, and a fair ratio of 10.7x. That gap points to meaningful valuation risk if sentiment cools. Which signal do you trust more: the story or the sticker price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the mix of optimism and caution around Centrus Energy? Move quickly, review the data, and weigh the 1 key reward and 2 important warning signs.
Looking for more Centrus Energy style investment ideas?
If Centrus Energy has sharpened your focus on where capital flows next, do not stop here. Broader opportunities often emerge where few investors are currently looking.
- Target potential mispricing by scanning a curated 31 high quality undervalued stocks and see which companies the data suggests may trade below their fundamentals.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (25 results) so you can focus on businesses with stronger financial footing.
- Get ahead of the crowd by searching a 19 high quality undiscovered gems and spot quality ideas before they hit everyone’s radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com