


What’s Behind Iovance Biotherapeutics (IOVA) Latest Move?
Iovance Biotherapeutics (IOVA) just raised its 2026 revenue outlook to a range of US$410 million to US$420 million, citing strong U.S. demand for Amtagvi and Proleukin as well as record quarterly product revenue.
That guidance upgrade has come amid a powerful share price surge. Iovance Biotherapeutics has a 30-day share price return of 78.99% and a 90-day gain of 243.85%, while the 1-year total shareholder return is very large. However, the 5-year total shareholder return is still down 44.45%, which suggests momentum has recently shifted from an extended period of weak performance to strong optimism around the current product ramp.
Scan how Iovance Biotherapeutics fits into the broader move in cancer care by comparing it with hand-picked 36 healthcare AI stocks targeting treatment breakthroughs and data-driven therapies.
Bulls point to Iovance Biotherapeutics’ sharp guidance lift and record Amtagvi demand, while bears stress ongoing losses and a long commercialization road. Which story does the current valuation most closely align with?
Most Popular Narrative: 17.7% Undervalued
Iovance Biotherapeutics last closed at $14.82, while the leading narrative fair value sits at $18. This frames the current rally as still leaving upside on the table according to that view.
In my opinion, Iovance is one of those biotech companies where the market is still focused on what went wrong in the past instead of what could happen over the next few years. After a disappointing commercial launch in 2025, many investors lost confidence and the share price fell sharply. However, I believe the company today is much stronger than the market gives it credit for.
See why 22 investors see Iovance Biotherapeutics as 18% undervalued.
Result: Fair Value of $18 (UNDERVALUED)
Still, Iovance Biotherapeutics faces clear pressure points, including continued net losses of US$289.5 million and reliance on strong Amtagvi uptake to support its higher 2026 outlook.
Find out about the key risks to this Iovance Biotherapeutics narrative.
Another View: Iovance Biotherapeutics Looks Expensive On Sales
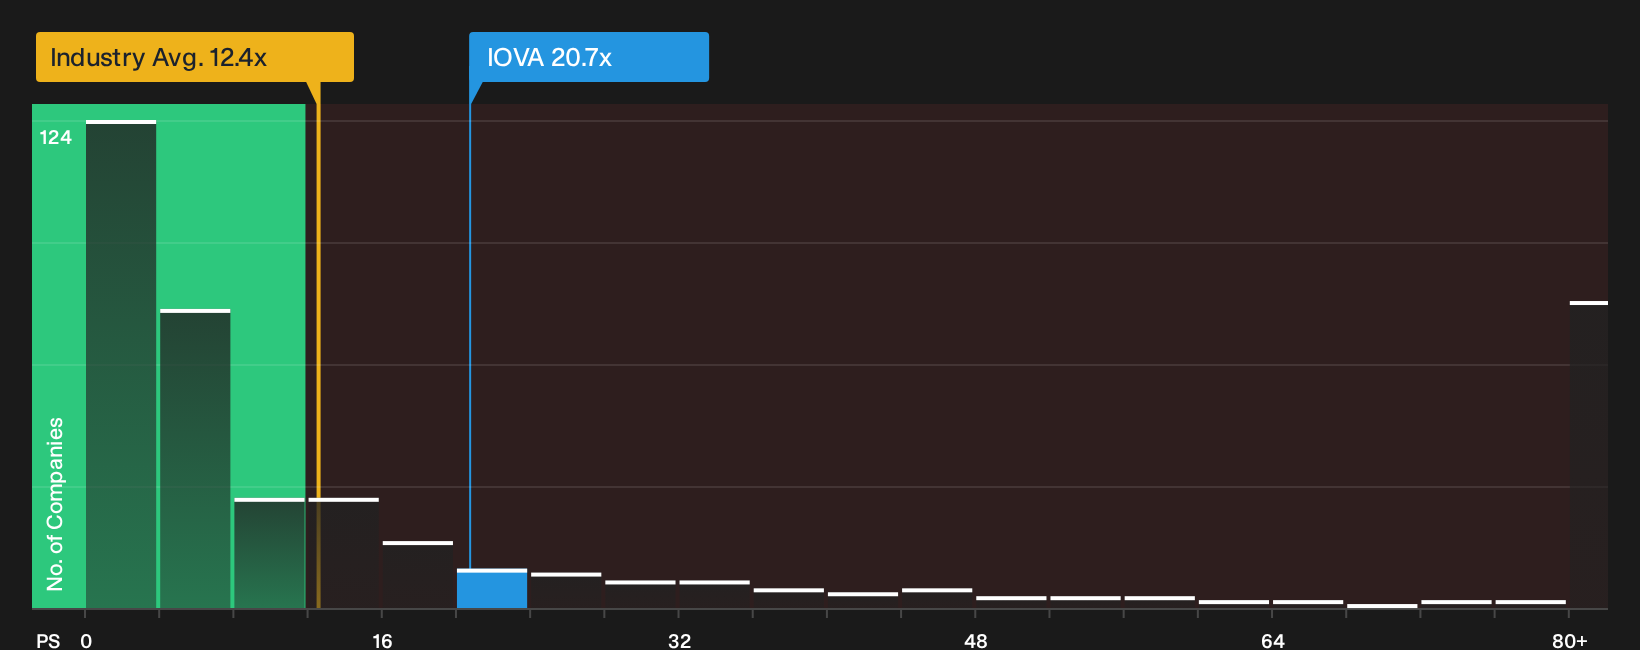
The SWS DCF model presents Iovance Biotherapeutics as deeply undervalued at $53.17 per share, yet the simple sales multiple points in the opposite direction. The stock trades on a P/S of 20.7x versus 12.4x for US biotechs and a fair ratio of 9.5x, which suggests meaningful valuation risk if sentiment cools.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Iovance Biotherapeutics is clearly split, so treat this rally as a prompt to review the numbers yourself and then weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Iovance Biotherapeutics?
Do not stop your research with Iovance Biotherapeutics when a broader watchlist could highlight better fits for your goals, risk profile, and time horizon.
- Target future upside by checking a curated set of quality companies that currently look cheap on fundamentals through the 31 high quality undervalued stocks.
- Prioritise resilience by scanning a 31 resilient stocks with low risk scores that focuses on businesses with steadier profiles and fewer red flags.
- Hunt for potential future leaders by reviewing a 19 high quality undiscovered gems that highlights strong fundamentals before they hit the spotlight.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com