


Earnings Beat Might Change The Case For Investing In CRA International Stock (CRAI)
- CRA International recently presented at the Noble Capital Markets Virtual Equity Investor Conference and appointed Patrick Hillan as a Vice President in its Life Sciences Practice, alongside reporting Q2 2026 sales and earnings per share that were higher year over year.
- The combination of stronger recent operating results, rising demand for complex regulatory and antitrust advisory work, and added life sciences leadership indicates management focus on deepening high-value consulting capabilities across key sectors.
- We will now see how CRA International's investment narrative might be influenced by the new life sciences leadership hire and recent results.
Scan CRA International’s peers turning complex regulation into revenue by reviewing the hand-picked 31 high quality undervalued stocks that share similar consulting and compliance themes.
CRA International Investment Narrative Recap
To own CRA International, you need to believe that complex regulation, litigation and M&A activity will keep clients leaning on premium economic advice, and that the firm can keep turning this into solid projects across antitrust, life sciences and broader consulting. Recent Q2 2026 results with higher sales and EPS support that operating backdrop, but do not radically change the short term story.
The key near term swing factor is whether CRA International can keep utilisation and pricing firm while consultant headcount stays roughly flat and clients push for more work at sharper fees. The biggest immediate risk is concentration in a few strong practices combined with debt that is not well covered by operating cash flow if activity cools.
The addition of Patrick Hillan as a Vice President in the Life Sciences Practice ties directly into the catalyst around growing work in healthcare and life sciences. It gives CRA International more depth in medical affairs and launch support at a time when clients are wrestling with complex evidence requirements and reimbursement rules across geographies.
For investors, the practical question is whether this leadership hire helps shift more revenue toward higher value engagements that can support pricing and offset any future fee pressure in more commoditised areas. Execution risk sits in integrating new senior experts, winning incremental mandates and doing it without stretching margins further in a business already carrying debt and substantial buybacks.
CRA International's current analyst storyline points to revenues of $890.9 million and earnings of $74.0 million by 2029, built on assumed yearly revenue growth of 4.9% and an increase in profit from $47.8 million today. This implies an earnings uplift of about 55% by the forecast year.
Uncover why CRA International's fair value indicates a 54% potential upside to its current price, which could narrow quickly.
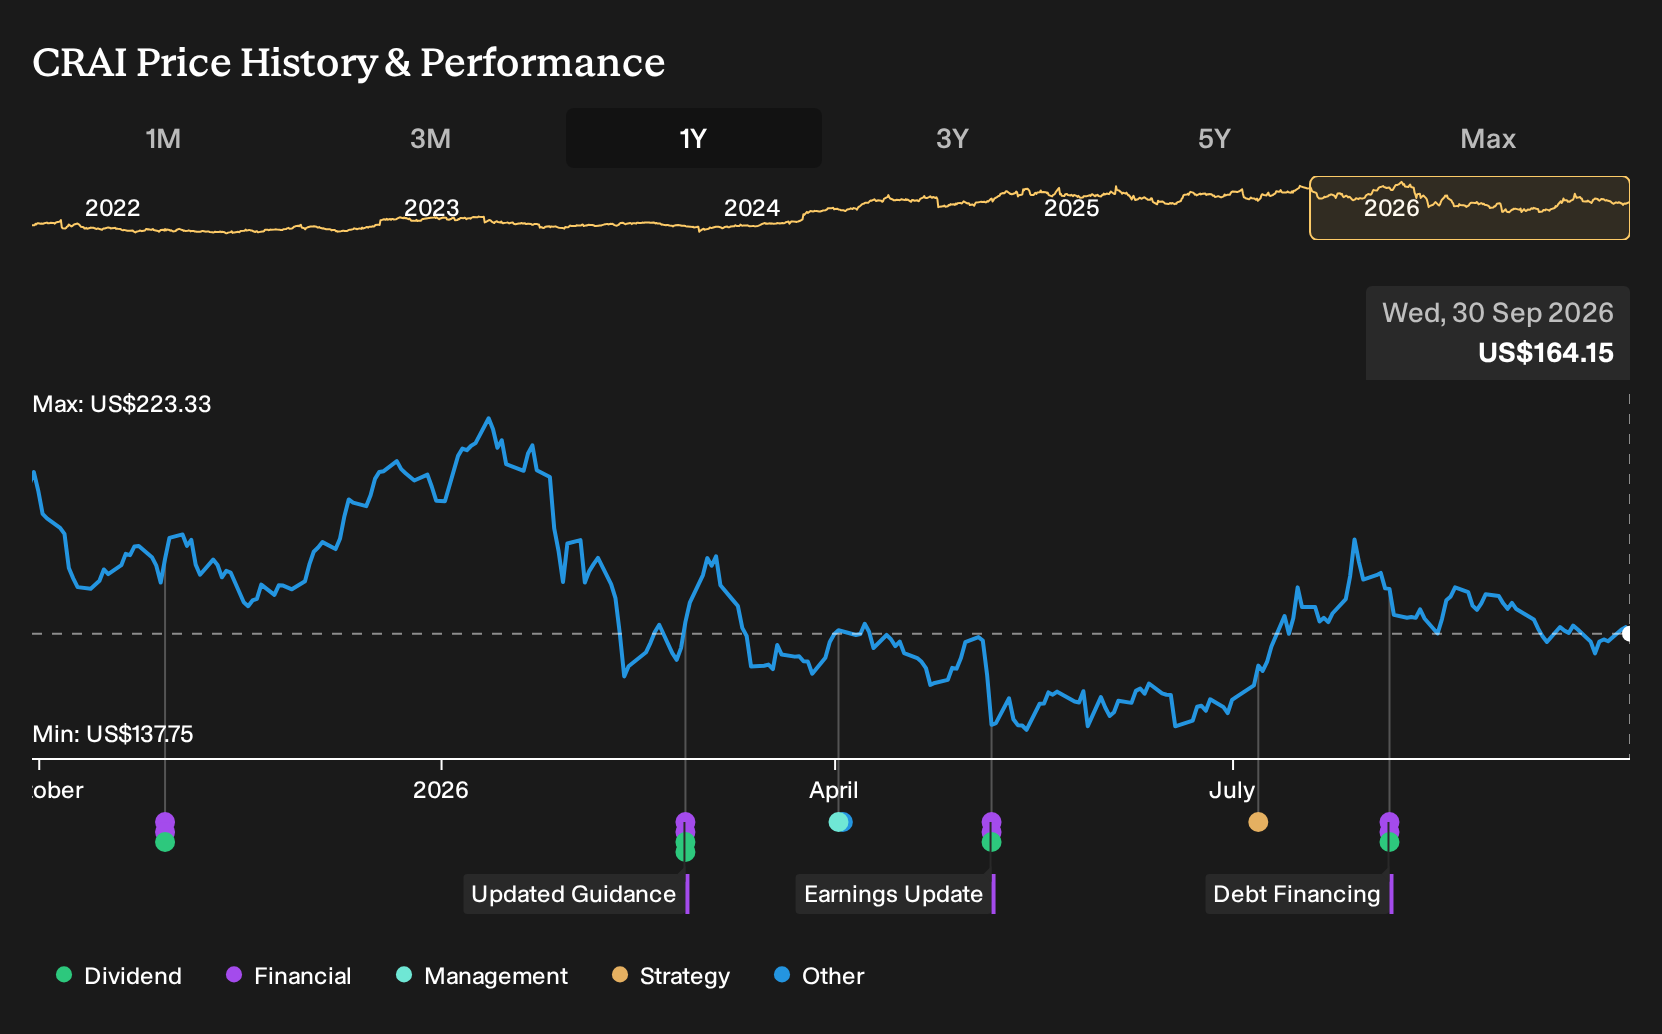
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$252 to more than US$800 per share, which is a huge gap for CRA International. That spread reflects how differently private investors model regulatory demand, M&A cycles and talent costs. Use it as a prompt to test several contrasting viewpoints before acting.
Explore another CRA International fair value estimate, including one that suggests as much as 387% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CRA International research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CRA International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CRA International's overall financial health at a glance.
Looking For More Investment Ideas Beyond CRA International?
If the CRA International story has you thinking about where else complex business models and solid fundamentals might create opportunity, the Simply Wall St Screener is a useful next step. You can filter for financial traits that matter to you and surface a focused set of candidates rather than scrolling through tickers at random.
- Prefer companies that already look mispriced on fundamentals and quality metrics? Start with a curated set using the 31 high quality undervalued stocks.
- If income is a priority and you want businesses with higher yields, take a closer look at the 7 dividend fortresses as a starting universe.
- For those who care most about resilient finances and cleaner balance sheets, narrow your watchlist with the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com