


Helios Technologies (HLIO) Could Be 28% Undervalued After Reaffirming Its Dividend
Dividend affirmation puts Helios Technologies in focus
Helios Technologies (HLIO) has reaffirmed its shareholder payout, with the board declaring a quarterly cash dividend of $0.12 per share, payable on October 26, 2026, to holders of roughly 33.0 million shares.
Recent trading has cooled, with the share price down 6.98% over 30 days and 17.56% over 90 days, yet Helios Technologies still shows a 24.15% year to date share price return and a 30.48% 1 year total shareholder return. This points to momentum that has eased but not reversed.
Scan income-focused opportunities that look similar to Helios Technologies by reviewing the hand picked 7 dividend fortresses highlighted for resilient payout potential and balance sheet strength.
Recent weakness has given Helios Technologies a lower entry point while the dividend signal remains intact. Is it worth stepping in now, or does patience for a deeper pullback look more sensible once valuation is on the table next?
Most Popular Narrative: 28% Undervalued
On the numbers, Helios Technologies is framed as undervalued, with a narrative fair value of about $94.67 against a last close of $67.92, and that gap is being tied to a mix of automation exposure, capital returns and improving guidance rather than a single short term catalyst.
Rapid expansion in new product launches, including incremental, non-cannibalizing value-add solutions and IoT-enabled platforms, positions Helios to capture greater share from ongoing adoption of automation, robotics, and digitalization in global industrial markets, potentially supporting future revenue and higher average selling prices. The shift in the industry towards electrification of mobile and industrial equipment is driving OEM demand for sophisticated electro-hydraulic and electronic control solutions, areas where Helios is actively innovating (e.g., Enovation Controls, Cygnus Reach). These developments are described as contributing to both top-line growth and margin expansion over the medium to long term.
See why 5 investors see Helios Technologies as 28% undervalued.
Result: Fair Value of $94.67 (UNDERVALUED)
Still, Helios Technologies faces pressure if demand in cyclical end markets softens again or if slower adoption of advanced control solutions reduces its pricing power.
Find out about the key risks to this Helios Technologies narrative.
Another View: Helios Technologies On Earnings Multiples
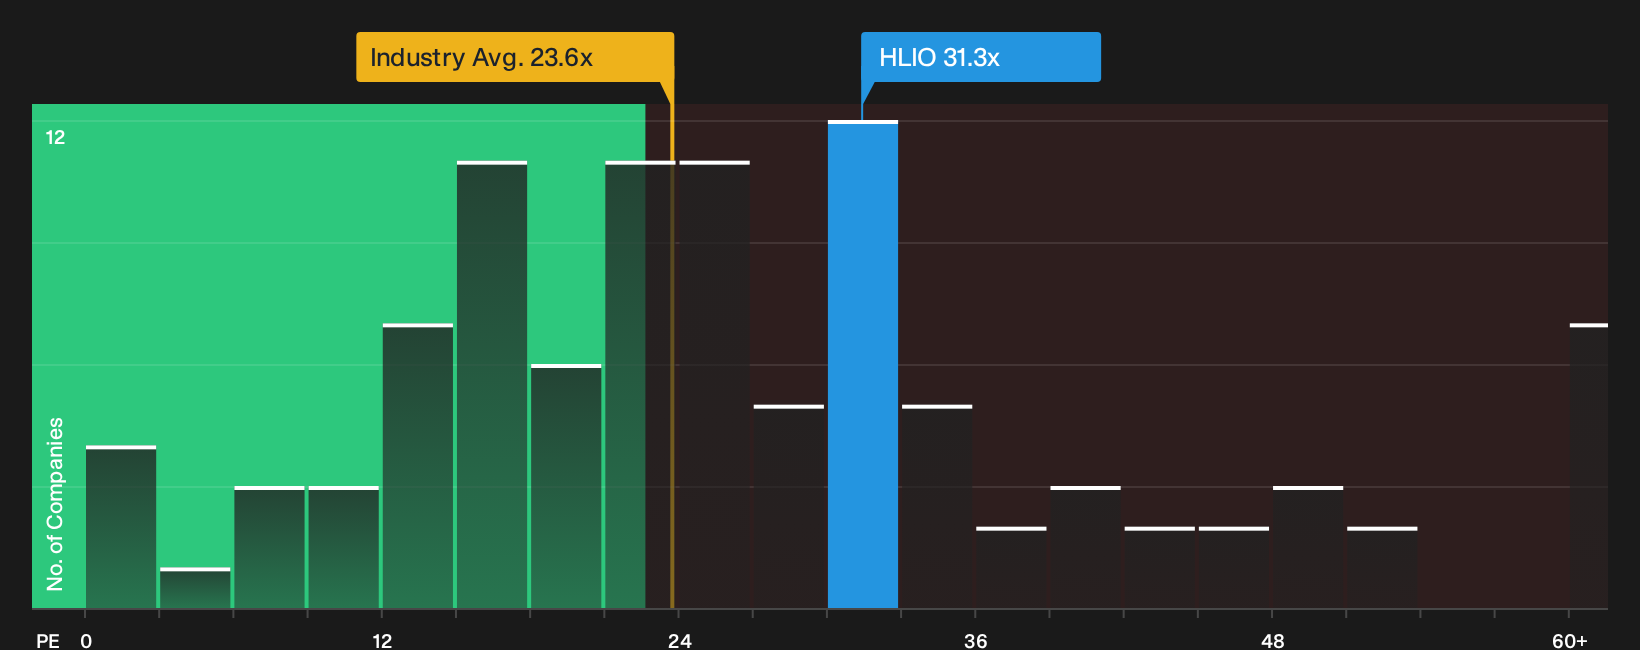
The earlier fair value of $94.67 for Helios Technologies leans on future earnings estimates and a discount rate. On today’s P/E of 31.3x, the stock trades richer than the US Machinery industry at 24.2x and above a fair ratio of 21.6x, which points to valuation risk if expectations cool.
The gap between the current P/E, peers at 33x, and the lower fair ratio suggests the market is paying up for Helios Technologies while still pricing in a premium to its own historical earnings power. The question for investors is whether earnings progress can keep justifying that heavier multiple or if a reset in expectations drags the price back toward the fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Helios Technologies can feel confusing, so it may help to look at the underlying data now and decide where you stand on the balance of risk and reward. To frame that decision with both caution and potential upside in mind, review the 4 key rewards and 1 important warning sign.
Looking for more Helios Technologies style investment ideas?
Do not stop your research with Helios Technologies alone. The right watchlist often starts with a few strong ideas and then widens into a deeper opportunity set.
Scan fresh opportunities that match your risk and income goals using the Simply Wall St Screener, so you are not relying on a single stock story.
- Target stability first and seek out companies with resilient finances through a focused list of solid balance sheet and fundamentals (25 results) that helps you avoid fragile balance sheets.
- Hunt for quality at a discount by reviewing the 31 high quality undervalued stocks that filters for stronger fundamentals at prices that may not fully reflect them.
- Lock in potential cash flow ideas by checking the 7 dividend fortresses that highlights payout track records and financial strength to support those distributions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com