


Is Mitsui (TSE:8031) Cheap After Its Texas Solar Project Went Live?
Mitsui (TSE:8031) has crossed an important marker in its energy shift, with the 150 MWdc Three W Solar facility in Texas now completed and handed over for ongoing operation.
Mitsui’s share price has been choppy in recent weeks, with a 1-day share price return of 2.09% after the Texas solar update, but a 7-day share price return down 4.48% and a 30-day share price return down 1.58%, suggesting momentum has cooled. Even so, the longer record tells a different story, with an 8.33% 90-day share price return alongside a 1-year total shareholder return of 38.74% and a 5-year total shareholder return of 366.84%. This points to investors having been rewarded for staying invested through shorter-term swings as Mitsui builds out projects like Three W Solar.
Scan for other energy transition plays with fundamentals similar to Mitsui by reviewing the hand picked 39 power grid technology and infrastructure stocks alongside this solar milestone.
Mitsui looks like a powerful, diversified operator, from LNG to Texas solar. The harder call is whether a ¥4,930 share price already reflects that strength or still leaves room on the table.
Most Popular Narrative: 20% Undervalued
Mitsui’s most followed valuation storyline points to a fair value of about ¥6,167 compared with the recent ¥4,930 close. This puts the focus squarely on what needs to go right for that gap to close.
Mitsui's ongoing investments in LNG, low-carbon ammonia, and related infrastructure projects (such as Blue Point and Ruwais LNG) position the company to capture growth from the increasing global demand for cleaner energy sources, likely boosting revenue and long-term earnings stability as the energy transition accelerates.
See why 21 investors see Mitsui as 20% undervalued.
Result: Fair Value of ¥6,167 (UNDERVALUED)
Still, heavy exposure to commodity cycles and the risk of costly overseas expansion missteps could challenge the underpriced Mitsui narrative if conditions turn against it.
Find out about the key risks to this Mitsui narrative.
Another View: Mitsui Through A Cash Flow Lens
The story looks different when Mitsui is assessed using the SWS DCF model. On that scorecard, the share price of ¥4,930 sits above an estimated future cash flow value of ¥4,035, which points to the stock looking overvalued on this framework rather than undervalued.
That gap matters because it reflects a market price that already builds in richer cash flow expectations than the model supports, leaving less room for disappointment if projects or commodity conditions underperform. It raises a simple question for investors studying Mitsui: which version of fair value feels more realistic based on their own assumptions.
Look into how the SWS DCF model arrives at its fair value.
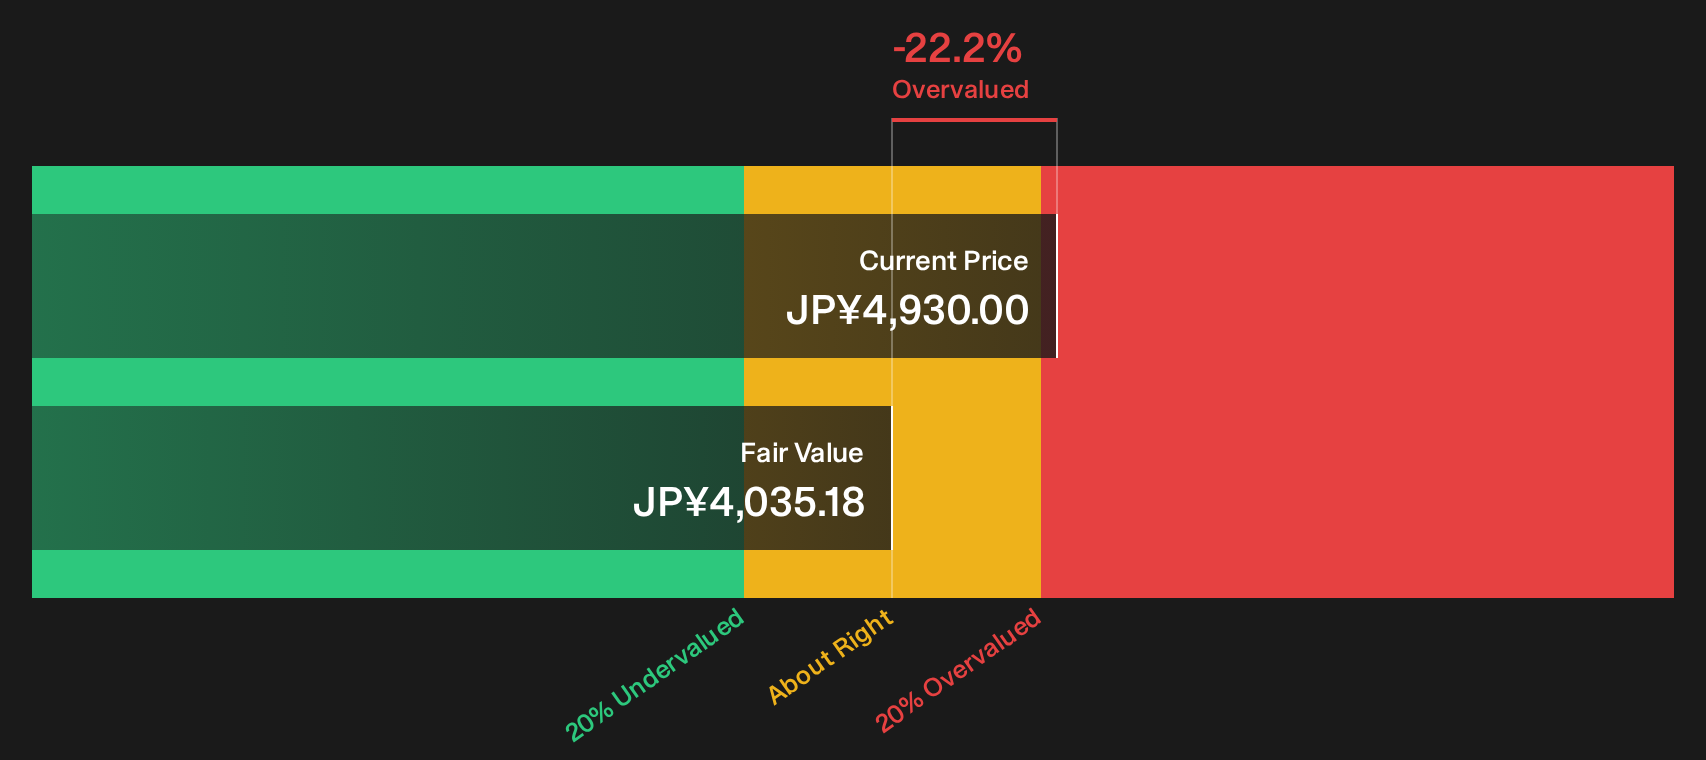
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitsui for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Mitsui’s value story are clear, so move quickly, review the underlying data, and weigh both sides of the argument. To see the full context around both the upside and the risks, start with 2 key rewards and 2 important warning signs.
Hunting For More Ideas Beyond Mitsui?
If Mitsui’s story has sharpened your thinking, do not stop here. Use fresh screeners now to spot other opportunities before the crowd catches up.
- Target potential mispricing across the market by running a focused search through 18 high quality undervalued stocks.
- Strengthen your income playbook by scanning companies in the 20 dividend fortresses that match your payout and stability preferences.
- Dial down portfolio stress by concentrating on the 21 resilient stocks with low risk scores that score well on resilience and financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com