


Learn Why The Bull Case For eBay (EBAY) Could Change Following Seller Ad Tools Rollout
- eBay has expanded its Promoted Stores Custom ads to all eligible sellers with an active Store subscription, letting them feature up to 1,000 listings and direct shoppers to tailored landing pages such as sales events, curated collections and eBay Live streams.
- The wider rollout gives eBay merchants more control over merchandising and funnel design, which can influence advertising spend patterns, the appeal of livestream shopping and how effectively influencer storefronts convert traffic into transactions on the platform.
- Next, the focus turns to what this broader Promoted Stores Custom access could mean for eBay’s investment narrative and long term platform economics.
What Is eBay's Investment Narrative?
To own eBay, you need to believe this marketplace can keep turning its 120 million style top line into high quality earnings while staying asset light and disciplined on capital. The expanded Promoted Stores Custom product fits that story neatly. It leans into higher margin ad tools rather than heavy logistics spend, and if sellers adopt it, near term catalysts skew toward better monetisation of existing traffic rather than expensive user acquisition.
The whistleblower lawsuit points in the opposite direction. It highlights execution and governance questions around seller treatment and deal metrics at exactly the time eBay is trying to convince merchants and influencers to build on its platform. Forecast earnings growth of 9.8% a year and a P/E of 21.5x only work if operational trust holds. Debt levels and management pay already give you enough to think about.
Even so, there is a specific pressure point in eBay's story that rarely shows up in headline numbers...
There's only one way to know the right time to buy, sell or hold eBay. Head to Simply Wall St's company report for the latest analysis of eBay's Fair Value.
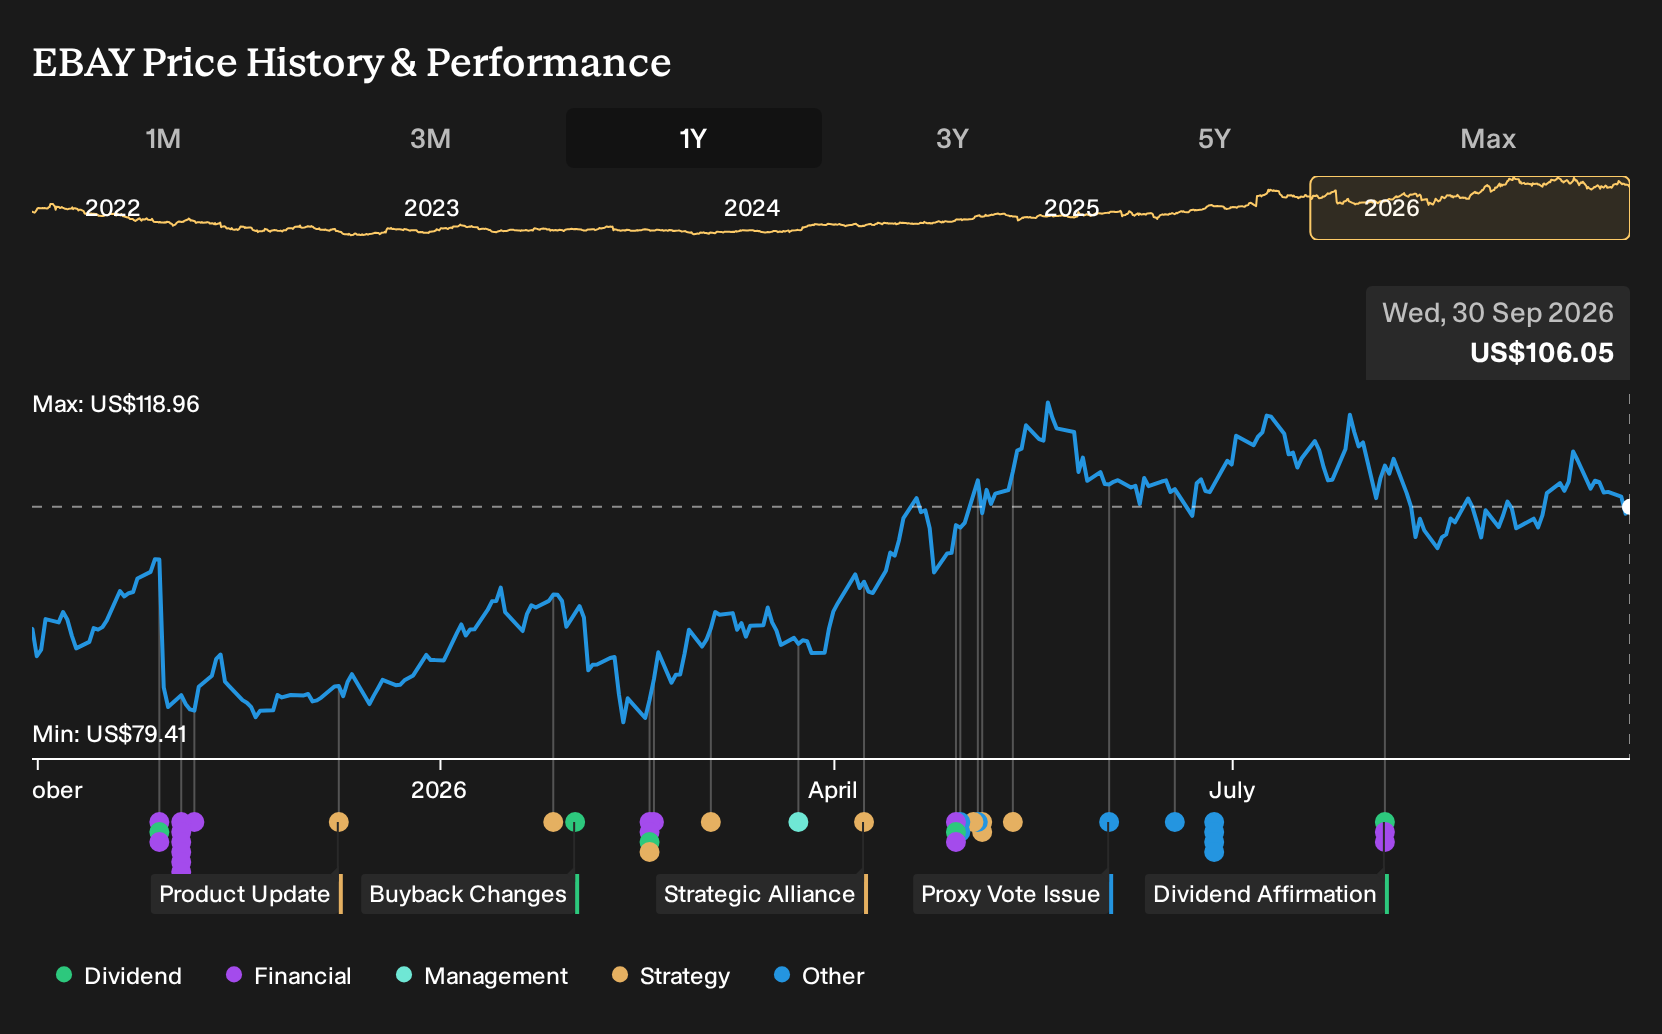
Exploring Other Perspectives
Some of the lowest ranked analysts see the real risk in eBay’s story as margin pressure rather than user growth. They were pencilling in only 5.3% annual revenue growth and profit margins easing from 18.3% to 16.5%, with earnings of about US$2.3b by 2029. Use that more cautious script as a counterweight and test how this ad rollout might shift it.
Explore 4 other eBay fair value estimates, including one that suggests it could be worth just $104.94.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your eBay research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for eBay. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate eBay's overall financial health at a glance.
Looking For More Investment Ideas Beyond eBay?
If the eBay story has you thinking about where seller tools, balance sheets and cash flows intersect, it can help to scan a wider field of listed businesses using the Simply Wall St Screener before making any decisions.
- If you want to focus on stability first, start with companies that score well on resilience and risk by scanning our 31 resilient stocks with low risk scores.
- For investors who care most about financial strength, filter for businesses with robust finances and clean balance sheets using this curated list of solid balance sheet and fundamentals (25 results).
- If you are hunting for mispriced opportunities with strong fundamentals, cast a wider net across our 32 high quality undervalued stocks to see which stocks currently screen as potentially attractively priced.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com