


How Investors May Respond To Marvell Technology (MRVL) Ahead Of Investor Day
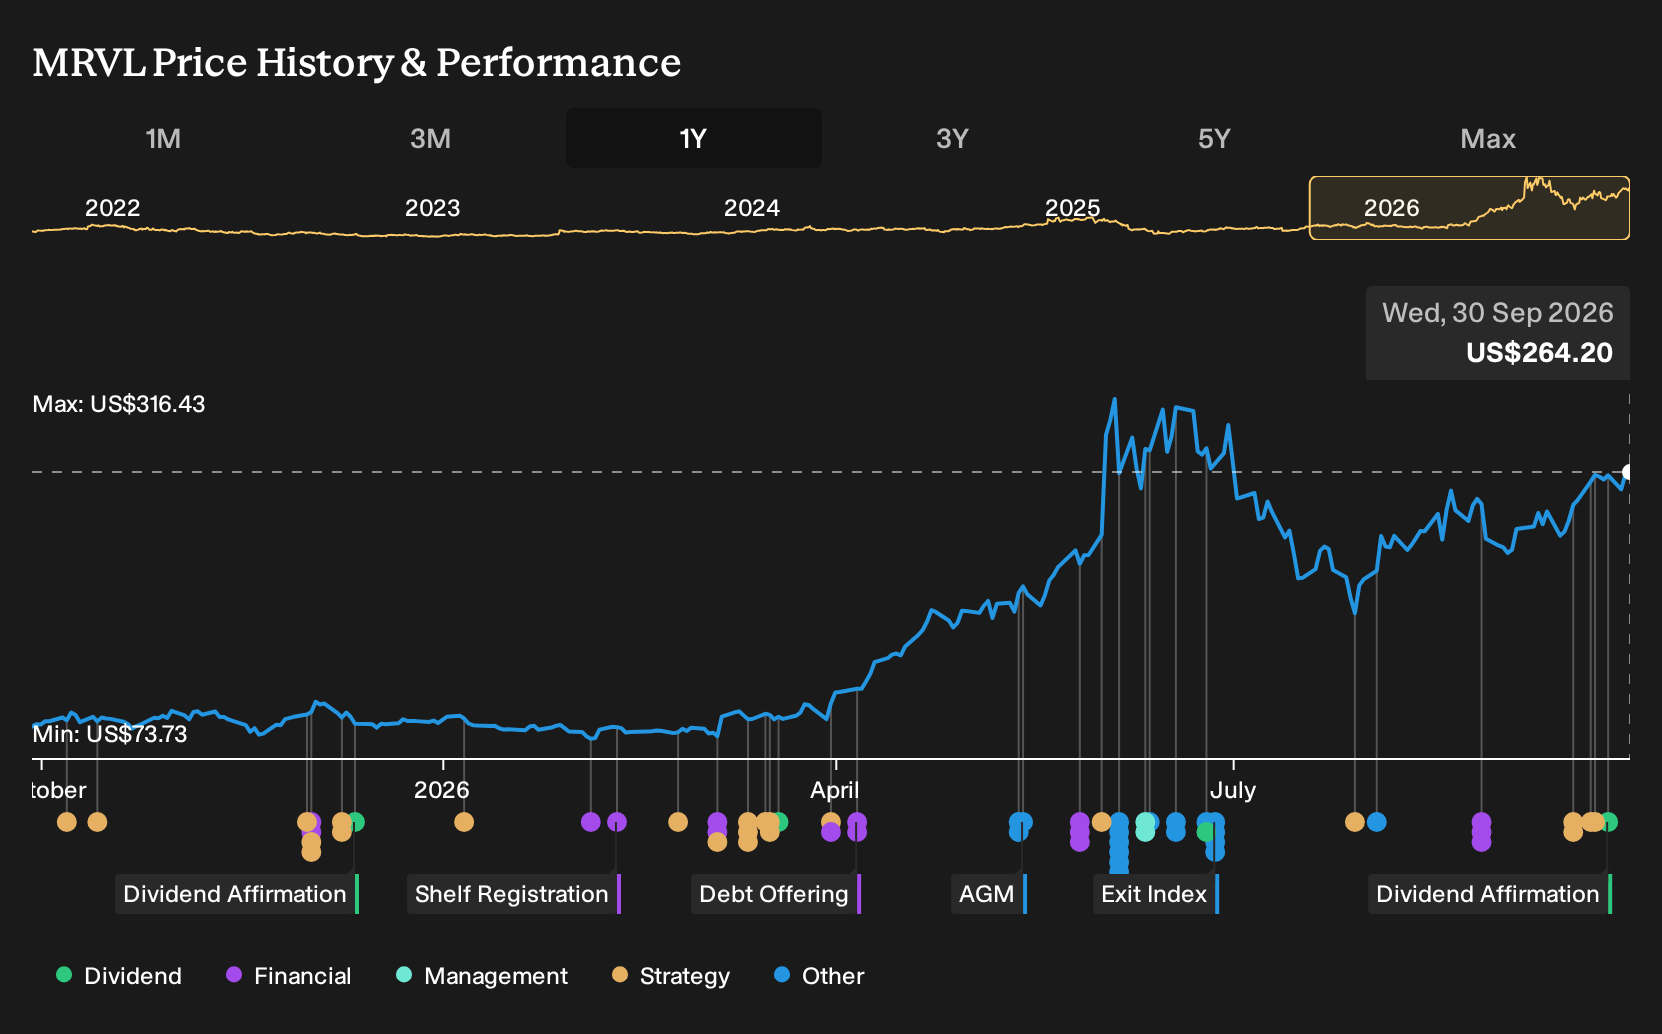
- Marvell Technology recently affirmed a quarterly dividend of US$0.06 per share and expanded collaborations in advanced IC substrates, silicon germanium capacity and cloud-based payment security platforms, while also showcasing 2 nm optical interconnect technologies for AI data center connectivity.
- These moves highlight Marvell Technology’s push to secure long-term capacity and packaging for AI networking chips, as well as integrate its LiquidSecurity hardware into Azure Payment HSM v2 for financial clients that need cloud-scale, regulated payment processing.
- We will now look at how Marvell Technology’s 2 nm AI interconnect initiatives could influence the broader investment narrative around data centers.
Marvell Technology Investment Narrative Recap
To own Marvell Technology, you need to be comfortable with a business that leans heavily on data center silicon and optical connectivity, with growth tied closely to hyperscale AI deployments. The 2 nm optical announcements and expanded capacity deals aim to support that demand, while the US$0.06 dividend affirmation mainly signals balance sheet confidence rather than a new earnings driver.
The near term swing factor remains how quickly large cloud customers ramp custom and optics orders relative to Marvell’s tight supply chain and high R&D spend. Execution risk sits in the same place. Any pause in AI capex or delay in custom projects could hit a business already concentrated in this one end market.
The expanded collaboration with AT&S to secure advanced IC substrate capacity looks especially relevant here. It directly addresses one of Marvell Technology’s key operational pressure points, which is making sure packaging and substrate supply can keep up with demand for higher speed AI networking chips without creating bottlenecks or added costs.
More committed substrate capacity can support the 2 nm optical roadmap and co packaged optics ambitions, which are central to the data center catalyst investors are focused on. It does not remove risk that large customers adjust AI spending or shift designs in house, but it can reduce execution friction if demand materializes and improve Marvell’s ability to deliver on multi year design wins.
Marvell Technology's narrative projects US$30.3b revenue and US$9.6b earnings by 2029. This implies 47.4% yearly revenue growth and an earnings increase of about US$7.0b from US$2.6b today.
Learn how Marvell Technology's fair value suggests a 9% potential increase from its current price before other investors respond to that opportunity.
Exploring Other Perspectives
Ten fair value estimates from the Simply Wall St Community span roughly US$140 to about US$377 per share, which shows how far apart retail views on Marvell Technology can be. You also have major concentration in data center revenue and tight supply chains. That combination can amplify both upside optimism and downside execution risk, so explore several viewpoints before you decide where you sit.
Explore 9 other Marvell Technology fair value estimates, including one that suggests as much as 47% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider your own analysis.
- A great starting point for your Marvell Technology research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Marvell Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marvell Technology's overall financial health at a glance.
Looking For More Ideas Beyond Marvell Technology?
If you want to pressure test your view on Marvell Technology, compare it with other companies that fit different risk and return profiles using the Simply Wall St Screener.
- If you prefer to keep risk contained, scan a 31 resilient stocks with low risk scores that may suit a steadier approach to portfolio building.
- For investors hunting for quality at a sensible entry point, filter for a 33 high quality undervalued stocks that combine solid fundamentals with pricing that may still be reasonable.
- Those who want to focus on financial strength can start with a list of solid balance sheet and fundamentals (25 results) and compare how those companies stack up against Marvell Technology on resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com