


Did New Singapore Chip Capacity Just Shift TOPPAN Holdings' (TSE:7911) Investment Narrative?
- TOPPAN Holdings and its subsidiary Irplast recently started a new high performance BOPP film line in Italy and opened an FC-BGA substrate plant in Singapore through Advanced Substrate Technologies to support demand for sustainable packaging and advanced semiconductor components.
- The twin build out in European packaging films and Singapore semiconductor substrates pushes TOPPAN Holdings further away from legacy print and toward higher spec, capital intensive manufacturing, where scale and technical capability matter most.
- We will now look at how TOPPAN Holdings' new Singapore FC-BGA capacity could reshape the broader investment narrative for the group.
Scan beyond TOPPAN Holdings and see how other manufacturers exposed to AI hardware and advanced packaging stack up with the curated 90 AI infrastructure stocks.
TOPPAN Holdings Investment Narrative Recap
To own TOPPAN Holdings, you need to buy into a slow grind away from shrinking legacy print and toward packaging, digital security, and semiconductor related products. The Singapore FC BGA build and Irplast BOPP expansion both lean into that shift. The key near term swing factor remains execution on this transformation while keeping earnings quality clear of one off noise.
The biggest immediate risk is that heavy capital spending and M&A related costs run ahead of cash generation, especially with net profit margins at 4.1% and recent earnings volatility. If the new capacity in packaging and electronics ramps more slowly than expected, balance sheet pressure and sentiment around returns on this spend could worsen.
The Singapore FC BGA project looks most relevant for investors watching catalysts. It directly ties into the existing push in advanced semiconductor packaging and photomasks. Analysts already build into their expectations that earnings will grow 7.05% a year. This new site outside Japan gives TOPPAN Holdings a larger operational footprint in AI and networking hardware supply chains.
Execution risk is real. The facility is planned to lift FC BGA capacity to at least 2.5 times the 2022 level by the end of fiscal 2027, which means a lot of capital, process ramp up, and customer qualification work still ahead. If that scaling progresses on time and within budget, it could help offset weakness in traditional print and support the longer term portfolio tilt investors are watching.
TOPPAN Holdings' analyst narrative points to revenues of ¥2,056.7b and earnings of ¥94.7b by 2029, based on 3.3% yearly revenue growth and an earnings increase of about ¥17.6b from ¥77.1b today.
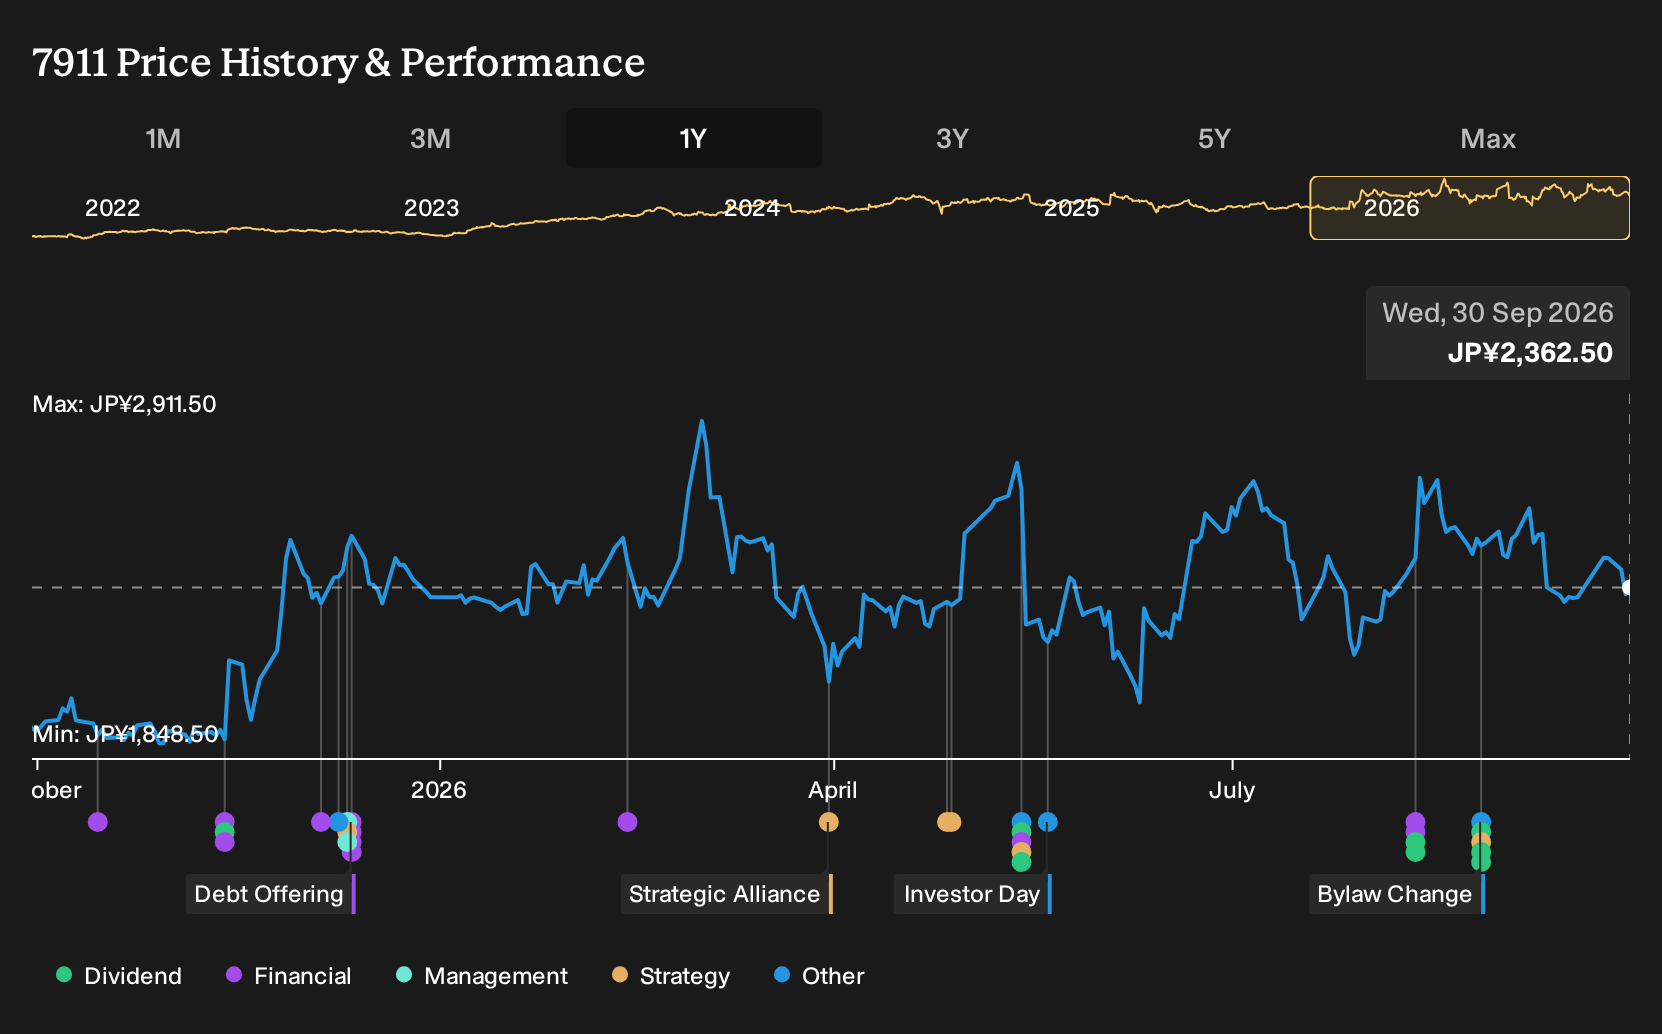
Uncover how TOPPAN Holdings' fair value indicates a 34% potential upside to its current price, a gap that could narrow quickly as sentiment shifts.
Exploring Other Perspectives
Across the Simply Wall St Community, 2 private investors peg TOPPAN Holdings’ fair value between ¥3,175 and about ¥4,468 a share, a wide band that shows how far views can stretch. This sits alongside heavy spending on packaging and FC BGA capacity. Your own take on execution risk and capital discipline really matters here.
Explore another TOPPAN Holdings fair value estimate, including one that suggests it could be worth just ¥3175!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your TOPPAN Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TOPPAN Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TOPPAN Holdings' overall financial health at a glance.
Looking for more investment ideas beyond TOPPAN Holdings?
If TOPPAN Holdings has you thinking about where to deploy your next yen, broaden the search and compare it with other businesses that fit the kind of profile you want in a portfolio.
- For investors hunting for early stage opportunities with stronger financial footing than the typical micro cap, take a look at 1 elite penny stocks with strong financials.
- If the goal is to pair quality with a sensible entry price, consider casting a wider net across the market using the 18 high quality undervalued stocks.
- When capital preservation and resilience matter most, you may want to start with a 21 resilient stocks with low risk scores that screens for companies with steadier risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com