


Is Laundry Platform Launch Altering The Investment Case For Electrolux Professional (OM:EPRO B)?
- Electrolux Professional has launched Generation 7000, a multi year refresh of its professional laundry portfolio that will roll out washers, dryers and connected solutions between 2026 and 2029, with the first Compact Power range targeting high performance needs in tight spaces.
- The Generation 7000 platform is built around lower resource use, connected monitoring and easier servicing. These features could reshape Electrolux Professional’s cost profile, aftermarket potential and reach into space constrained customers and retail or wholesale channels.
- We will now examine how Electrolux Professional’s new Generation 7000 laundry platform could shift its investment narrative toward connectivity and services.
Scan Electrolux Professional's shift toward smarter, resource efficient laundry and compare it with curated peers by reviewing 93 robotics and automation stocks to see how equipment, automation and services come together in real-world operations.
Electrolux Professional Investment Narrative Recap
To own Electrolux Professional, you need to believe that heavier R&D and higher costs today can translate into stronger, more connected product platforms and better quality earnings over time. Generation 7000 sits right in the middle of that bet. The key near term swing factor is still how efficiently the group converts this investment into commercially relevant laundry launches.
The biggest operational risk remains margin pressure from rising costs, currency effects and choppy customer ordering patterns. The Generation 7000 rollout does not remove those issues. It could help if customers adopt the connected, resource efficient equipment at scale, but execution timing, especially in Europe where demand has been more muted, is still critical.
The Generation 7000 announcement ties directly into the earlier catalyst around higher R&D spend, now about 5% of sales. Investors have been told to expect a pipeline of energy efficient, connected products that can support better mix and service revenue. This laundry platform is a concrete expression of that ambition rather than a fresh theme.
For investors, the question becomes how quickly Electrolux Professional can monetize the Compact Power range and subsequent Generation 7000 releases across regions like the Americas and APAC, where demand has been healthier. Progress on connected services, aftermarket uptake and pricing on these units will feed back into the core thesis on margin quality and earnings growth.
Electrolux Professional Consensus Expectations Through 2029
Electrolux Professional's narrative projects SEK 13.5 billion revenue and SEK 1.4 billion earnings by 2029. This is based on analyst assumptions of 4.9% yearly revenue growth and an earnings increase of SEK 692 million from SEK 708.0 million today.
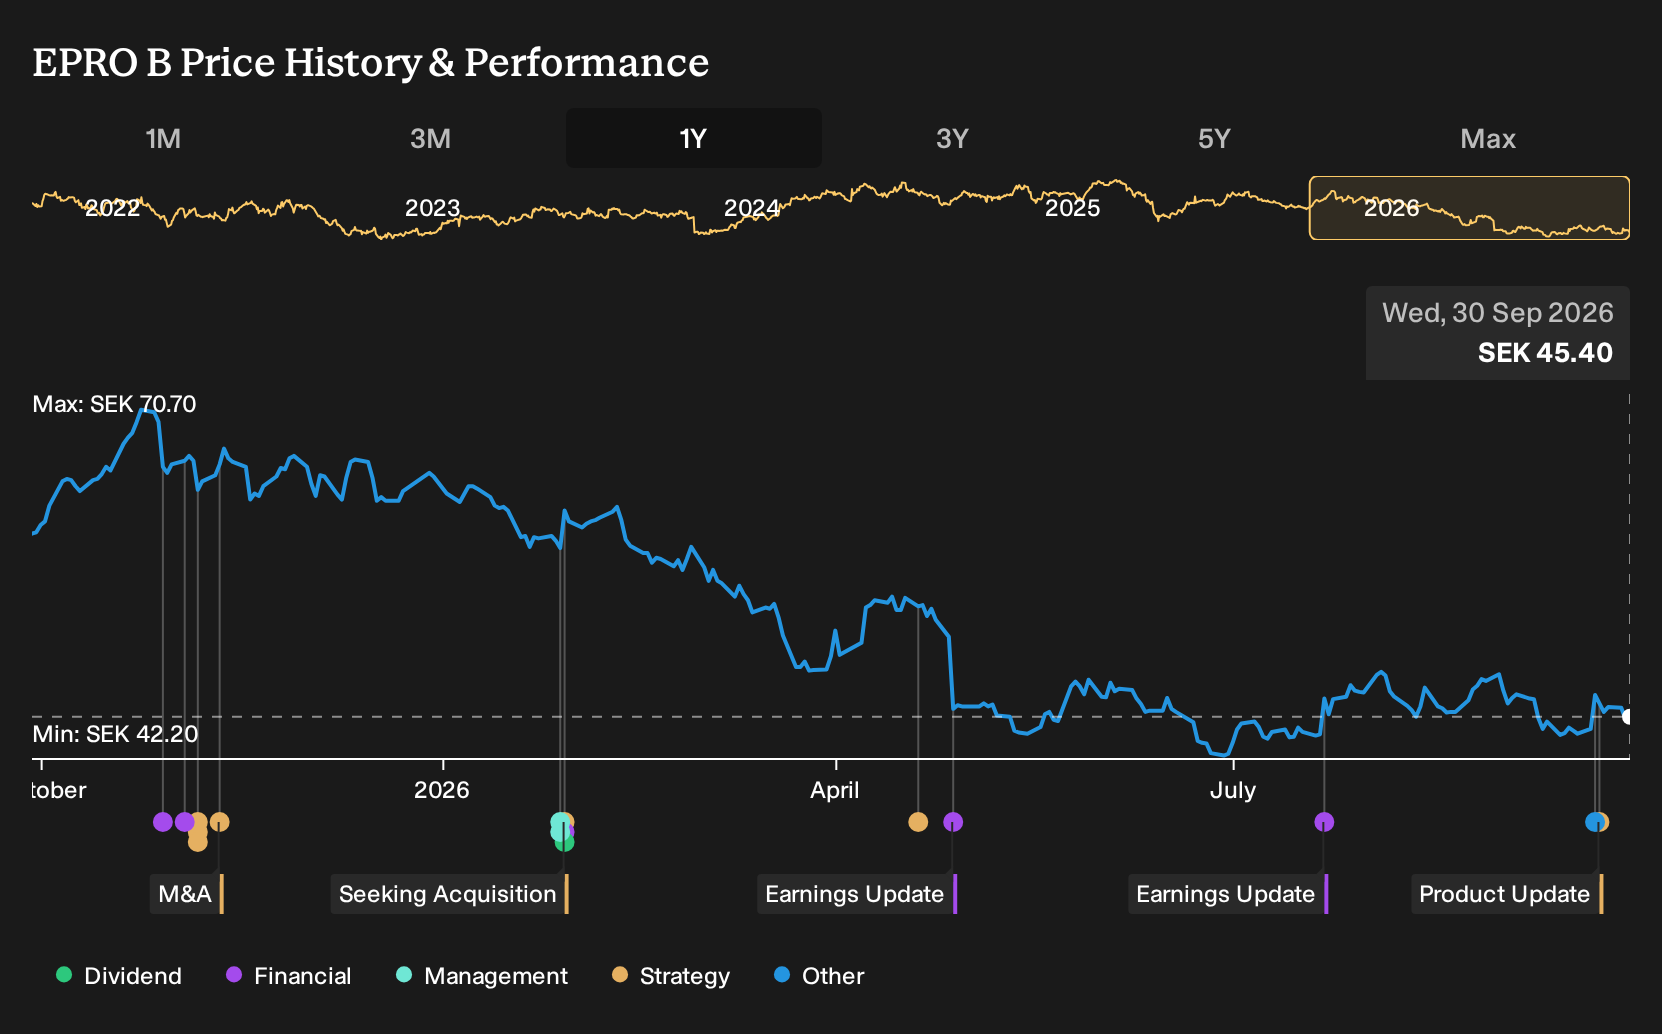
Uncover why Electrolux Professional's fair value indicates a 61% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly SEK 44 to about SEK 115, with one outlier implying far higher optimism on Electrolux Professional than the rest. These private investors clearly disagree. When you factor in currency pressure, elevated R&D spend and the Generation 7000 launch, you get very different paths for future performance.
Explore 3 other Electrolux Professional fair value estimates, including one that suggests it could be worth just SEK44.00.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Electrolux Professional research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Electrolux Professional. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Electrolux Professional's overall financial health at a glance.
Looking for more Electrolux Professional style investment ideas?
If Electrolux Professional has sharpened your focus on quality, pricing power and balance sheet strength, it can be useful to scan a wider pool of companies that share some of those traits but sit in very different corners of the market.
- For investors who want potential upside without ignoring fundamentals, review a curated set of value focused opportunities through 191 high quality undervalued stocks.
- If dependable balance sheets matter to your process, you can filter for businesses with stronger financial footing using the list of solid balance sheet and fundamentals (205 results).
- Those who care about steadier return profiles can narrow the field to companies with fewer risk flags by using the 224 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com