


DCM Holdings (TSE:3050) Stock Sees Revenue Growth Clash With Profit Compression
DCM Holdings stock went into this earnings release on the back foot, with the share price down over the past week and month even as the 90 day return stayed slightly positive. That set up a classic sentiment clash when the new numbers hit.
The headline this quarter is profit pressure. Basic earnings per share of ¥36.89 in Q2 2027 sat well below Q1, while net income of ¥5,040m came against a trailing net profit margin of about 3% that had already been under strain. For a specialty retailer, that kind of squeeze on earnings power is what really tests conviction in the recent share price weakness.
Concerned that DCM Holdings is feeling the squeeze on earnings but still want exposure to retailers with sturdier profit power and cleaner balance sheets? Benchmark this result against our list of solid balance sheet and fundamentals stocks (23 results).
Q2 2027 Earnings Summary
- Revenue, Q2 2027 vs. Q2 2026: ¥152,405m vs. ¥142,002m (up about 7.3%)
- Net Income, Q2 2027 vs. Q2 2026: ¥5,040m vs. ¥6,255m (down about 19.4%)
- Basic EPS, Q2 2027 vs. Q2 2026: ¥36.89 vs. ¥46.68 (down about 20.9%)
- Trailing 12 Month Net Profit Margin, Q2 2027 vs. prior year: 3.0% vs. 3.3% (compressed by about 0.3 percentage points)
Prefer clean visual charts instead of a dense wall of earnings numbers and margin figures? See DCM Holdings' profit profile in context with a full visual breakdown in the company report for DCM Holdings.
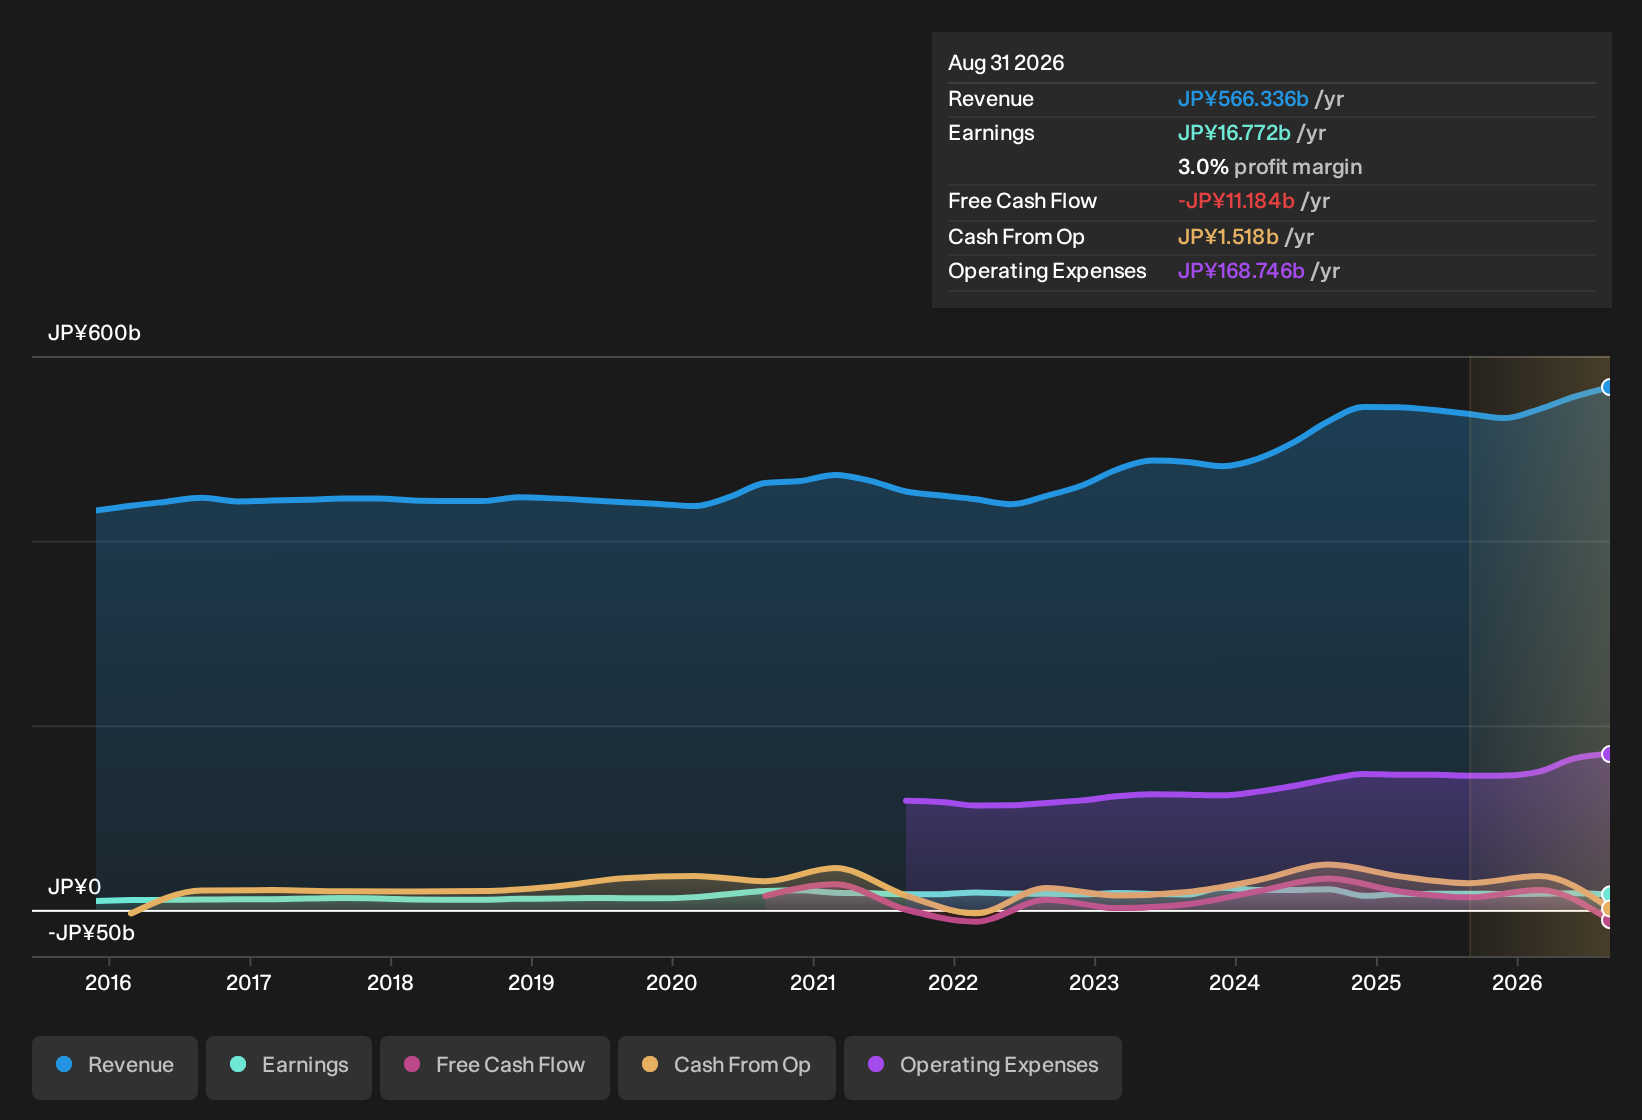
DCM bullish story meets mixed earnings reality
For investors who see DCM Holdings as a defensive retailer with steady demand, the top line helps that view. Revenue in Q2 2027 reached ¥152,405m compared with ¥142,002m a year earlier, which points to healthy customer traffic across everyday categories. That sits comfortably with the idea of a broad home improvement and daily goods platform that still pulls shoppers in, even while sentiment toward the stock has cooled over the past month.
Profit squeeze tests the defensive retail thesis
The bear case focuses on margin strain and these results give that concern real footing. Net income fell from ¥6,255m to ¥5,040m year on year, and basic EPS declined from ¥46.68 to ¥36.89. The trailing net profit margin eased from 3.3% to 3.0%. For a retailer often treated as a steady holding, that pressure on earnings power and profitability sits uncomfortably against the defensive narrative and helps explain why the share price has slipped over 7 and 30 days.
After profit margins compress and dividends put pressure on free cash flow, questions about debt coverage usually follow. Review our risk analysis for DCM Holdings which shows 2 important warning signs to see whether these pressures are early warnings or part of a deeper risk pattern.Take Control Of Your Next Move
Profit pressure and a softer share price often create the exact kind of setup you may want to track closely, so register for free with Simply Wall St and add DCM Holdings to your Watchlist to follow how the price moves against fair value and identify a potential entry that fits your plan. Once you own the shares, keep a clear view of what matters by using the Portfolio Command Center to filter noise and surface only the most important updates on earnings, dividends, and risks. Round out your process by tapping into crowd insight through the Community so you can see how other investors are interpreting the same data. By highlighting potential catalysts and pressure points early, Simply Wall St aims to help you act faster and stay prepared for market developments.
Seeking Alternatives Beyond DCM Holdings?
Fresh opportunities move fast and early momentum often fades once the crowd catches on. Scan these curated ideas while they are still under the radar for now and act now.
- Target steadier compounding potential by scanning a curated 21 resilient stocks with low risk scores that may help you avoid stocks dropping on fragile balance sheets and stretched valuations.
- Chase upside in real economic assets by reviewing hand picked 17 top copper producer stocks that could benefit if infrastructure demand gains momentum before the story goes fully mainstream.
- Ride structural demand for electricity by checking a tight list of 39 power grid technology and infrastructure stocks that might be building quiet breakouts before earnings revisions start flying.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com