


Turning Point Brands (TPB) Reaffirms Guidance Following CEO Change, Is The Stock Trading At A Discount?
CEO transition and reaffirmed outlook at Turning Point Brands
Turning Point Brands (TPB) announced that CEO Graham Purdy will step down for personal reasons. Executive Chairman David E. Glazek will take over as chief executive, and the company reaffirmed its 2026 sales guidance.
For investors tracking Turning Point Brands, the leadership change and reaffirmed 2026 guidance come after a sharp reset in sentiment. The share price is down about 28% over the past month and the year-to-date share price return is down 45.5%. Even so, the three-year total shareholder return of 172.22% still points to a very strong longer-term outcome compared with the 39% decline in total shareholder return over the past year. This suggests that recent weakness has followed a strong multi-year run rather than a steadily deteriorating story.
Scan how other consumer-focused stocks with stronger price momentum or different leadership stories stack up against Turning Point Brands in our curated list of 32 high quality undervalued stocks.
So the question now is whether Turning Point Brands’ steep slide mostly reflects concern about the underlying business after the CEO change, or a sharp reset in sentiment that has pushed the valuation too far.
Most Popular Narrative: 49% Undervalued
On the most followed narrative, Turning Point Brands screens as materially below its implied fair value of $118.50 compared with the last close at $60.08. That gap is tied closely to how the Modern Oral pouch story plays out.
Strong growth in the Modern Oral nicotine pouch segment, with sales growing nearly 8x year-over-year and now accounting for 26% of total revenue, positions TPB to capture significant market share in a category projected to reach $10 billion by decade's end. This will drive long-term revenue and margin expansion as the modern oral segment scales and premiumizes.
See why 7 investors see Turning Point Brands as 49% undervalued.
Result: Fair Value of $118.50 (UNDERVALUED)
Still, the Turning Point Brands story depends heavily on Modern Oral staying on track, while higher freight and marketing costs do not squeeze margins more than expected.
Find out about the key risks to this Turning Point Brands narrative.
Another View on Turning Point Brands' Value
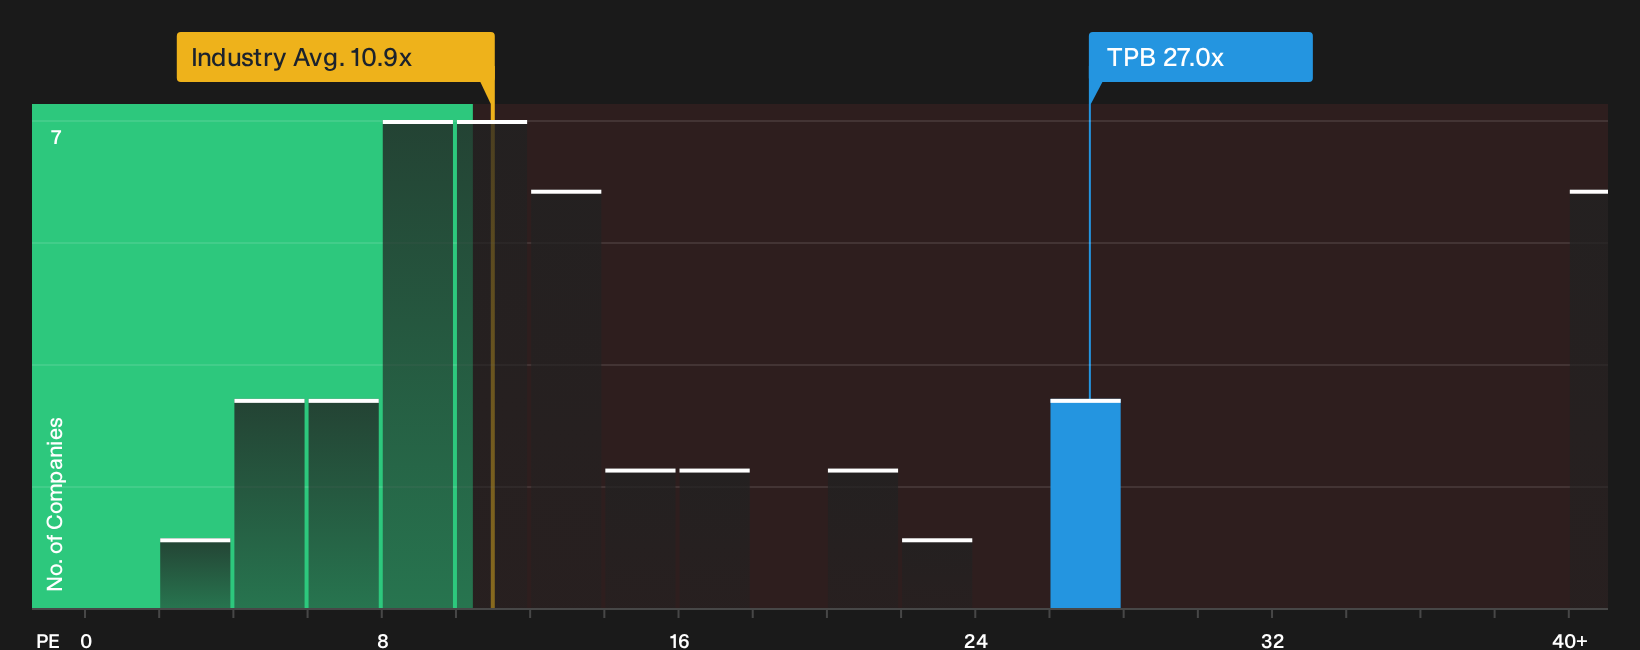
There is a different read on Turning Point Brands when looking at simple earnings multiples. The shares trade on a P/E of 27x, compared with a fair ratio of 36.3x from regression work and a peer average of 33.8x, while the wider Global Tobacco group sits much lower at 10.7x.
That mix means the stock looks cheaper than similar companies and the fair ratio, yet expensive versus the broader industry. This points to real valuation risk if sentiment swings back toward sector norms, or potential upside if it continues to be treated more like its higher rated peer group.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Turning Point Brands for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Turning Point Brands is clearly split, with concerns on one side and optimism on the other. Move quickly, test the data yourself, and then weigh the balance of 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Turning Point Brands?
If Turning Point Brands has your attention, do not stop there. Use the Simply Wall St Screener to spot fresh opportunities before everyone else piles in.
- Target dependable cash generators and pressure test your income strategy with 6 dividend fortresses, built to highlight companies supporting stronger yield profiles.
- Zero in on balance sheet strength and stress test your downside risk using the list of solid balance sheet and fundamentals (25 results), so weaker businesses do not catch you off guard.
- Hunt for overlooked potential by scanning the 17 high quality undiscovered gems, where smaller, less-followed stocks still fly under the radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com