


Custom Truck One Source (CTOS) Posted Record Q2 Results, Is It Still Below Fair Value?
Custom Truck One Source (CTOS) moved into focus after reporting record Q2 revenue of $563 million and Adjusted EBITDA of $117 million, along with higher full-year 2026 sales and profit guidance.
Despite the strong Q2 release, Custom Truck One Source’s recent share price action has cooled, with a 1-day share price return that declined 0.97%, a 7-day share price return down 4.26% and a 90-day share price return down 16.49%. The pullback sits against a much stronger backdrop, with a year-to-date share price return of 58.97% and a 1-year total shareholder return of 43.61%, which suggests momentum has been positive over the longer stretch even as shorter term sentiment has eased around the current US$9.22 level.
Scan for other equipment and infrastructure plays showing similar momentum to Custom Truck One Source by running the handpicked 39 power grid technology and infrastructure stocks.
Custom Truck One Source looks like a solid operator on paper, yet the recent pullback after strong results raises a sharper question. Is the quality of this business already fully reflected in today’s share price, or not?
Most Popular Narrative: 31% Undervalued
Custom Truck One Source is currently trading at $9.22, while the most followed narrative framework pegs a fair value closer to $13.33. This sets up a clear gap that analysts are trying to explain through rental growth, margin assumptions, and balance sheet repair.
Continued focus on inventory optimization and leverage reduction (with a stated net leverage target of below 3x by end of FY 2026), if achieved through strong free cash flow, is likely to decrease interest expense and boost net income, creating potential for valuation rerating.
See why 3 investors see Custom Truck One Source as 31% undervalued.
Result: Fair Value of $13.33 (UNDERVALUED)
Still, the bullish Custom Truck One Source story can fray if elevated net leverage near 4.66x remains high or if TES backlog pressure signals softer demand ahead.
Find out about the key risks to this Custom Truck One Source narrative.
Another View on Custom Truck One Source Valuation
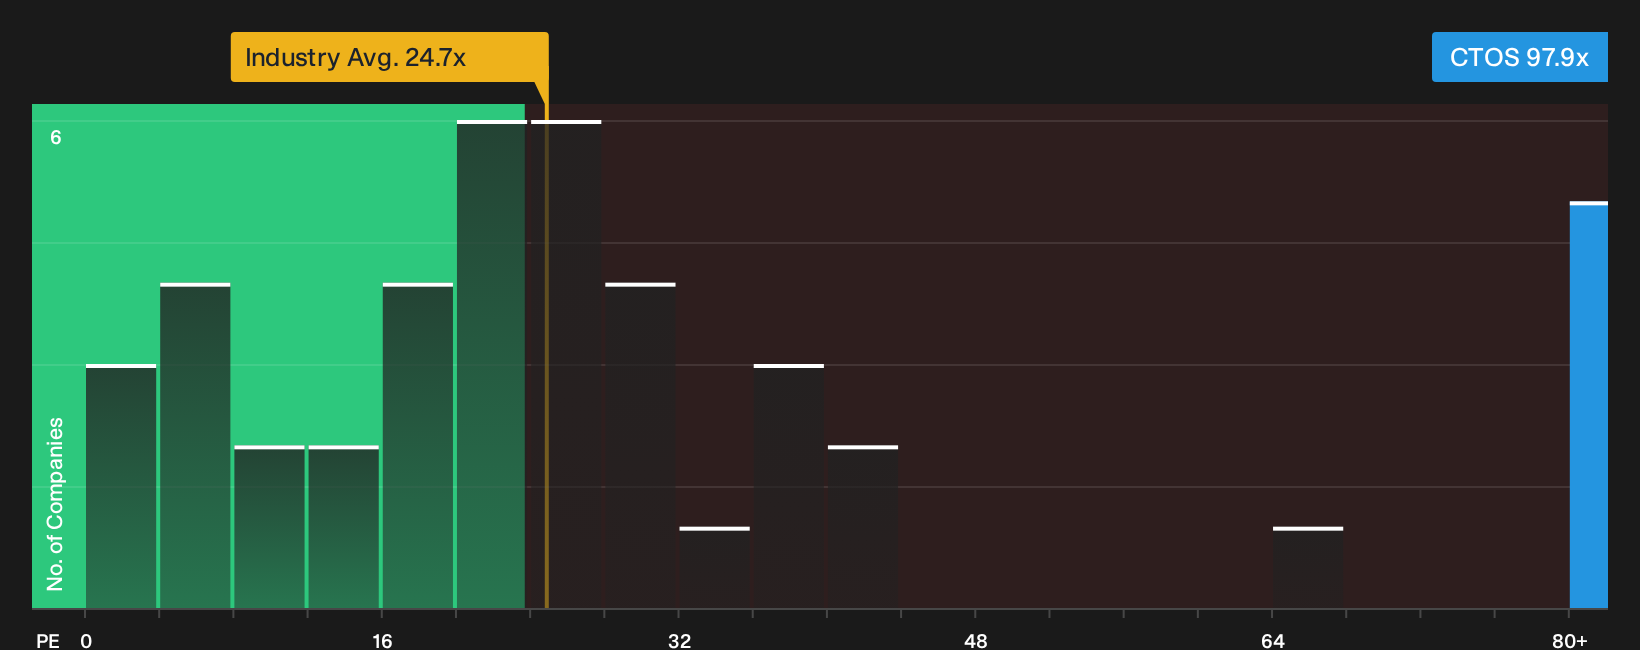
On the flip side of that fair value narrative, Custom Truck One Source trades on a P/E of 97.9x compared with 24.7x for the US Trade Distributors industry, peers at 23.2x, and a fair ratio of 40.4x. That is a wide premium. Is the market overpaying for the story or just front running it?
For a closer look at what this gap could mean in practice, including where the fair ratio sits relative to pricing today, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the tug of war between Custom Truck One Source bulls and bears feels sharp, that is by design, so use it as a prompt to move fast and check the underlying data yourself. To see how the upside case stacks up against the more cautious view, start with the 4 key rewards and 2 important warning signs.
Looking for more Custom Truck One Source style ideas?
If Custom Truck One Source has grabbed your attention, do not stop here. Use the Simply Wall St screener to surface other opportunities before the market does.
- Target steadier compounding potential by scanning a curated 32 resilient stocks with low risk scores list that focuses on resilience when conditions get choppy.
- Hunt for quality at sensible prices through a focused 31 high quality undervalued stocks set that filters for strong fundamentals without stretching on price.
- Spot businesses that the crowd has not fully noticed yet by running a tailored 17 high quality undiscovered gems lineup built around robust financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com