


IDT (IDT) Stock Jumps As Record Earnings Meet A Rich P E
The market cheered IDT long before anyone finished reading the earnings release. The stock jumped 8.6% to US$75.56, extending a three month run that already had the shares up about 30%. That kind of move usually implies a flawless quarter. The actual results tell a more complicated story.
Record fiscal 2026 earnings and a net profit margin of 6.7% helped, yet the headline tonight is valuation strain. IDT now trades around 21.7x earnings, well above global telecom peers near 2.6x and the broader industry at 15.6x. For investors, the gap between price and underlying cash generation is becoming more difficult to ignore.
Love the record earnings from IDT but uneasy about paying up at a 21.7x P/E multiple that sits well above telecom peers? Filter for companies that pair resilient profitability with more modest valuations using our 31 high quality undervalued stocks.
Q4 2026 Earnings Summary
- Q4 2026 Revenue: US$338.979m vs. Q4 2025 US$316.594m (up about 7%)
- Q4 2026 Net Income (Excl. Extra Items): US$21.71m vs. Q4 2025 US$16.885m (up about 29%)
- Q4 2026 Basic EPS: US$0.87 vs. Q4 2025 US$0.67 (up about 30%)
- FY 2026 Net Profit Margin: 6.7% vs. FY 2025 6.2% (modest improvement in profitability)
If you prefer clear charts to a dense collection of earnings tables and financial ratios for IDT, explore the complete visual overview of the business, from valuation through to recent share price behavior, in our company report for IDT.
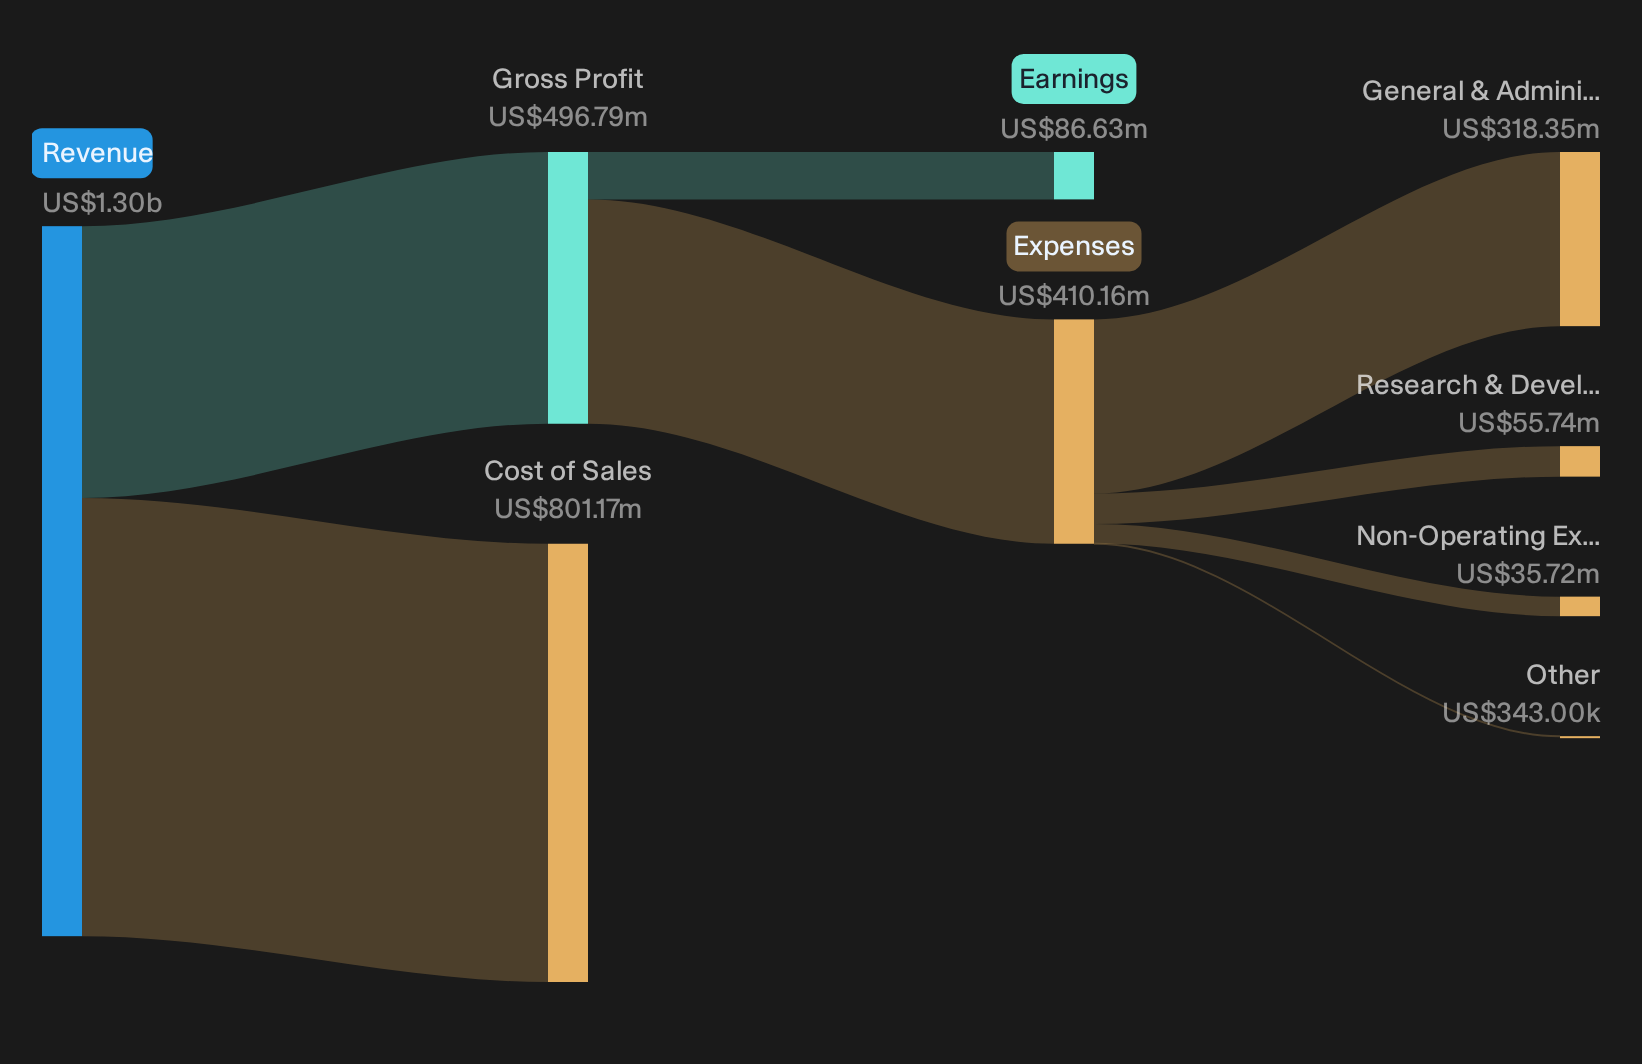
IDT bull story leans on mix shift proof
Bulls argue IDT is turning into a higher margin fintech and software platform, with NRS, BOSS Money and net2phone doing the heavy lifting. The latest year backs up that claim on operations. Those three units now generate about 53% of adjusted EBITDA while only a third of revenue, which shows the mix is tilting toward richer economics. NRS grew Q4 revenue 31% with advertising and data up 49% and EBITDA rising faster than sales, helped by very high gross margins around 92% for the year. Fintech revenue rose 14% with Q4 gross margin expanding about 650 bps to 66% and EBITDA up 41%. net2phone pushed subscription revenue up 10% and lifted adjusted EBITDA 33% with roughly 17% margin. Record consolidated EBITDA of US$154.6m, up 17%, ties the bullish narrative to actual profit delivery.
Bear case tests disclosure gaps and capital choices
Skeptics worry IDT is stretching disclosure, softening capital returns and leaning on stories that may slip. Some of that caution holds. NRS retired a familiar terminal level KPI in favor of retailer locations and gross profit per location, which makes near term tracking of monetization harder even as management talks up quality over quantity. On capital allocation, buybacks slowed to 422,000 shares for US$21m in FY26 despite a debt free balance sheet with US$272m of cash and liquid investments, which raises fair questions about how aggressively surplus funds will be returned. There is also radio silence on previously discussed moves like a net2phone spin off and NRS’s Colombia rollout. At the same time, bears who predicted erosion in the legacy communications cash engine are not getting that validation, since that segment kept EBITDA slightly higher year on year.
After management slowed repurchases and left plans for net2phone and NRS in limbo, it is fair to ask what other pressure points might be sitting off your radar. Review the risk analysis for IDT which shows 1 important warning signTake Control Of Your Next Move
If the mix of record earnings and a stretched P/E on IDT has your attention, register for free with Simply Wall St and add it to a Watchlist to track share price against fair value and wait for a setup that fits your playbook. Once you decide to build or trim a position, use the Portfolio Command Center to cut through noise and focus on the updates that actually affect your thesis. For a broader lens on sentiment and fresh angles you might have missed, tap into thousands of perspectives through the Community. Spot hidden catalysts and potential risks earlier so you can act with more confidence and stay a step ahead of the market.
Seeking Alternatives Before The Crowd Moves
Fresh ideas move first. When the next breakout gathers momentum, late money often gets caught chasing stocks already flying or dropping. Scan under the radar for now and act now.
- Spot resilient cash generators that pair strong balance sheets with pricing power by reviewing the curated list of solid balance sheet and fundamentals stocks (25 results) before others start bidding them up.
- Track where real income strength meets durability by scanning the hand picked 6 dividend fortresses while yields still reflect mispriced risk and not crowded demand.
- Ride the build out of tomorrow’s core infrastructure by surveying carefully filtered 39 power grid technology and infrastructure stocks while these stories are still forming, not fully priced.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com