


Is Adaptive Biotechnologies (ADPT) Fully Valued After The NCCN Guideline Update?
Clinical guideline update puts Adaptive Biotechnologies in focus
Adaptive Biotechnologies (ADPT) is back on investors’ radar after new National Comprehensive Cancer Network multiple myeloma guidelines more clearly position minimal residual disease testing, including the company’s clonoSEQ assay, within standard care discussions.
Recent price action has been strong, with a 30-day share price return of 14.21% and a 90-day move of 28.61%. The year-to-date share price return of 80.83% and 1-year total shareholder return of 92.31% indicate that momentum in Adaptive Biotechnologies is building rather than fading.
Capitalize on the momentum around Adaptive Biotechnologies by reviewing hand-picked peers in precision medicine and cancer diagnostics with the 37 healthcare AI stocks.Adaptive Biotechnologies now trades slightly above the average analyst target, yet still screens at a sizeable intrinsic discount. After a near doubling in 12 months, is that gap caution or mispricing?
Most Popular Narrative: 9% Overvalued
Adaptive Biotechnologies last closed at $28.77, compared with a widely followed narrative fair value of $26.36. This frames the current rally as richer than that reference point while still anchored to clear fundamental drivers.
Expansion of clonoSEQ integration and higher reimbursement rates position the company for strong recurring revenue growth and improved gross margins. Ongoing development of AI-driven TCR-antigen prediction models and a robust immune medicine pipeline creates future optionality for high-margin pharma partnerships and new diagnostic indications, leveraging secular trends in data-driven healthcare and personalized therapeutics supporting sustained long-term earnings growth.
See why 8 investors see Adaptive Biotechnologies as 9% overvalued.
Result: Fair Value of $26.36 (OVERVALUED)
Still, the narrative wobbles if CMS reimbursement shifts meaningfully or if key partnerships like Genentech or NeoGenomics underdeliver and slow MRD adoption for Adaptive Biotechnologies.
Find out about the key risks to this Adaptive Biotechnologies narrative.
Another view on Adaptive Biotechnologies valuation
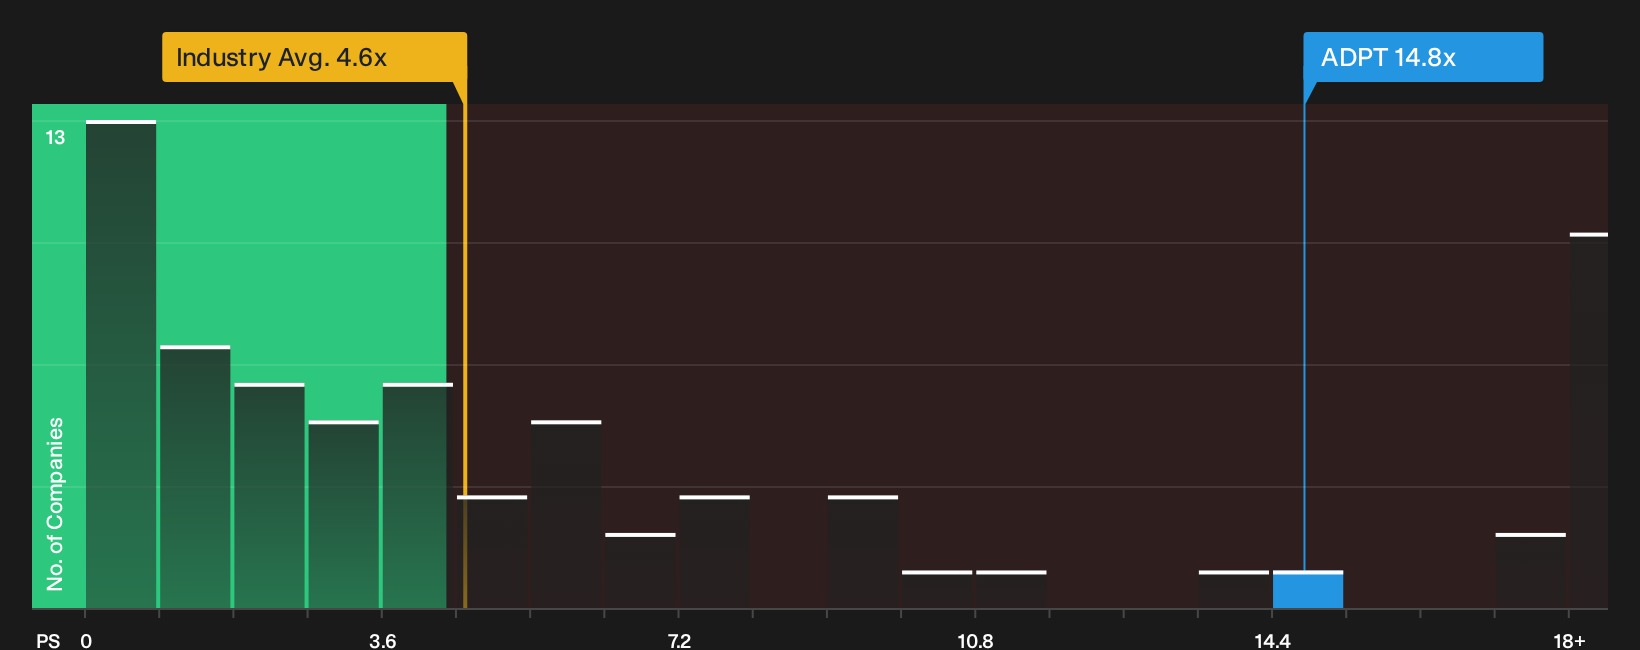
The first narrative pegs Adaptive Biotechnologies as around 9% overvalued. On a simple revenue multiple, the picture stretches even further. The stock trades on a P/S of 14.8x versus 4.5x for the US Life Sciences group and a fair ratio of 5.2x, which points to rich expectations baked into the price. Is that confidence well placed, or does it narrow the margin for error?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this piece points to excitement around Adaptive Biotechnologies, yet there are also clear pressure points that investors are watching closely. Act quickly, pull up the underlying figures, and weigh the 2 key rewards and 1 important warning sign against your own expectations.
Looking for more investment ideas beyond Adaptive Biotechnologies?
If Adaptive Biotechnologies has your attention, use that momentum to scan for other potential opportunities before they move out of reach.
- Hunt for quality at a discount by reviewing companies in the 32 high quality undervalued stocks.
- Prioritise resilience and sleep-at-night balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Spot early-stage potential with stronger fundamentals using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com