


OceanFirst Financial (OCFC) Dropped, What Is Drawing Attention Now?
OceanFirst Financial (OCFC) has drawn investor interest after recent share price pressure, with the stock down 11% over the past month and 14% over the past 3 months into the latest close.
The recent pressure sits against a mixed backdrop for OceanFirst Financial, with the 1-day and 7-day share price returns both declining, the year-to-date share price return also down, the 1-year total shareholder return close to flat, and the 3-year total shareholder return still positive.
Compare OceanFirst Financial's recent pullback with other regional banks by scanning our hand-picked list of solid balance sheet and fundamentals (25 results) that may be better positioned for the next rebound.
Bulls see OceanFirst Financial's recent share pullback as a chance to buy solid community banking earnings at a discount, while bears focus on the weak near term returns. Which case does the valuation actually support next?
Most Popular Narrative: 22% Undervalued
Based on the most followed narrative, OceanFirst Financial's fair value estimate of about $21.33 sits above the recent $16.72 close. This frames the latest pullback as a valuation gap rather than just weak momentum.
The substantial investments in C&I bankers and expansion into new commercial markets are driving robust growth in the commercial loan pipeline (record $791M), positioning OceanFirst for above-peer loan and net interest income growth as population migration and small business formation continue in its regional markets, likely boosting both revenue and net earnings. Early momentum from newly launched Premier Bank teams is bringing in significant new deposit relationships (~$115M from 670+ accounts in 8 weeks, with a target of $500M by year-end), providing low-cost and diversified funding as more people and businesses migrate to suburban and exurban regions, enabling margin improvement and supporting future balance sheet growth.
See why 7 investors see OceanFirst Financial as 22% undervalued.
Result: Fair Value of $21.33 (UNDERVALUED)
Still, that 3 year earnings plan relies heavily on new commercial hires delivering and on deposit costs not rising faster than OceanFirst Financial can reprice its loans.
Find out about the key risks to this OceanFirst Financial narrative.
Another View: What Multiples Say About OceanFirst Financial
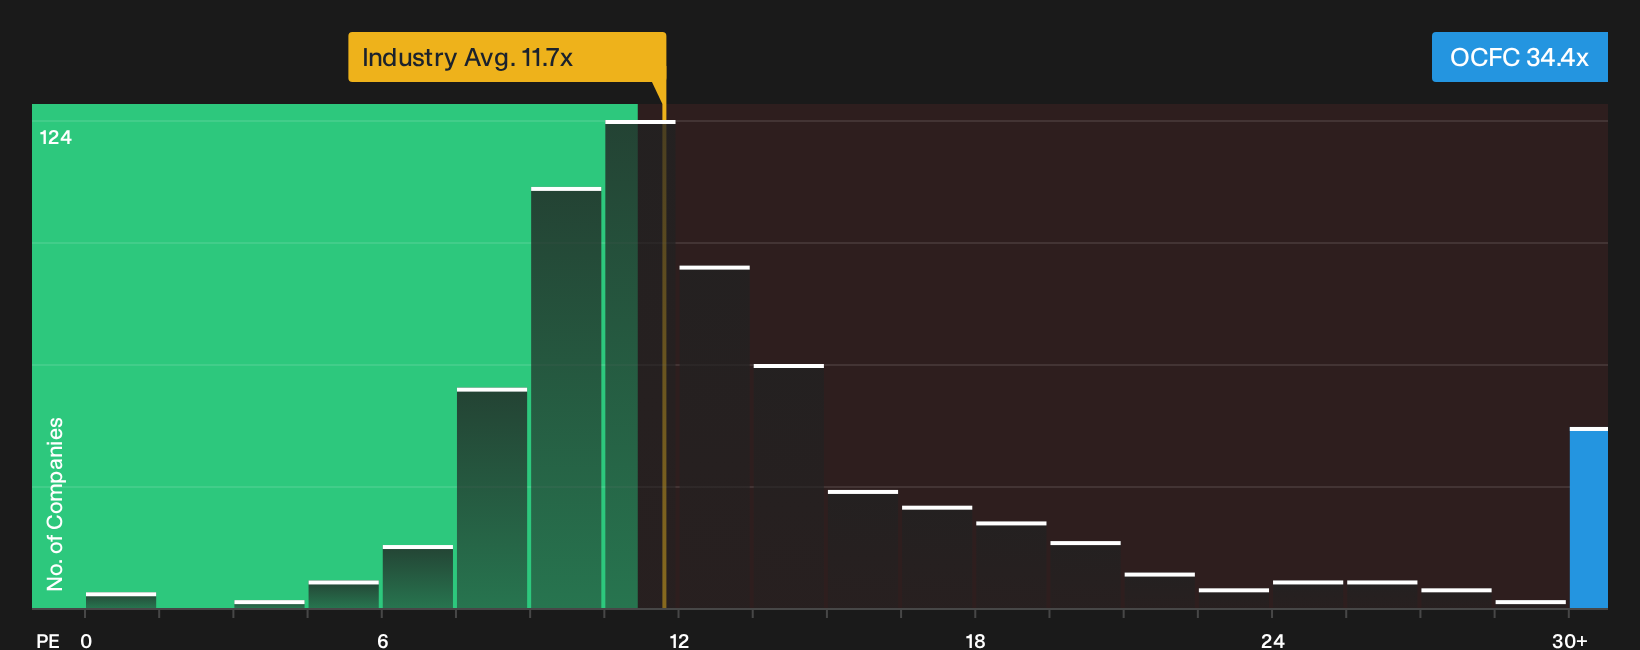
That fair value story contrasts with a very different message when you look at OceanFirst Financial through its P/E ratio. The stock trades on 34.4x earnings, while the wider US Banks group sits at 11.7x and close peers average 13.1x.
The fair ratio for OceanFirst is 28.1x, so the current P/E is not only richer than the sector and peer group, but also above the level the market could potentially gravitate toward over time. For anyone weighing the recent pullback against this premium, the question becomes whether the growth narrative is strong enough to justify paying more on this metric.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around OceanFirst Financial can create debate, so consider reviewing both sides of the ledger yourself and weigh the 3 key rewards and 5 important warning signs.
Looking for more OceanFirst Financial investment ideas?
If OceanFirst Financial has you thinking harder about where to put fresh capital, do not stop at a single ticker. Broaden your watchlist now to avoid missing stronger setups.
- Target resilient growers with healthy fundamentals by scanning the 16 high quality undiscovered gems before other investors start paying attention.
- Prioritize capital protection and steadier rides by checking the 30 resilient stocks with low risk scores that align with your comfort for volatility and potential drawdowns.
- Aim for powerful income potential by reviewing the 6 dividend fortresses that combine robust yield with sound underlying businesses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com