


Asian Growth Leaders With Insider Confidence September 2026
As of September 2026, Asian markets have been navigating a complex landscape marked by inflation concerns and fluctuating bond yields, with technology sectors showing resilience amidst these challenges. In this environment, companies with strong insider ownership often signal confidence in their growth potential, making them noteworthy candidates for investors seeking stability and potential upside in uncertain times.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Meitu (SEHK:1357) | 23% | 26.9% |
| Meiko Electronics (TSE:6787) | 19.2% | 33.8% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| JHT DesignLtd (SHSE:603061) | 23.1% | 48.6% |
| HUMAN MADE (TSE:456A) | 23.9% | 29.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gold Circuit Electronics (TWSE:2368) | 29.8% | 43.6% |
We're going to check out a few of the best picks from our screener tool.
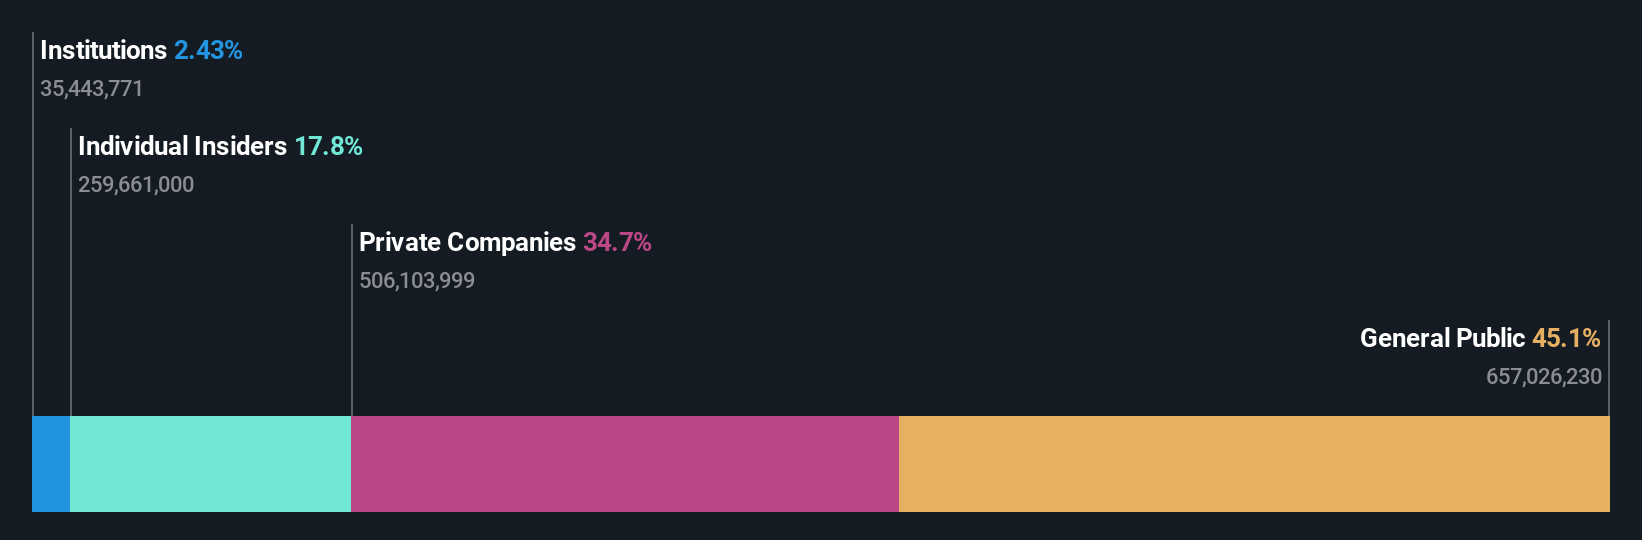
China XLX Fertiliser (SEHK:1866)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: China XLX Fertiliser Ltd. is an investment holding company involved in the development, manufacture, and sale of urea both in Mainland China and internationally, with a market cap of HK$15.81 billion.
Operations: The company's revenue is primarily derived from the sale of urea (CN¥10.47 billion) and compound fertilizer (CN¥9.01 billion), along with significant contributions from chemicals such as methanol (CN¥7.13 billion), liquid ammonia (CN¥3.66 billion), DMF (CN¥1.19 billion), melamine (CN¥958.23 million), and polyoxymethylene (CN¥467.24 million).
Insider Ownership: 19.5%
Earnings Growth Forecast: 21% p.a.
China XLX Fertiliser demonstrates strong growth potential with a significant increase in sales and net income for H1 2026, driven by scale efficiency and optimized product structure. Despite substantial insider selling over the past quarter, the company is trading at 45.2% below its estimated fair value. Earnings are forecast to grow significantly faster than the Hong Kong market, although debt coverage by operating cash flow remains a concern.
- Unlock comprehensive insights into our analysis of China XLX Fertiliser stock in this growth report.
- Our valuation report unveils the possibility China XLX Fertiliser's shares may be trading at a discount.
Geo Energy Resources (SGX:RE4)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Geo Energy Resources Limited is an investment holding company involved in the mining, production, and trading of coal, with a market capitalization of SGD1.08 billion.
Operations: The company generates revenue primarily from its coal mining operations, amounting to $465.50 million.
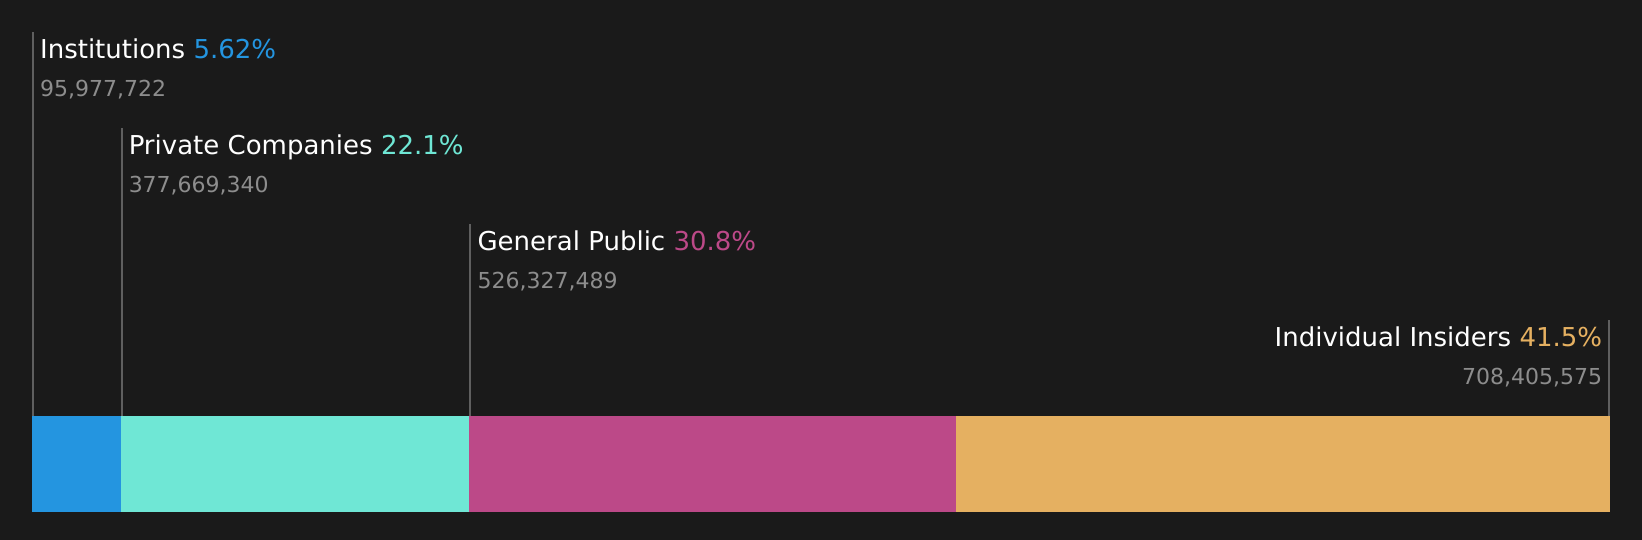
Insider Ownership: 36.5%
Earnings Growth Forecast: 48.4% p.a.
Geo Energy Resources is poised for significant growth, with revenue and earnings projected to outpace the Singapore market substantially. Despite recent shareholder dilution, the company trades at 46% below its estimated fair value. Operational advancements, such as the MBJ Integrated Infrastructure, are set to boost EBITDA by up to US$600 million annually upon full capacity. The company's coal production guidance indicates a ramp-up in output and sales, enhancing its growth trajectory despite recent lower half-year earnings.
- Navigate through the intricacies of Geo Energy Resources with our comprehensive analyst estimates report here.
- Our valuation report unveils the possibility Geo Energy Resources' shares may be trading at a premium.
V5 Technologies (TWSE:7822)
Simply Wall St Growth Rating: ★★★★★☆
Overview: V5 Technologies Co., Ltd. focuses on the research, development, and manufacturing of semiconductor inspection and measurement equipment with a market cap of NT$41.92 billion.
Operations: The company's revenue primarily comes from its Semiconductor Equipment and Services segment, which generated NT$2.75 billion.
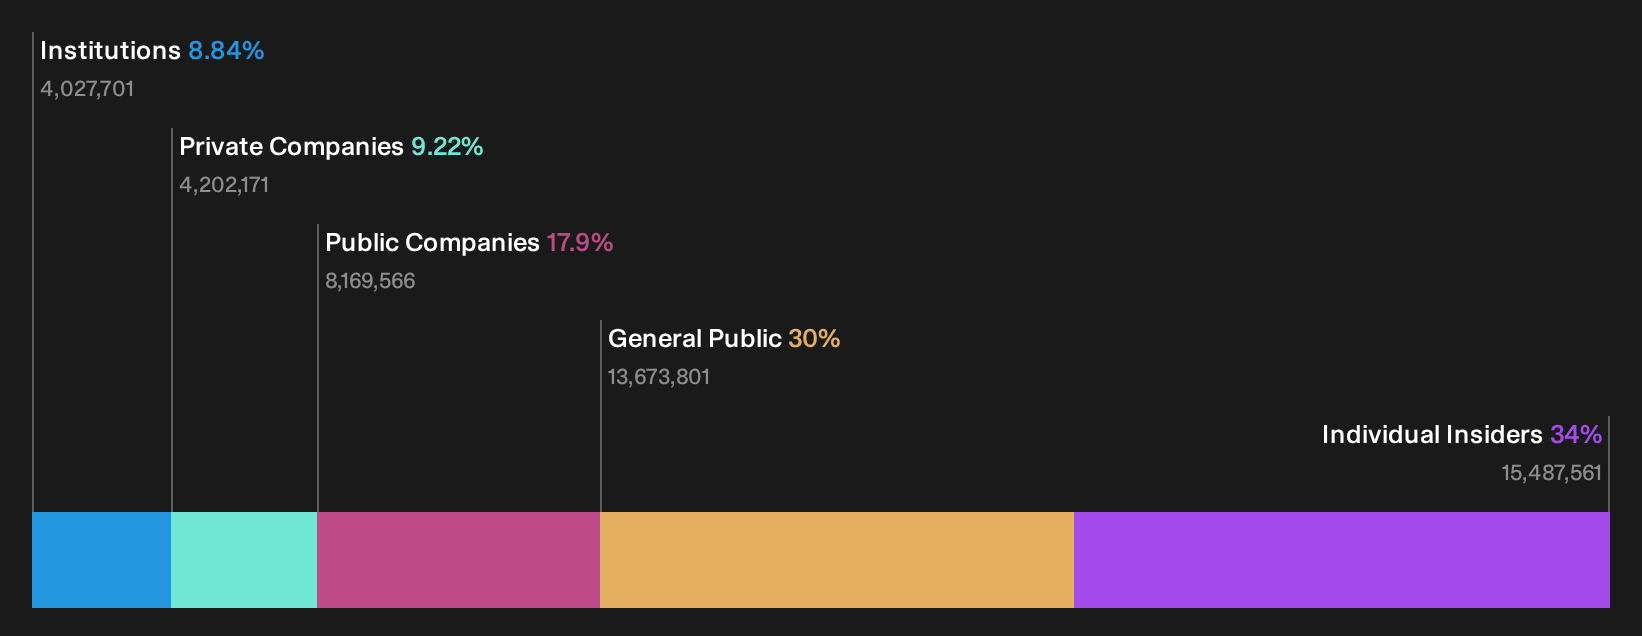
Insider Ownership: 34%
Earnings Growth Forecast: 57.0% p.a.
V5 Technologies demonstrates robust growth potential, with earnings and revenue expected to grow significantly faster than the Taiwan market over the next three years. Recent inclusion in the S&P Global BMI Index underscores its expanding market presence. The company's second-quarter results show a notable increase in sales to TWD 734.85 million and net income of TWD 236.27 million, reflecting strong operational performance without substantial insider trading activity reported recently.
- Delve into the full analysis future growth report here for a deeper understanding of V5 Technologies.
- The valuation report we've compiled suggests that V5 Technologies' current price could be inflated.
Seize The Opportunity
- Click this link to deep-dive into the 488 companies within our Fast Growing Asian Companies With High Insider Ownership screener.
- Ready To Venture Into Other Investment Styles? Trump's oil boom is here — pipelines are primed to profit. Discover the 80 US stocks riding the wave.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com