


Marriott International (MAR) Reworks Credit Facility As Valuation Debate Stays In Focus
Marriott International (MAR) just reworked its core credit facility with lenders, lifting total commitments to $5.0b, extending maturity to 2031 and adding room for rate adjustments tied to environmental performance metrics.
Marriott International’s latest credit agreement lands while the share price sits at US$352.03, with a 7 day share price return of 2.73% and a year to date share price return of 12.32%. However, the 90 day move is down 5.01%, so recent momentum looks softer than the longer trend implied by the 1 year total shareholder return of 33.03%.
Scan how Marriott International’s refinancing compares with peers by reviewing the hand picked list of solid balance sheet and fundamentals (24 results) that also emphasize funding flexibility and balance sheet strength.
Short term, Marriott International’s slower 90 day move clashes with that strong 1 year run. The real issue now is whether current pricing already reflects that stronger footing or leaves enough upside to justify waiting for a cheaper entry.
Most Popular Narrative: 7.6% Undervalued
At a last close of $352.03 against a narrative fair value of $380.80, Marriott International is framed as slightly undervalued, with that gap hinging on how fee based growth and loyalty economics play out over time.
Diversification of high margin offerings and alternate fee streams continues to build, as luxury and premium properties show higher RevPAR in recent quarters and co branded credit card economics are expected to add about US$30 million of incremental 2026 fees and potentially US$100 million to US$125 million of incremental annual fees by 2028, which supports higher gross fee revenue and earnings.
See why 32 investors see Marriott International as 8% undervalued.
Result: Fair Value of $380.80 (UNDERVALUED)
Still, the narrative around Marriott International can unravel if Middle East RevPAR weakness persists, or if richer owner economics drag on margins without delivering stronger net unit growth.
Find out about the key risks to this Marriott International narrative.
Another View On Marriott International’s Valuation
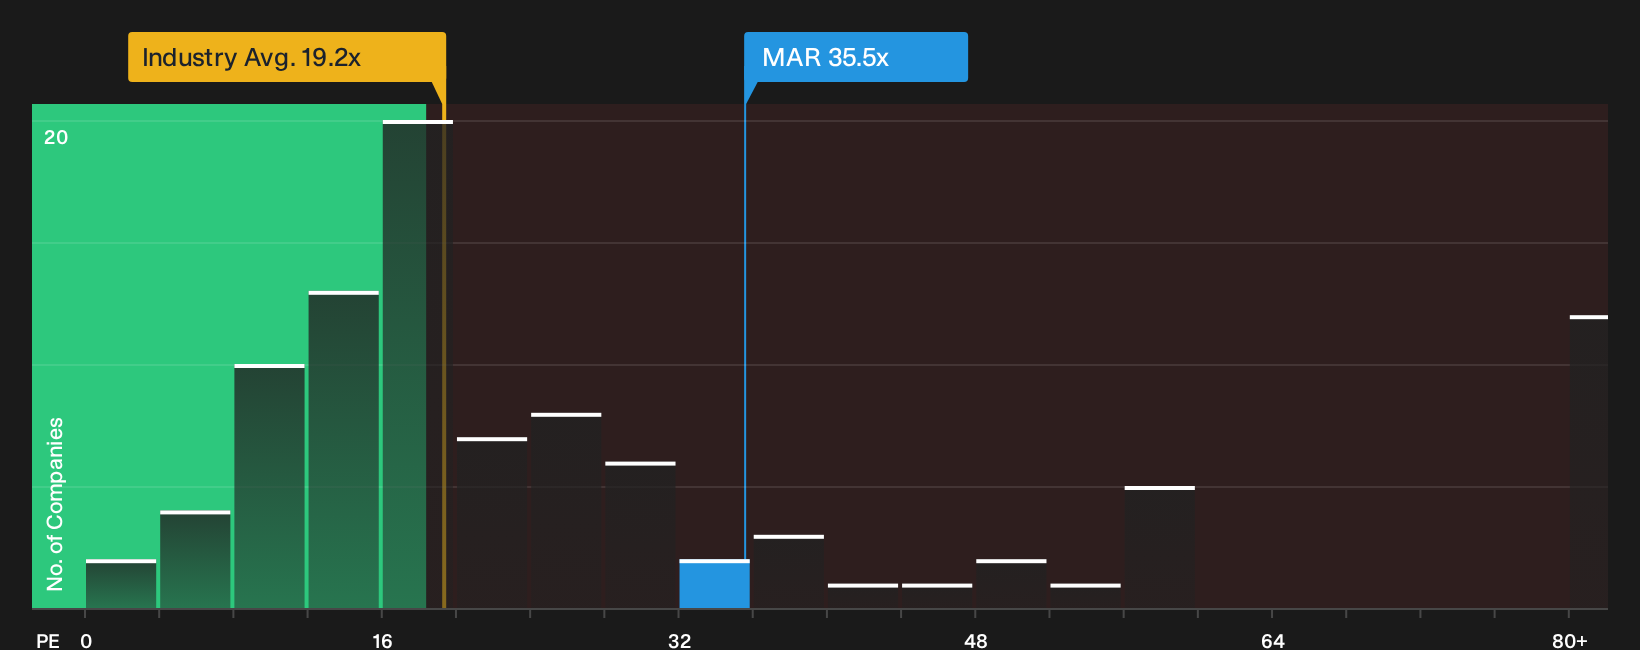
The narrative fair value paints Marriott International as 7.6% undervalued, yet the P/E ratio of 35.5x tells a sharper story. That multiple is higher than both the US Hospitality industry at 19.2x and the fair ratio of 27.7x, so pricing leaves less room for error if growth or margins slip.
Our valuation tools dig into this gap in more detail, showing how current pricing compares with what the fair ratio suggests the market could move toward, and where that leaves potential valuation risk for investors weighing entry points today See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Marriott International’s valuation and momentum create a clear split between cautious and optimistic sentiment, so it makes sense to move quickly and test the numbers yourself. To weigh both sides in one place, review the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Marriott International?
If Marriott International has sharpened your focus, do not stop here. Use fresh screeners to spot opportunities before they move and pressure test your next idea.
- Target potential upside by scanning quality companies that market pricing may be overlooking through the 32 high quality undervalued stocks.
- Strengthen your income game by checking out reliable payers in the 7 dividend fortresses.
- Dial back risk while staying invested by focusing on resilient businesses in the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com