


UniFirst (UNF), What Is Behind The Attention Now?
UniFirst (UNF) drew fresh attention after its recent share performance, with the stock last closing at $259.09. Investors are weighing this uniform and facility services provider’s returns against its current earnings profile.
Recent trading tells a mixed story. The share price is down 8.1% over the past month and slightly lower over 90 days. Yet UniFirst still carries a strong year to date share price return of 33.8% and a 1 year total shareholder return of 56.4%, which points to longer term momentum outweighing the latest pullback as investors reassess growth prospects and risk.
Compare UniFirst’s recent momentum with other service providers by scanning our hand picked list of solid balance sheet and fundamentals (24 results), which may offer a similar mix of resilience and share price strength.
UniFirst now trades only about 5% below the average analyst target, even after a sharp run and recent pullback. Is that discount a genuine opportunity, or is it a warning that caution on valuation is warranted?
Most Popular Narrative: 7% Undervalued
On the most widely followed view, UniFirst’s fair value sits at $279, compared with the recent $259.09 close. This puts the current quote below that reference point and frames the recent pullback as a test of that narrative.
Significant investments in technology, specifically an ERP system, are anticipated to enhance efficiency, leading to improved profitability and reduced operational costs once fully implemented, which should impact net margins positively in the long run. Expansion of the distribution center in Owensboro, Kentucky, is expected to improve speed and efficiency in direct sales of uniforms, potentially driving revenue growth through enhanced operational capacity.
See why 2 investors see UniFirst as 7% undervalued.
Result: Fair Value of $279 (UNDERVALUED)
Still, two pressure points could unsettle that 7% undervalued story for UniFirst: softer wearer levels and rising health care costs that squeeze profitability.
Find out about the key risks to this UniFirst narrative.
Another View On UniFirst’s Valuation
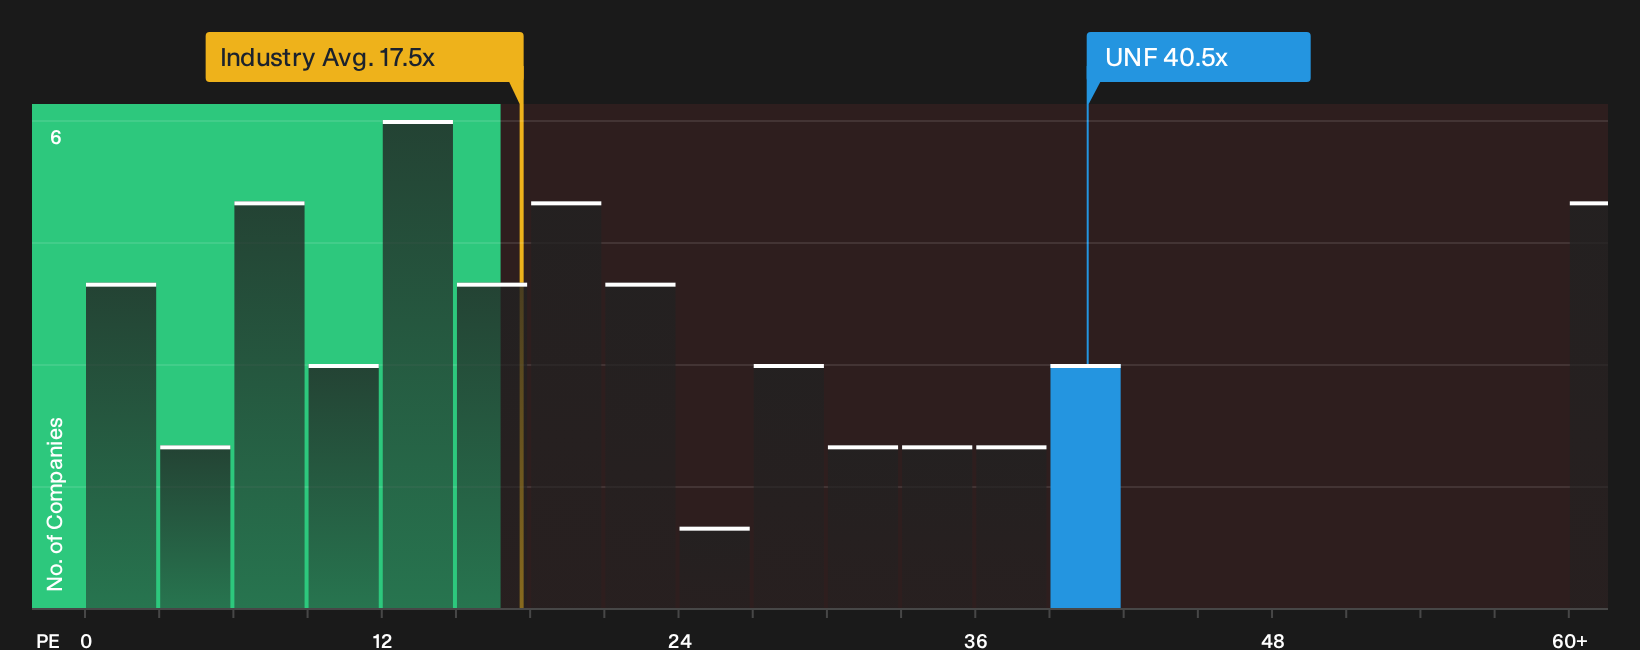
There is a catch to the 7% undervalued story. On earnings multiples, UniFirst trades on a P/E of 40.5x, while the Commercial Services industry averages 17.5x and peers sit near 26.3x. The fair ratio is 22.6x, which suggests meaningful valuation risk if sentiment cools.
For a closer look at how those earnings multiples compare with what the fair ratio implies, take a few minutes to run through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Plenty in this UniFirst story points to optimism, yet valuation questions linger, so weigh the full picture and move fast to frame your own stance. To see what is driving that optimism, review the 1 key reward
Looking for more ideas beyond UniFirst?
If you stop with UniFirst, you risk missing out on other opportunities that fit your goals, so put a few minutes into scanning fresh ideas with the Simply Wall St screener.
- Target sturdier portfolios by reviewing a curated 30 resilient stocks with low risk scores that aims to keep drawdowns in check while still giving your capital room to work.
- Hunt for potential mispricings by filtering through the 32 high quality undervalued stocks that focuses on companies with strong fundamentals at more modest valuations.
- Spot future market leaders early by scanning the 16 high quality undiscovered gems that flags quality businesses investors have not widely focused on yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com