


Top 3 Japanese Dividend Stocks To Watch In September 2026
Global markets have been swinging as bond yields react to higher interest rates and volatile oil, which can rattle share prices but leave reliable cash dividends looking more appealing. For investors in Japanese dividend stocks, income from well covered payouts above 3% can feel more predictable than day to day price moves. This article profiles three high yielding dividend players from Japan that fit that brief.
The stocks profiled below are just a starting sample in this search for reliable income, and the full screen surfaced 546 more companies with equally compelling dividend stories that are not covered here. To identify and analyze the highest conviction income ideas that match your own risk and yield preferences, head straight into the Dividend Powerhouses (3%+ Yield) screener.
Tokio Marine Holdings (TSE:8766)
Overview: Tokio Marine Holdings is a long established Japanese insurer whose non life and life underwriting businesses generate recurring cash flows that support dividends.
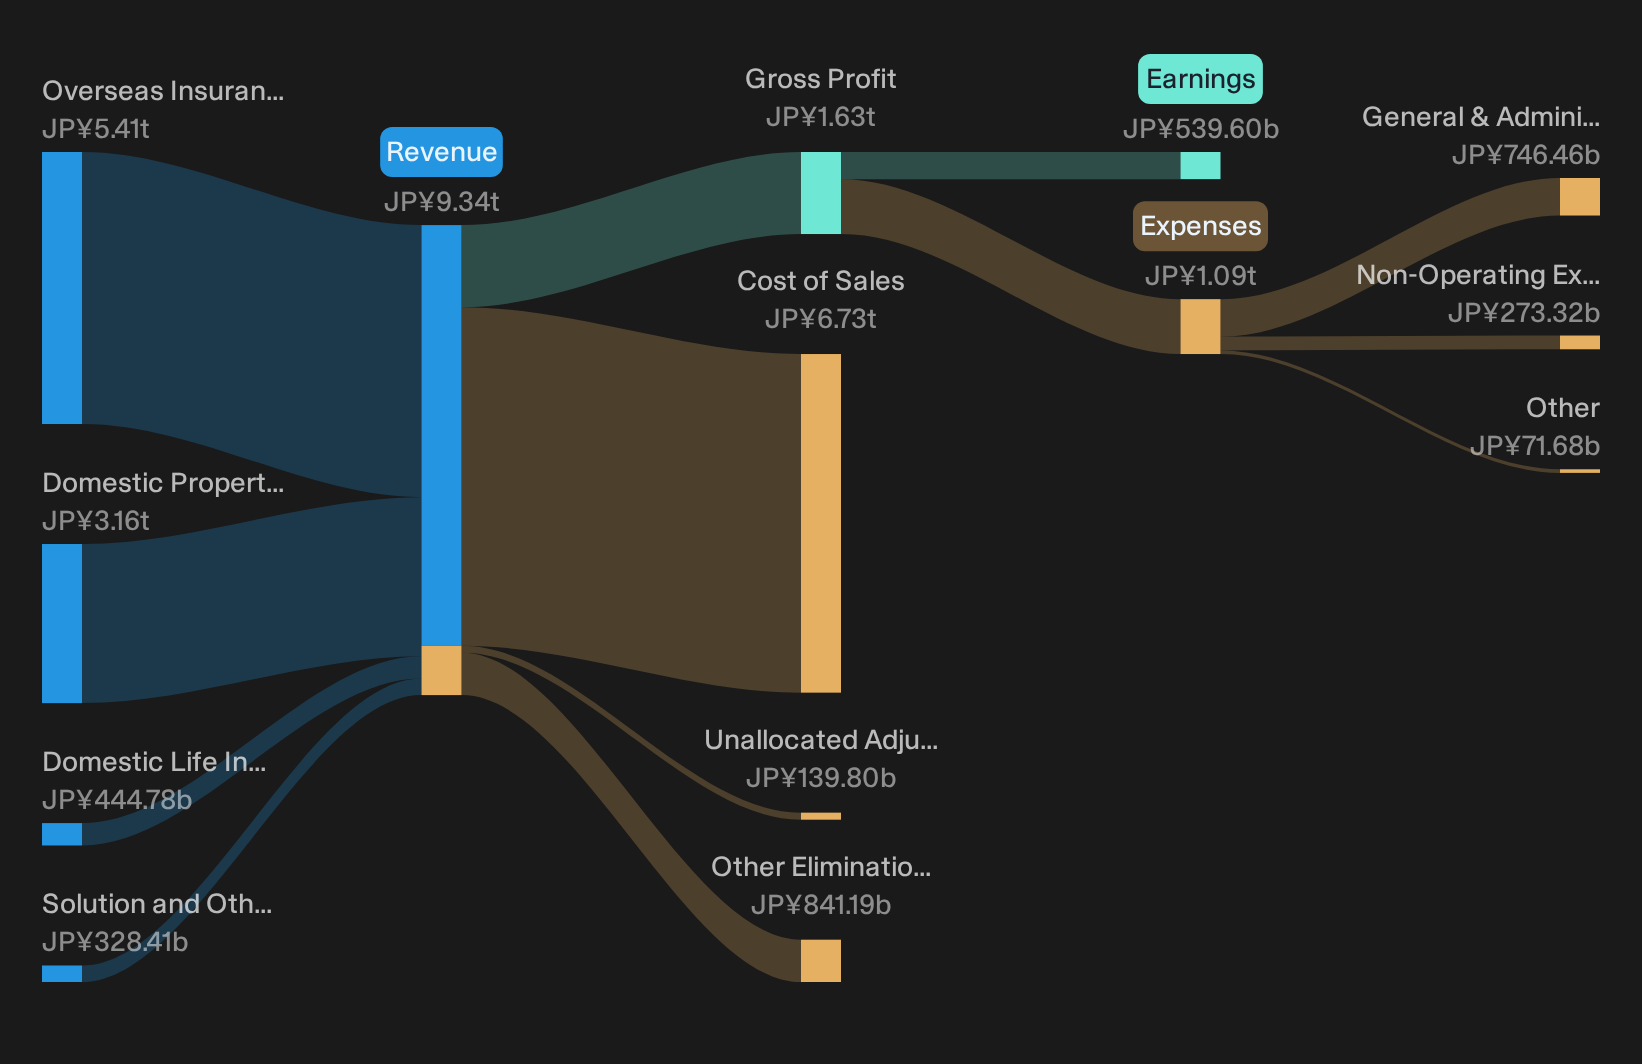
Operations: Tokio Marine earns most of its revenue from overseas insurance at ¥5,408b and domestic property and casualty insurance at ¥3,163b, with smaller contributions from domestic life insurance and solution businesses.
Market Cap: ¥15,184.8b
Tokio Marine Holdings matters for a 3%+ dividend screen because its global insurance engine generates recurring policy cash flows that can underpin regular payouts even when markets are volatile.
"AI and data usage is being rolled out across Japan P&C, Brazil and North America to improve cost efficiency and underwriting. However, the scale and complexity of group wide implementation create execution risk. Slower than expected benefits could delay planned reductions in expense ratios and limit EPS growth."
For income focused investors, a single pressure on how that insurance book is priced could quietly decide whether margins comfortably cover those future dividends.
Those margin pressures are only half the story, and the full narrative for Tokio Marine Holdings shows how Tokio Marine Holdings could still turn that execution risk into a dividend holding opportunity.
Daiichi Life Group (TSE:8750)
Overview: Daiichi Life Group is a Tokyo based insurer that sells life and related protection products, using long term policy cash flows to support a stable dividend.
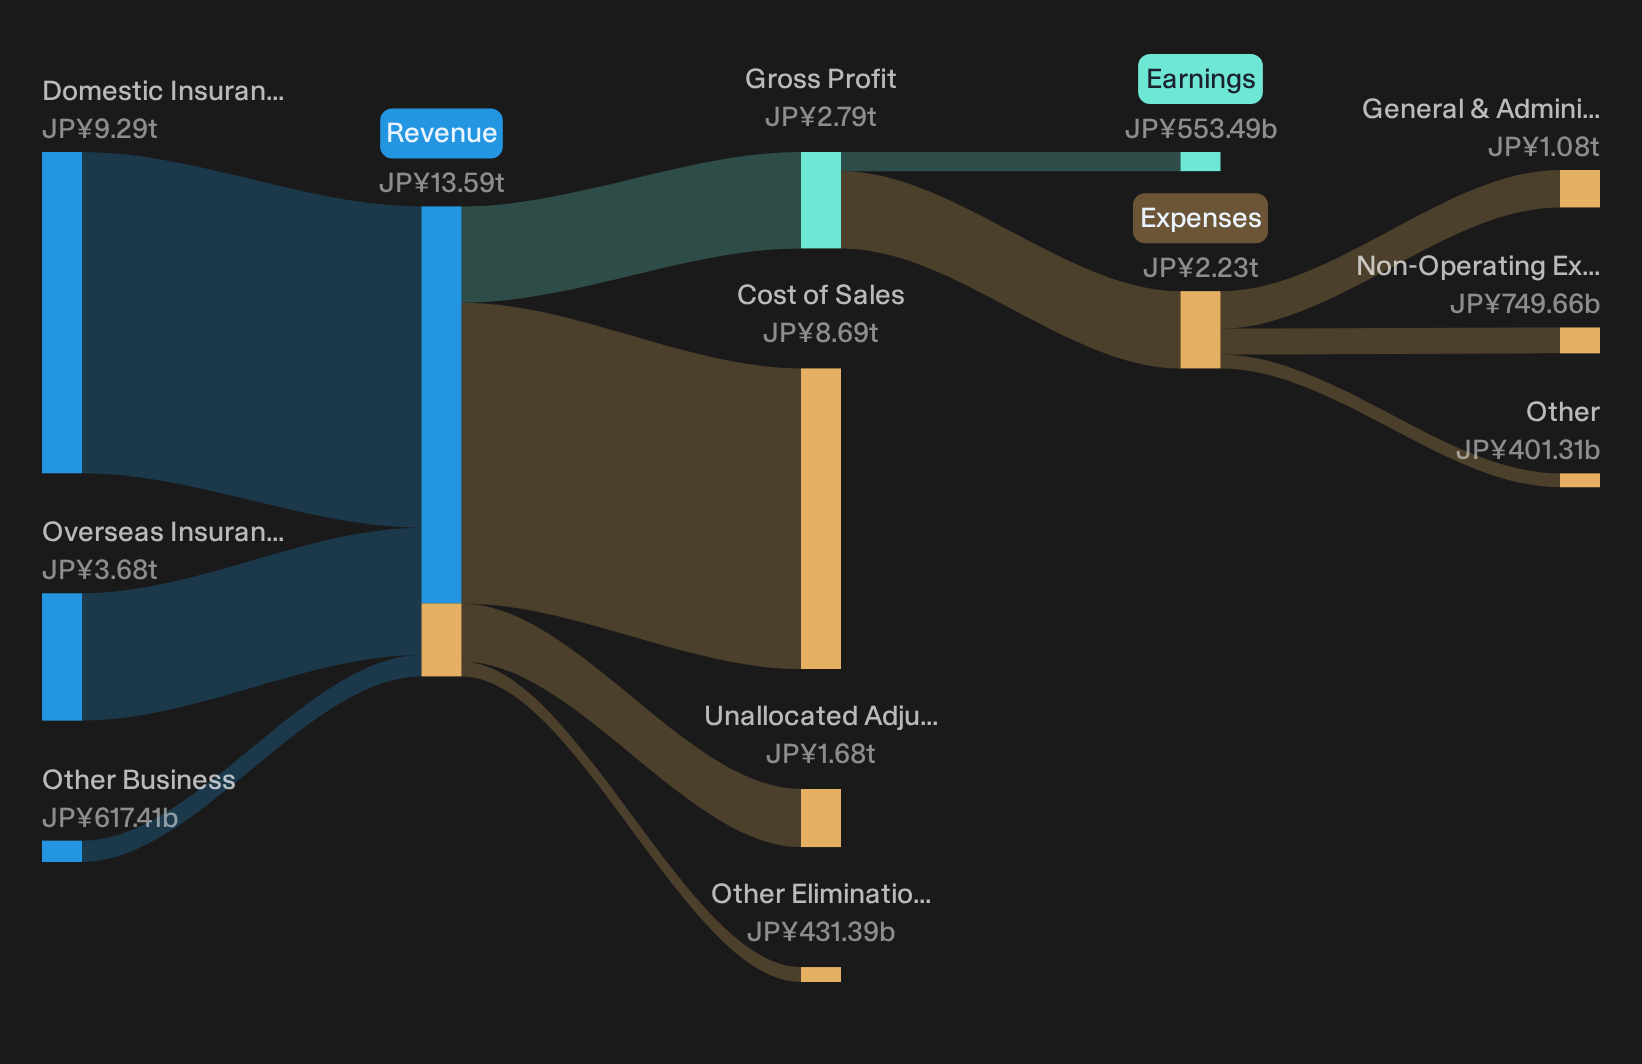
Operations: Daiichi Life Group generates most revenue from its Domestic Insurance Business at ¥9.3t, with ¥3.7t from Overseas Insurance and a smaller Other Business.
Market Cap: ¥6.9t
Income seekers looking at Daiichi Life Group are really assessing how dependable its life insurance cash flows and capital buffers are for supporting a growing dividend stream that already clears the screener’s 3% hurdle.
"Expansion in international business, particularly in Asia and Australia, is delivering strong profit growth and improving diversification, reducing reliance on Japan's mature insurance market, which in turn supports higher consolidated revenue and earnings stability."
What happens if one quiet shift in its balance between domestic policies, overseas earnings and capital requirements presses harder on those payout plans.
That quiet shift is exactly what the full narrative for Daiichi Life Group unpacks, revealing how Daiichi Life Group's overseas push and capital discipline could be accelerating an underappreciated dividend story.
Japan Tobacco (TSE:2914)
Overview: Japan Tobacco is a Tokyo based tobacco group whose cigarette and reduced risk products generate most of the cash that supports its dividend profile, with a smaller processed food arm contributing a modest share of earnings.
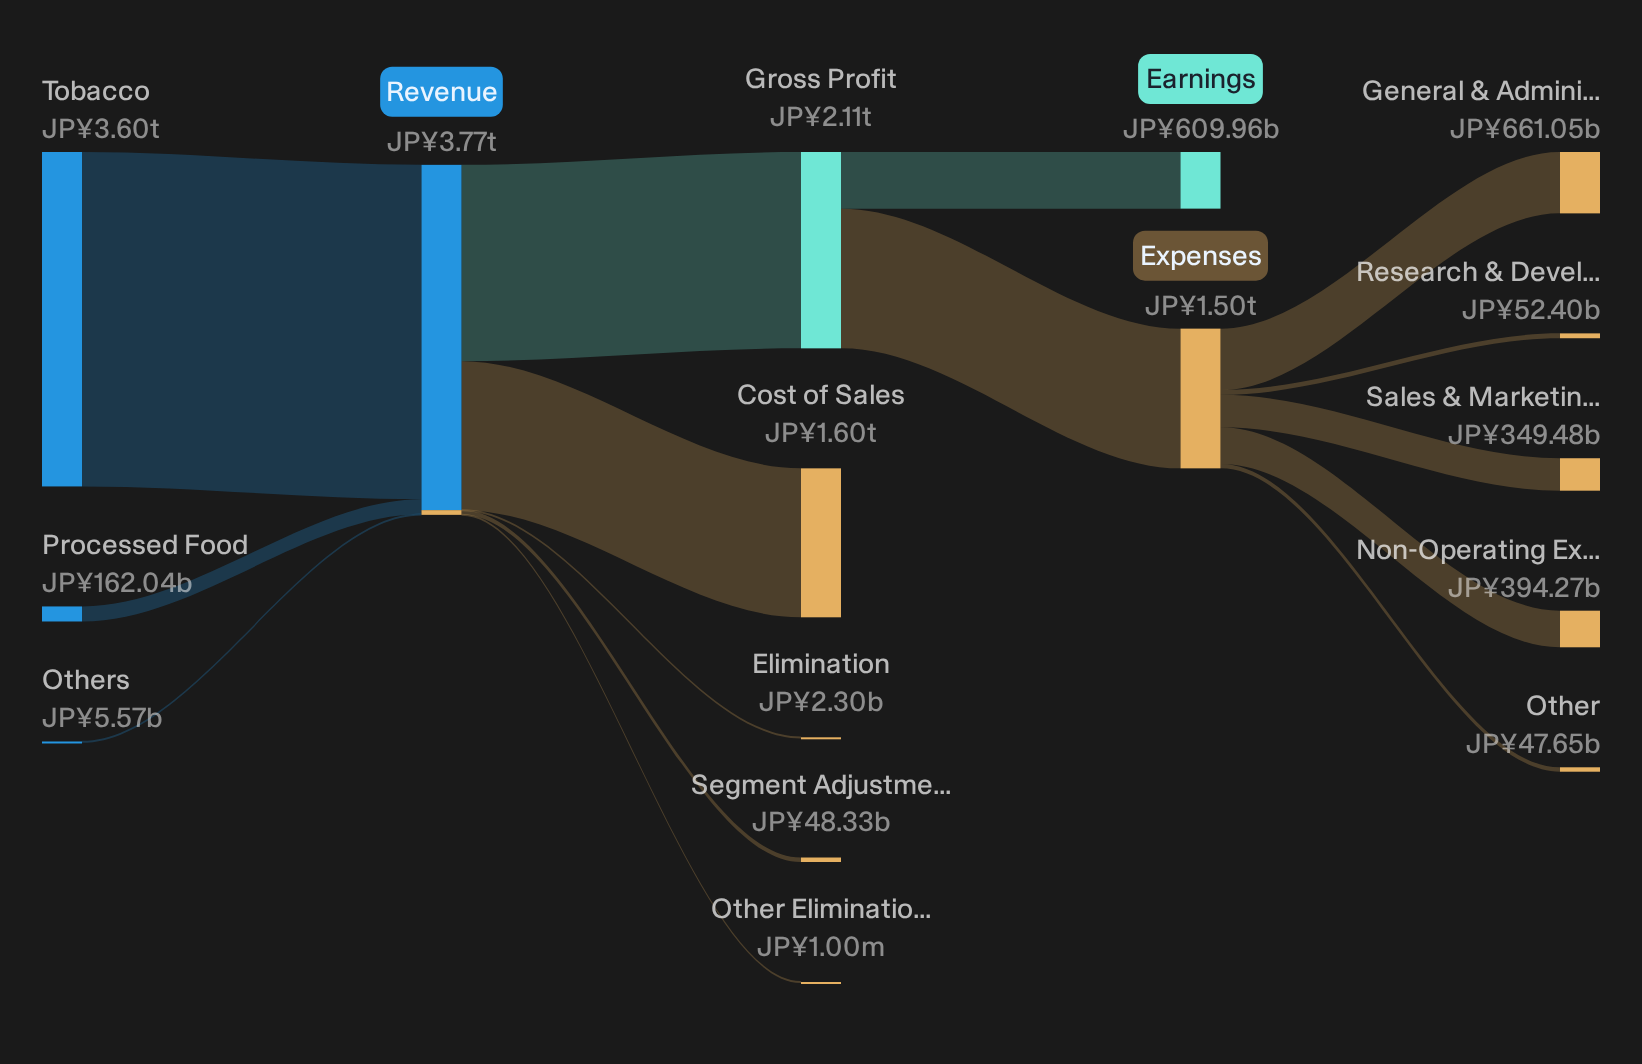
Operations: Japan Tobacco generates around ¥3.6t from Tobacco, ¥162b from Processed Food and ¥1.8t from EMA, with ¥904b from Asia.
Market Cap: ¥12,326.9b
Japan Tobacco matters for this Dividend Powerhouses screen because its tobacco cash flows underpin the current 3.96% yield and give management room to adjust payouts as earnings and reduced risk products evolve.
"Expansion of harm-reduction products like Ploom AURA and EVO addresses evolving consumer preferences for reduced-risk options, with segment share gains and plans for accelerated international rollout. This is expected to support sustained future revenue growth and improved net margins over the medium term."
What happens if a single shift in how quickly that newer product mix turns truly profitable changes the cushion under those future payouts?
That timing question is exactly what the full narrative for Japan Tobacco tackles, showing where Japan Tobacco's cash engine, product shift, and risk profile could be quietly decoupling from expectations.
Seeking Alternatives Before The Crowd?
Fresh income ideas can shift quickly as momentum changes, yields adjust and quiet outliers move under the radar. Scan these curated lists before potential entry points change. Act now.
- Target resilient compounding potential by filtering for strong balance sheets and robust fundamentals through the curated list of solid balance sheet and fundamentals (22 results) while these quieter performers stay under the radar for now.
- Hunt for metal producers that can support portfolio diversification using the focused 36 elite gold producer stocks before interest cycles or sentiment shifts draw additional attention to these miners.
- Track infrastructure trends related to tomorrow's electricity backbone with the hand picked 40 power grid technology and infrastructure stocks before grid technology and hardware leaders attract broader market focus.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com