


ExxonMobil Holdings (XOM), Why Is It Back In The Spotlight?
ExxonMobil Holdings (XOM) is back in focus after management paused its Baytown blue hydrogen project, citing limited customer demand and policy uncertainty for this type of lower carbon business.
Against that backdrop, ExxonMobil Holdings’ share price has eased 1-day but still carries a 7-day share price return of 1.45% and a 90-day gain of 17.46%. The 1-year total shareholder return of 44.67% and 5-year total shareholder return of 210.04% signal that longer term momentum has been strong even as investors reassess newer lower carbon projects like Baytown in light of policy and demand risks.
Scan hand-picked energy producers with strong balance sheets and cash flows that might echo ExxonMobil Holdings’ resilience using our 32 high quality undervalued stocks.ExxonMobil Holdings now trades below both its analyst target and an intrinsic value estimate, even after the recent pullback. Is that discount still justified once the assumptions behind those fair value ranges are unpacked?
Most Popular Narrative: 6% Undervalued
ExxonMobil Holdings last closed at $160.59, while the most widely followed narrative pegs fair value near $170.91. This frames the current pullback as a discount that depends heavily on how future volumes, margins and cash discipline play out.
Strong production growth from high return assets in Guyana and the Permian Basin remains central, with upstream volumes outside the Middle East at the highest level in more than two decades and the Permian at over 1.8 million oil equivalent barrels per day, which supports future revenue and earnings per barrel.
Guyana has already recovered about US$55b of investment and operating costs nearly two years earlier than anticipated, and the desaturation of this cost bank is expected to roughly double free cash flow between 2025 and 2030 versus 2025 levels, which feeds into future earnings and cash generation.
See why 340 investors see ExxonMobil Holdings as 6% undervalued.
Result: Fair Value of $170.91 (UNDERVALUED)
Still, ExxonMobil Holdings faces real pressure if long term oil demand weakens faster than expected, or if its low carbon projects fail to scale into meaningful contributors.
Find out about the key risks to this ExxonMobil Holdings narrative.
Another View: ExxonMobil Holdings On Earnings Multiples
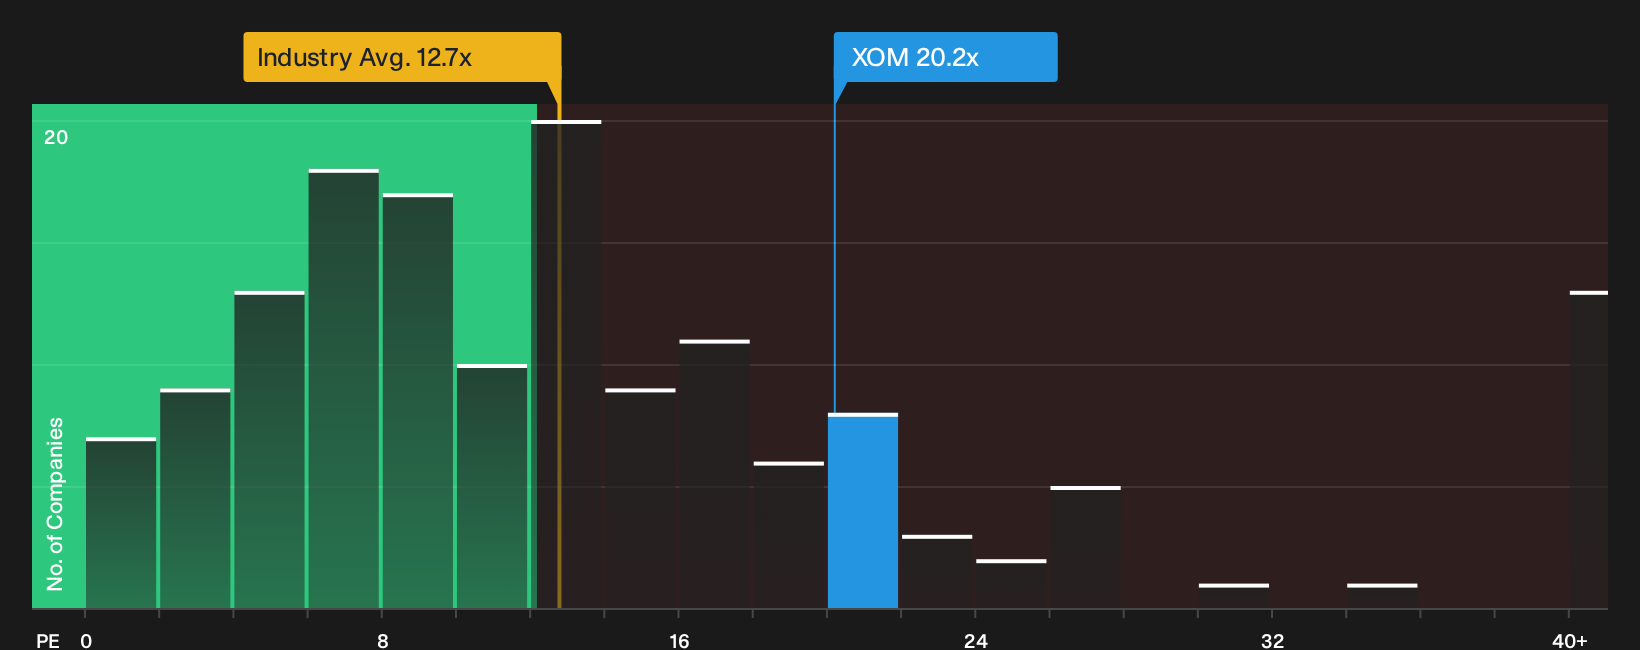
The fair value story for ExxonMobil Holdings looks supportive on discounted cash flow, yet the P/E ratio paints a tighter picture. The stock trades on 20.2x earnings, richer than both peers at 16.4x and the wider US Oil and Gas group at 12.7x, even though the fair ratio sits higher at 27.8x.
This gap suggests investors are already paying a premium to the sector while still sitting below where the market could move if it leans toward that fair ratio. The question for you is whether modest forecast growth, forecast earnings quality and capital discipline justify paying up for ExxonMobil Holdings at this multiple, or whether it leaves less room for error in future expectations.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on ExxonMobil Holdings is mixed, which is exactly when doing your own homework matters most. Move quickly and weigh the upside case using the 4 key rewards.
Looking for more ExxonMobil Holdings style ideas?
If you like how ExxonMobil Holdings blends cash generation with long term themes, you can use the Simply Wall Street Screener to broaden your opportunity set before the crowd.
Discover new ideas across the market with targeted filters that surface stocks by quality, valuation and resilience so you are not relying on headlines alone.
- Target potential value opportunities early by scanning a curated 32 high quality undervalued stocks that combines quality fundamentals with discounted pricing.
- Explore income focused ideas by reviewing a focused 8 dividend fortresses built around higher yield payouts and robust underlying businesses.
- Prioritise resilience by searching a 30 resilient stocks with low risk scores that is centred on steadier balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com