


Why China Nonferrous Mining (SEHK:1258) Is Back In The Spotlight
China Nonferrous Mining (SEHK:1258) has drawn fresh attention after its recent share performance, with the stock down about 11% over the past month but up roughly 30% over the past 3 months.
For context, the recent pullback follows a strong upswing, with China Nonferrous Mining’s 90 day share price return of 30.5% sitting alongside a 1 year total shareholder return of 19.7%, and a larger multi year total shareholder return that indicates momentum has been building rather than fading.
Scan other copper focused opportunities on Simply Wall St by comparing China Nonferrous Mining with the 17 top copper producer stocks that analysts are watching closely right now.
After a 30% climb in 3 months and a recent 11% pullback, China Nonferrous Mining now trades at a wide discount to both intrinsic value estimates and analyst targets. Is the market being careful, or simply too cautious?
Preferred P/E of 13.4x for China Nonferrous Mining: Is it justified?
China Nonferrous Mining closed at HK$15.49 while trading on a P/E of 13.4x that sits above the Hong Kong metals and mining industry average but well below its closer peer group.
The P/E multiple compares the current share price with earnings per share and effectively tells you how many years of profit the market is willing to pay for today. For a miner with exposure to copper and cobalt, investors often watch this yardstick to gauge how much profit resilience and future earnings power are being factored into the HK$15.49 price.
China Nonferrous Mining is described as expensive when set against the broader Hong Kong metals and mining sector, where the average P/E is 9.6x. At the same time, it is labelled good value versus its more direct peers, where the average multiple is a much higher 30.7x. When stacked against an estimated fair P/E of 11.9x, the current 13.4x suggests the market is paying a premium to that fair level and could eventually move closer to that lower benchmark if sentiment cools.
The contrast between an industry average of 9.6x and a current market tag of 13.4x is sharp. This signals investors are assigning richer terms to China Nonferrous Mining than the wider sector. Compared with the 11.9x fair P/E estimate, the current rating again looks stretched, pointing to a valuation that leans more on optimism than on the fair ratio level the numbers imply.
Explore the SWS fair ratio for China Nonferrous Mining.
Result: Price-to-earnings of 13.4x (OVERVALUED).
Still, China Nonferrous Mining relies on copper and cobalt markets and operates in Zambia and the DRC, where price swings and political shifts can quickly hit sentiment.
Find out about the key risks to this China Nonferrous Mining narrative.
Another view on China Nonferrous Mining’s value
The P/E work suggests China Nonferrous Mining looks a bit rich, yet the SWS DCF model points the other way. On that framework, HK$15.49 is described as well below an estimated future cash flow value of HK$50.68, which frames the share price as heavily undervalued instead.
Two lenses are telling very different stories. One treats the current earnings multiple as stretched. The cash flow model, in contrast, implies a large value gap that the market has not closed. Which signal do you weigh more heavily when both are on the table?
Look into how the SWS DCF model arrives at its fair value.
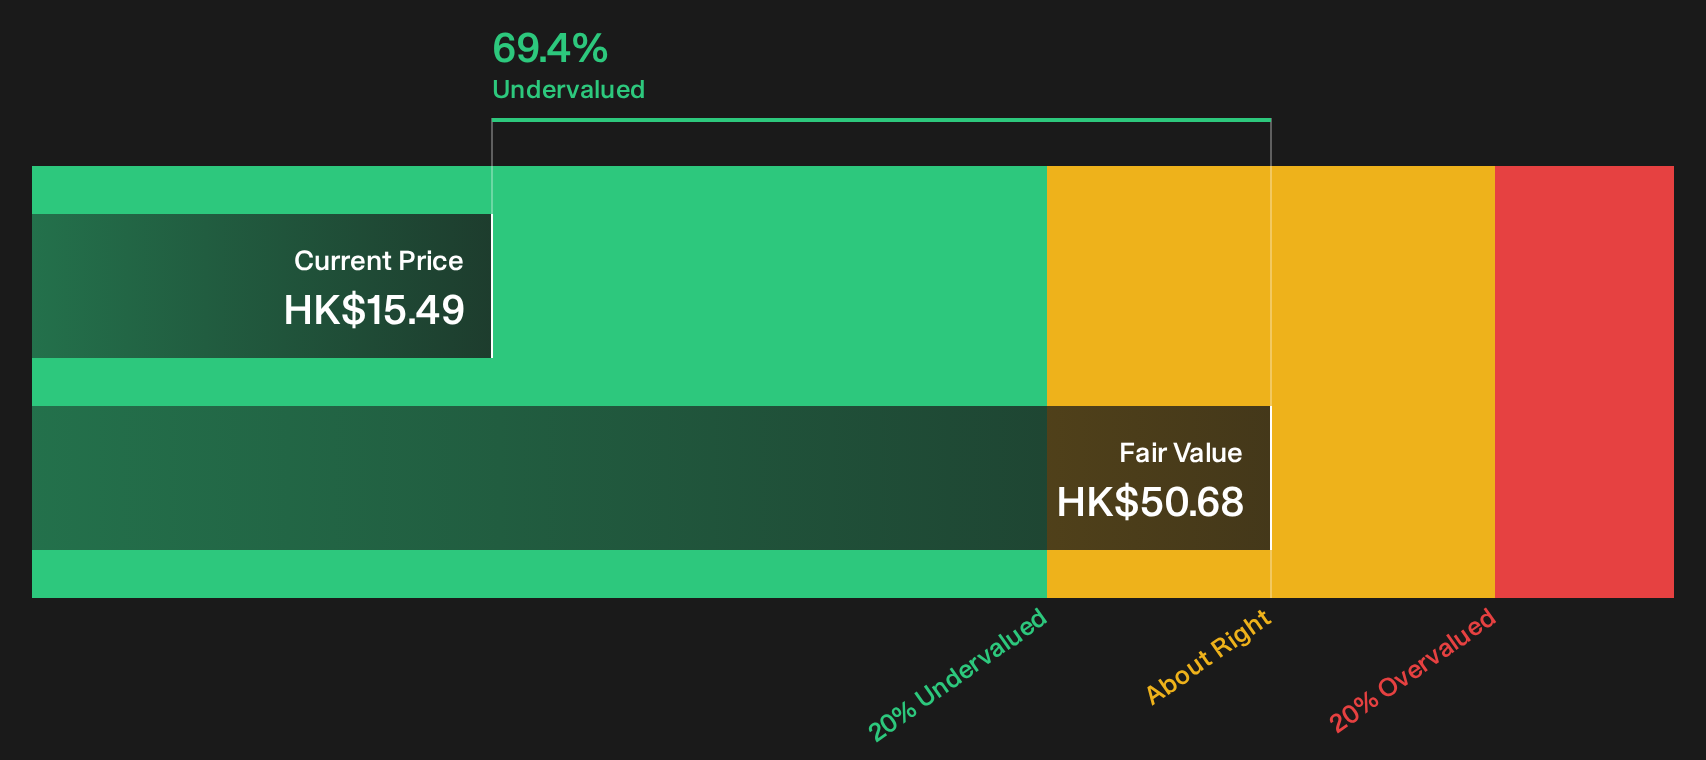
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Nonferrous Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 184 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on China Nonferrous Mining is clearly split, which makes this an interesting moment to review the numbers yourself and not just the headlines. Act quickly, weigh the upside against your own risk tolerance, and then check the 3 key rewards.
Looking for more investment ideas beyond China Nonferrous Mining?
If China Nonferrous Mining has your attention, you can use that momentum and run a quick screen so you are not leaving other potential opportunities on the table.
- Target resilient balance sheets by scanning the list of solid balance sheet and fundamentals (201 results) to find companies that combine financial strength with room for future decisions.
- Hunt for potential mispricings by reviewing the 618 high quality undiscovered gems before the wider market focuses on them.
- Prioritise calmer portfolio candidates by checking the 226 resilient stocks with low risk scores to help keep volatility in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com