


Emami And 2 Indian Dividend Stocks To Own
Global bond markets have pushed long term interest rates to multidecade highs, and Australia’s 10 year government yield is near 5.5%, so cash and term deposits finally pay something again. That tempts many investors to sit on the sidelines. It also creates a window where solid Australian dividend payers offering yields above 3% and consistent payout records can look especially appealing. This article highlights three such stocks from our high yield screener.
The three stocks covered below are just a sample. The full Dividend Powerhouses screen surfaced 44 more companies with yields above 3% and equally compelling income stories that are not unpacked here. To identify and analyze those potential dividend payers for yourself, head straight into the Dividend Powerhouses (3%+ Yield) screener.
Emami (BSE:531162)
Overview: Emami is an Indian FMCG group that sells personal care and healthcare brands such as BoroPlus, Zandu, Navratna, Kesh King and Dermicool, using their steady cash generation to support its dividend profile.
Operations: Emami reports about ₹39.1b in revenue from personal and healthcare products, with roughly ₹32.5b from India and ₹6.6b from overseas markets.
Market Cap: ₹169.9b
For a dividend investor, Emami matters because its everyday personal care labels throw off recurring cash flow, which can underpin a 3% plus yield while leaving room for reinvestment in the brands that keep that income stream resilient.
"Analyst consensus expects portfolio revamps in male grooming and hair care (Smart & Handsome, Kesh King) to revive growth, but this may be understated. With multiple simultaneous launches, deep research-driven product improvements, celebrity endorsements, and cross-channel D2C and offline targeting, Emami is positioned not just to regain share, but to drive step-change category expansion, leading to above-trend revenue acceleration and faster share gains than the market currently discounts."
What happens to Emami’s dividend story if a single key assumption about how quickly consumer demand shifts in its core categories breaks.
If that demand shift is what you are weighing, the full narrative for Emami explains how Emami’s cash engine, brand risk and potential acceleration fit together in more detail.

Bhansali Engineering Polymers (BSE:500052)
Overview: Bhansali Engineering Polymers manufactures ABS, SAN and related specialty resins. It uses this plastics business to generate the cash underpinning its 3% plus dividend.
Operations: Bhansali Engineering Polymers reports about ₹14,402 million in revenue from manufacturing ABS and SAN resins for industrial and consumer applications.
Market Cap: ₹31.4b
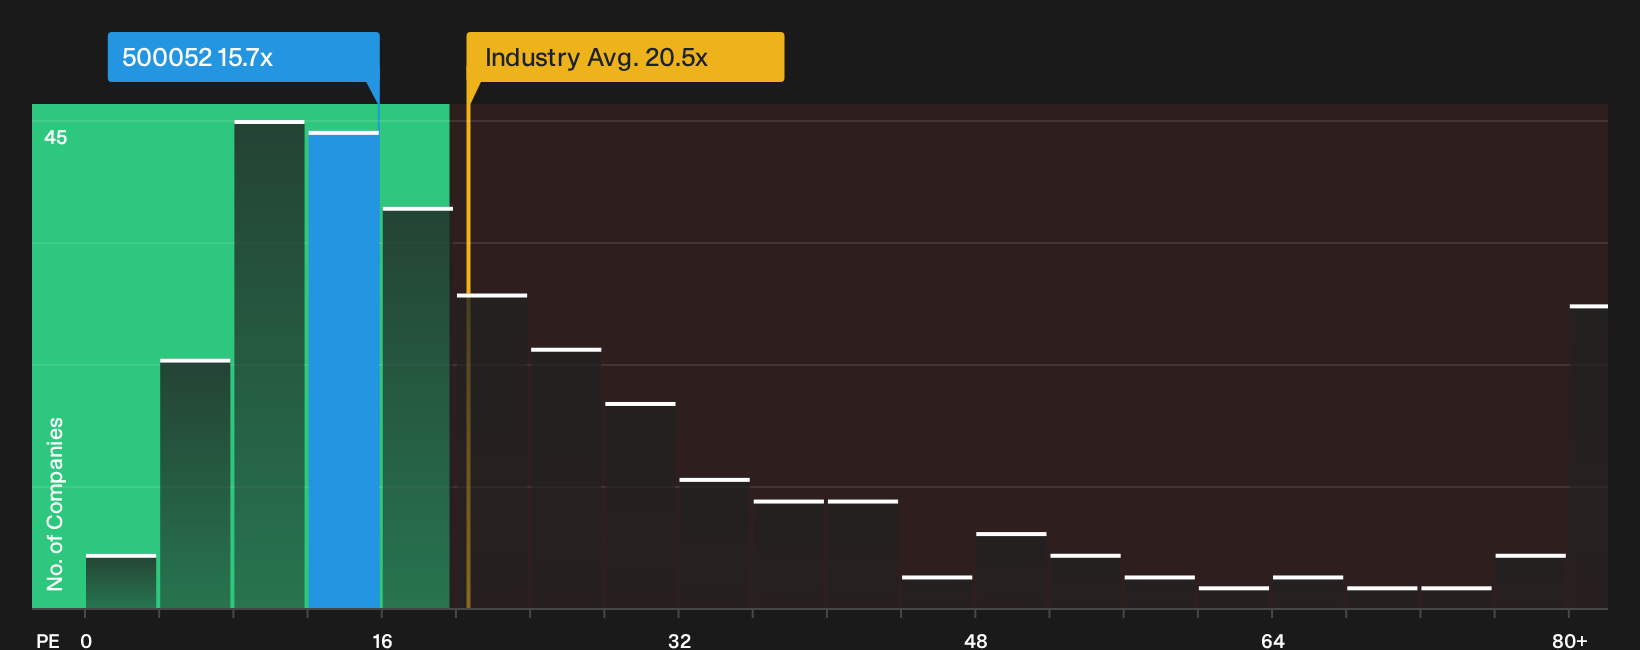
Bhansali Engineering Polymers interests income focused investors because a 3.17% dividend is backed by ABS and SAN resin cash flow, a 15.7x P/E that sits below Indian chemicals peers, and improving profitability. One unseen pressure on longer term earnings trends is likely to decide how durable that payout really is.
That unseen pressure could be the hinge for future returns. Check the 2 key rewards and 1 important major warning sign to see what might accelerate or cap Bhansali Engineering Polymers from here.
Gujarat Energy (NSEI:GUJENERGY)
Overview: Gujarat Energy runs a large city gas distribution network supplying piped gas and CNG across several Indian states and territories.
Operations: Gujarat Energy generates most of its ₹273.1b in India revenue from city gas distribution and gas trading, with smaller power and E&P contributions.
Market Cap: ₹221.4b
For dividend hunters, Gujarat Energy matters because its regulated gas distribution network produces utility-like cash generation that can support a covered, 3% plus payout, while management also funds network expansion and cleaner fuel projects.
"Sustained policy and consumer momentum towards cleaner fuel usage and rapid urban expansion are supporting strong double-digit growth in CNG volumes, with Q1 FY '26 seeing 12% YoY CNG volume increase and the company expecting to outpace even last year's 11% growth due to robust CNG vehicle additions and strategic infrastructure investments."
What happens to Gujarat Energy’s dividend strength if a single cost pressure quietly squeezes the gap between steady volumes and actual cash available?
That squeeze risk is exactly what the full narrative for Gujarat Energy unpacks, revealing how Gujarat Energy’s regulated model and growth projects could keep dividends accelerating instead of stalling.

Curious About What You Might Be Missing?
Fresh ideas do not stay under the radar for long. Screen for breakouts and quiet compounders before the crowd catches on and while valuations still matter. Act now.
- Spot cash rich businesses with low debt loads and steady momentum, then filter them instantly with the list of solid balance sheet and fundamentals (201 results).
- Hunt for resilient earnings stories that aim to pair lower volatility with upside by scanning the 226 resilient stocks with low risk scores curated by strict risk filters.
- Target early stage upside in smaller companies tied to artificial intelligence trends by running the 37 profitable AI stocks that aren't just burning cash before those stories start flying.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com