


Oscar Health (OSCR) Shares Moved, What Is Catching Investors' Attention?
Why Oscar Health’s latest product push matters now
Fresh commentary around Oscar Health (OSCR) centers on management’s push for higher earnings per share through tighter medical loss ratios, new offerings such as the Lucy Healthcare Marketplace, and wider use of AI tools.
At a share price of $29.60, Oscar Health has pulled back over the past week with a 7 day share price return of down 5.4% and a 30 day share price return of down 2.9%. However, the 90 day share price return of 3.8% and year to date share price return of 97.7%, alongside a 1 year total shareholder return of 54.7% and a 3 year total shareholder return above 4x, suggest momentum over the longer stretch is still strong as investors weigh the earnings story behind management’s product and AI rollout.
Compare Oscar Health’s AI and marketplace push with peers by scanning our curated list of 38 healthcare AI stocks that could be setting up for their next major move.
Oscar Health trades at $29.60 while analysts sit closer to $35.40. With that gap and a multi year return above 4x, the question is where fair value really lands now.
Most Popular Narrative: 95% Undervalued
Against a last close of $29.60, the leading valuation story on Oscar Health pins fair value at $583.34. This frames the recent pullback very differently for anyone focused on long term upside.
Every so often, a ticker flashes on my screen that makes me stop and rub my eyes. It is the kind of number that look like a mistake, like you thought you were getting clothes on Christmas Day, but then your parents surprise you by hiding the PlayStation 2 you've been wanting for months in the other room...
The screen showed Oscar Health. Ridiculous name for a health insurance company, but the numbers are anything but.
See why 11 investors see Oscar Health as 95% undervalued.
According to J_Tyrader, the detailed discounted cash flow work assumes a 25.0% growth rate for ten years, fading to 2.5%, and still arrives at that $583.34 estimate using a 9.6% discount rate, which is far above the current market value of the shares.
The same narrative points to $15.32b of trailing revenue and highlights that a large portion is described as converting to cash flow, alongside reference to a sizeable net cash cushion and what is described as strong returns on invested capital. These factors are presented as anchoring the argument that Oscar Health has more financial flexibility than many listed insurers.
The stress testing in that write up also matters for readers who worry about aggressive assumptions, since the author spells out how shifts in the growth rate or discount rate affect the outcome rather than relying on a single scenario.
Result: Fair Value of $583.34 (UNDERVALUED)
Still, Oscar Health’s story could be knocked off course if medical loss ratios move against expectations or if AI and marketplace investments do not translate into durable profitability.
Find out about the key risks to this Oscar Health narrative.
Another view on Oscar Health’s valuation
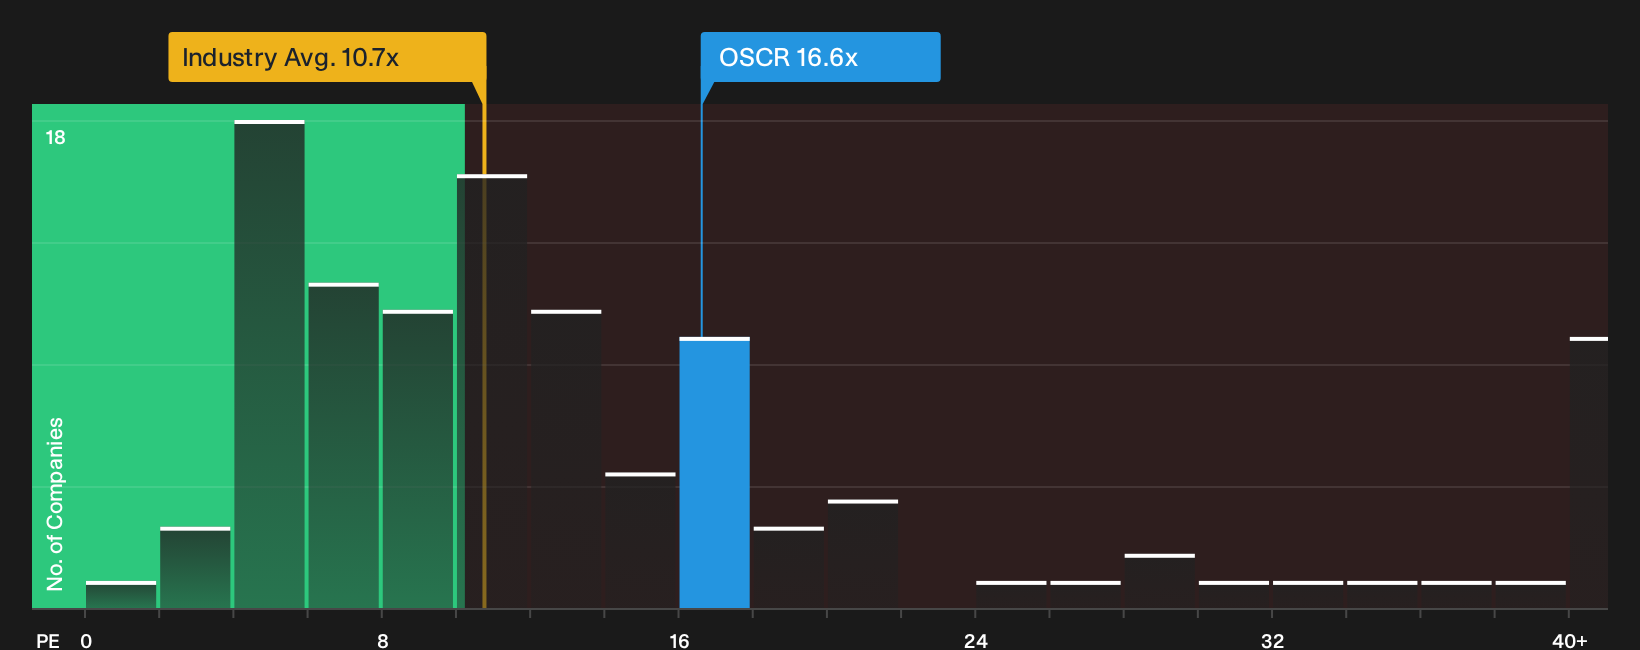
The DCF-style narrative around Oscar Health is eye catching, yet the current P/E of 16.6x tells a more grounded story. That multiple is higher than the US insurance industry at 10.7x but below the peer average of 32.5x and an estimated fair ratio of 23.3x, which points to both upside potential and mispricing risk. Which signal would you trust when sentiment cools?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Oscar Health can leave even experienced investors second guessing their instincts. Move quickly, pressure test the data, and then rely on your own judgment by weighing its 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Oscar Health?
If Oscar Health has sharpened your focus on valuation and quality, you may want to widen your opportunity set now so you are not relying on a single story.
- Hunt for potential bargains that pair solid fundamentals with attractive pricing by scanning our curated list of 32 high quality undervalued stocks.
- Strengthen the quality of your watchlist by checking companies with resilient finances through the list of solid balance sheet and fundamentals (24 results).
- Balance return potential with a focus on resilience by reviewing 30 resilient stocks with low risk scores before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com