


Elite Cash Flow Stocks For September 2026
The bond market just woke up to 5% U.S. Treasury yields, and cash suddenly has real competition again. That shift can pressure richly priced stories, yet it also leaves some solid cash generators trading at what look like clearance tags. This article breaks down three stocks that our cash flow focused value screen flags as mispriced, and explains why patient investors may want them on the watchlist now.
The three examples below are just a small sample, with the full screen surfacing 39 more businesses where discounted cash flow analysis flags equally compelling stories that do not fit into this article. If you want to identify and analyze the highest conviction ideas straight away, head into the Undervalued Stocks Based On Cash Flows screener.
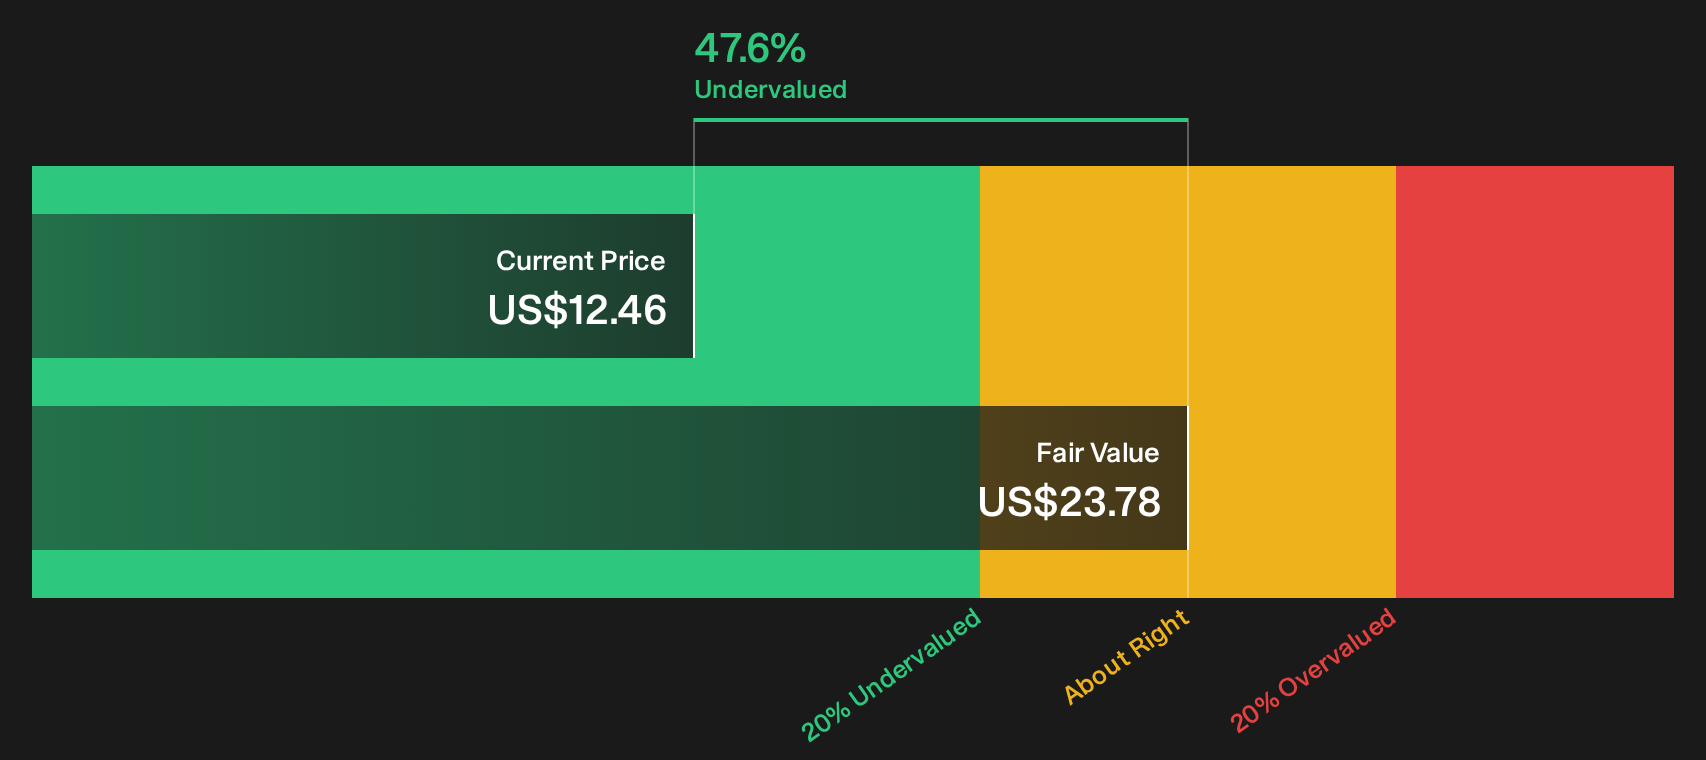
UiPath (PATH)
Overview: UiPath provides an enterprise automation platform that uses RPA, AI agents, and orchestration tools to power recurring subscription cash flows.
Operations: UiPath generates about US$1.7b from software and programming, with meaningful exposure across the United States, EMEA, Asia Pacific, and the rest of the Americas.
Market Cap: US$6.5b
UiPath sits in this cash flow focused screen, since its automation platform is built around long term subscriptions and maintenance contracts that can compound over time.
"New product launches such as Agent Builder and Agentic Orchestration, along with strategic partnerships like with Microsoft and Deloitte, are positioned to expand market opportunities, potentially increasing earnings through higher-value deals."
The key factor for UiPath is how a subtle shift in customer spending patterns shapes the pace of recurring cash generation.
As that spending pattern evolves, read the full narrative for UiPath to see how UiPath’s cash engine could accelerate or stall from here.
Broadcom (AVGO)
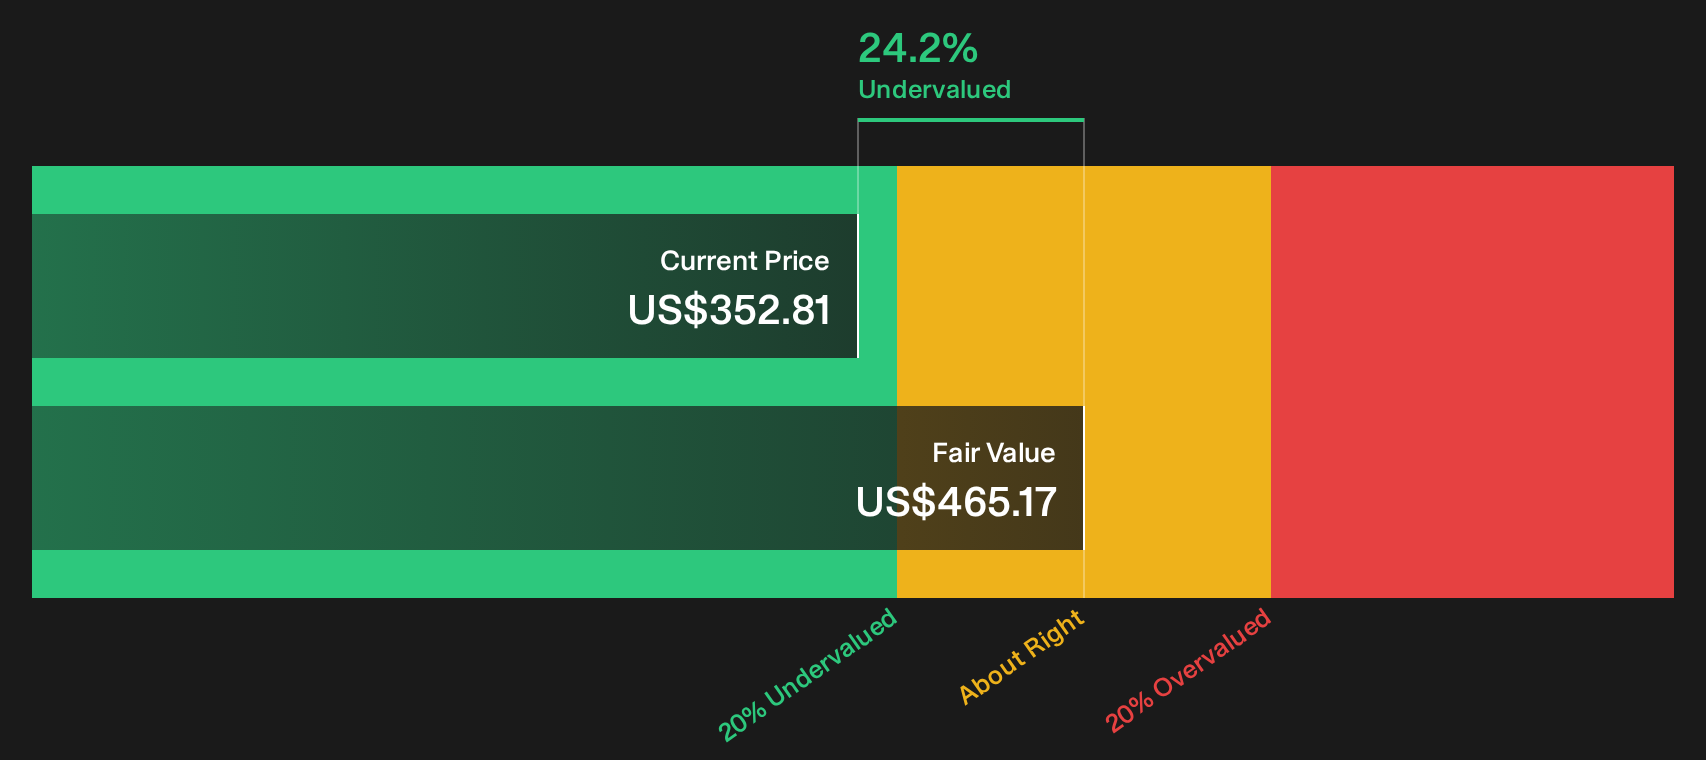
Overview: Broadcom provides semiconductor hardware and infrastructure software, with its VMware and enterprise platforms generating recurring subscription and support cash flows.
Operations: Broadcom reports about US$59.4b from Semiconductor Solutions and US$29.7b from Infrastructure Software, reflecting a hardware led but software rich mix.
Market Cap: US$1,684.2b
Broadcom matters for this cash flow focused screen because its infrastructure software arm converts long contracts into steady, high margin subscription money that supports a discounted cash flow view of the whole group.
"Broadcom is generating substantial free cash flow, expanding its custom silicon business, strengthening its position in networking, and integrating software assets that further diversify earnings."
What happens to that cash engine if a single unseen pressure changes how customers commit to multi year software and AI hardware deals?
If that pressure is what you are weighing, read the full narrative for Broadcom to see whether Broadcom’s cash engine is quietly accelerating or masking brewing risks.
Amazon.com (AMZN)
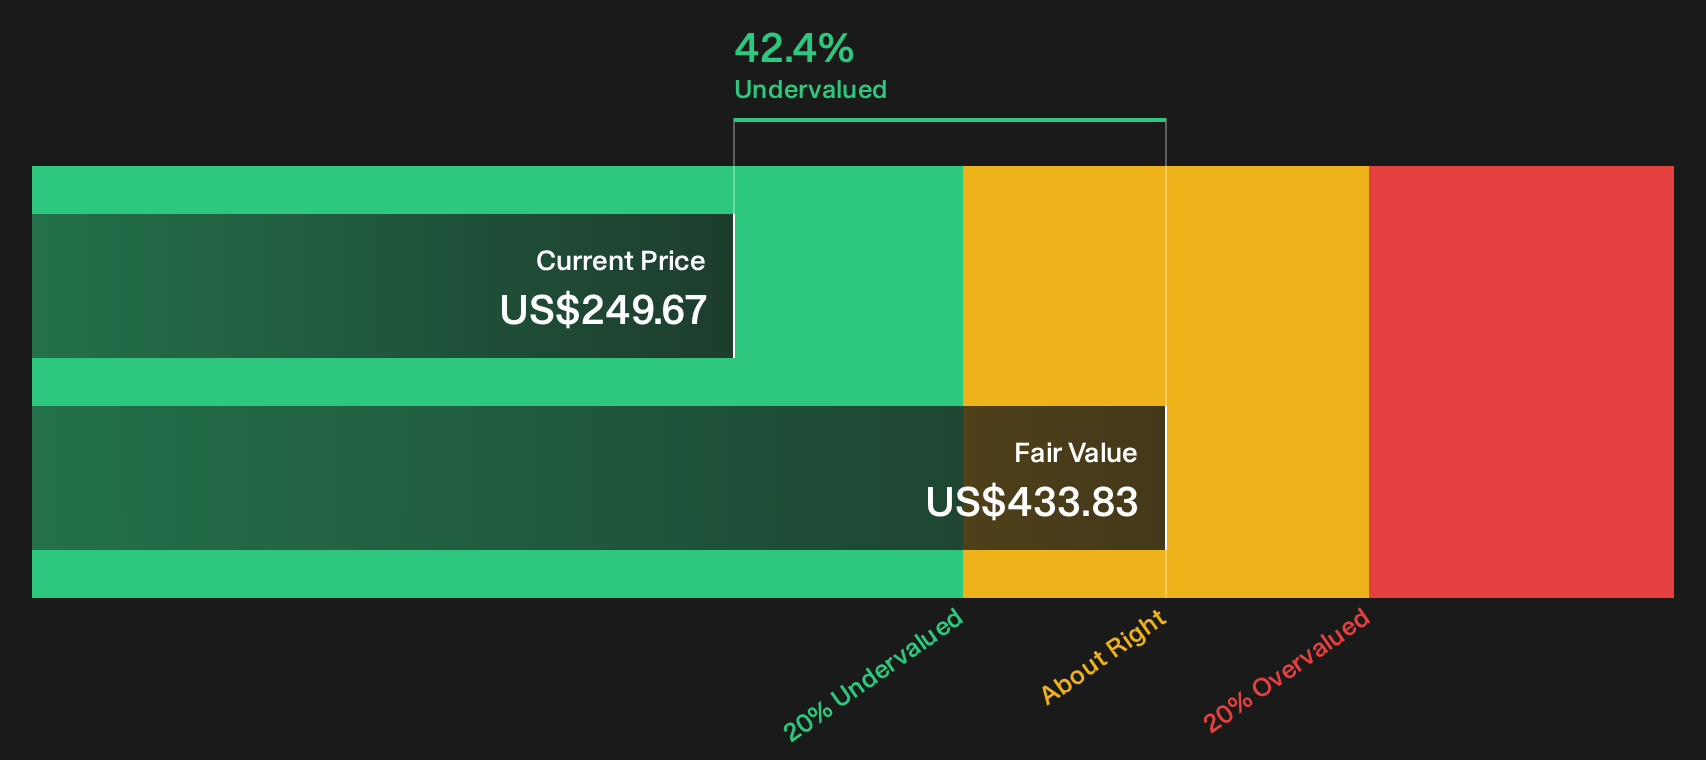
Overview: Amazon.com runs global online and physical retail stores, AWS cloud computing services, and a fast growing digital advertising and subscription ecosystem.
Operations: Amazon.com generates about US$453.7b from North America, US$173.6b from International, and US$148.4b from AWS cloud services.
Market Cap: US$2,693b
Amazon.com matters for this cash flow focused screen because AWS throws off recurring, contract based cash that anchors discounted cash flow models even while retail and advertising shape the broader story.
"AWS reaccelerated through 2025 with roughly 20% year-over-year growth, exiting the year with an annualized revenue base exceeding $130 billion. Advertising has quietly become Amazon’s second major growth engine, approaching a $70 to $80 billion annualized run rate and growing north of 20% year over year."
What happens to Amazon.com’s future margin profile if a single key assumption about that AI heavy buildout and cash conversion cycle breaks.
If that assumption matters to you, read the full narrative for Amazon.com to see how Amazon.com’s cash engine could be accelerating, masking risks, or quietly decoupling.
Seeking Fresh Alternatives Before They Fly
Fresh opportunities do not stay quiet for long. Breakout momentum often gets caught late, once the crowd arrives and prices move. Scan these under the radar ideas while it matters and aim to get in early.
- Target resilient cash generators before volatility hits by running the 30 resilient stocks with low risk scores and focusing on businesses built to handle rougher markets without losing financial footing.
- Spot early winners in AI infrastructure by scanning the 85 AI infrastructure stocks and zeroing in on suppliers positioned at the center of data center and compute demand.
- Hunt for future robotics leaders by working through the curated 92 robotics and automation stocks and filtering for automation specialists already converting real projects into solid balance sheet strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com