


Top 3 Australian AI Stocks To Watch In September 2026
The AI boom has pushed Australia’s 10 year government bond yield near 5.5%, which raises the bar for every investment competing for your cash. Higher yields make it harder for hype to justify lofty prices, yet they also expose solid AI related businesses that have been left behind on valuation. This article walks through three undervalued Australian AI stocks drawn from our screener that merit a closer look.
The three stocks covered below are only a small sample of the undervalued AI opportunities on the radar. The full screen surfaced 0 more companies with equally compelling narratives that are not featured in this article.
If you want to quickly identify which AI related businesses best fit your own criteria, head straight to the Undervalued Artificial Intelligence/ AI Stocks screener to filter, analyze, and focus on your highest conviction ideas.
COSOL (ASX:COS)
COSOL is a Brisbane based IT services group that leans heavily into AI driven asset lifecycle and enterprise intelligence tools for asset intensive industries. It generates about A$54.9 million from Australian consulting, A$30.7 million from asset management services and A$12.9 million from the Americas, and has a market cap of roughly A$35.5 million.
COSOL provides exposure to AI that is wired into day to day operations, from predictive maintenance to data governance inside large enterprise asset management systems. The stock trades on a low P/S multiple and the company is working to scale AI enabled services. A key consideration is how this effort may affect margins over time.
To see how that trade off looks in detail, review the DCF valuation analysis for COSOL and judge whether COSOL’s AI ambitions already crowd the current share price or not.
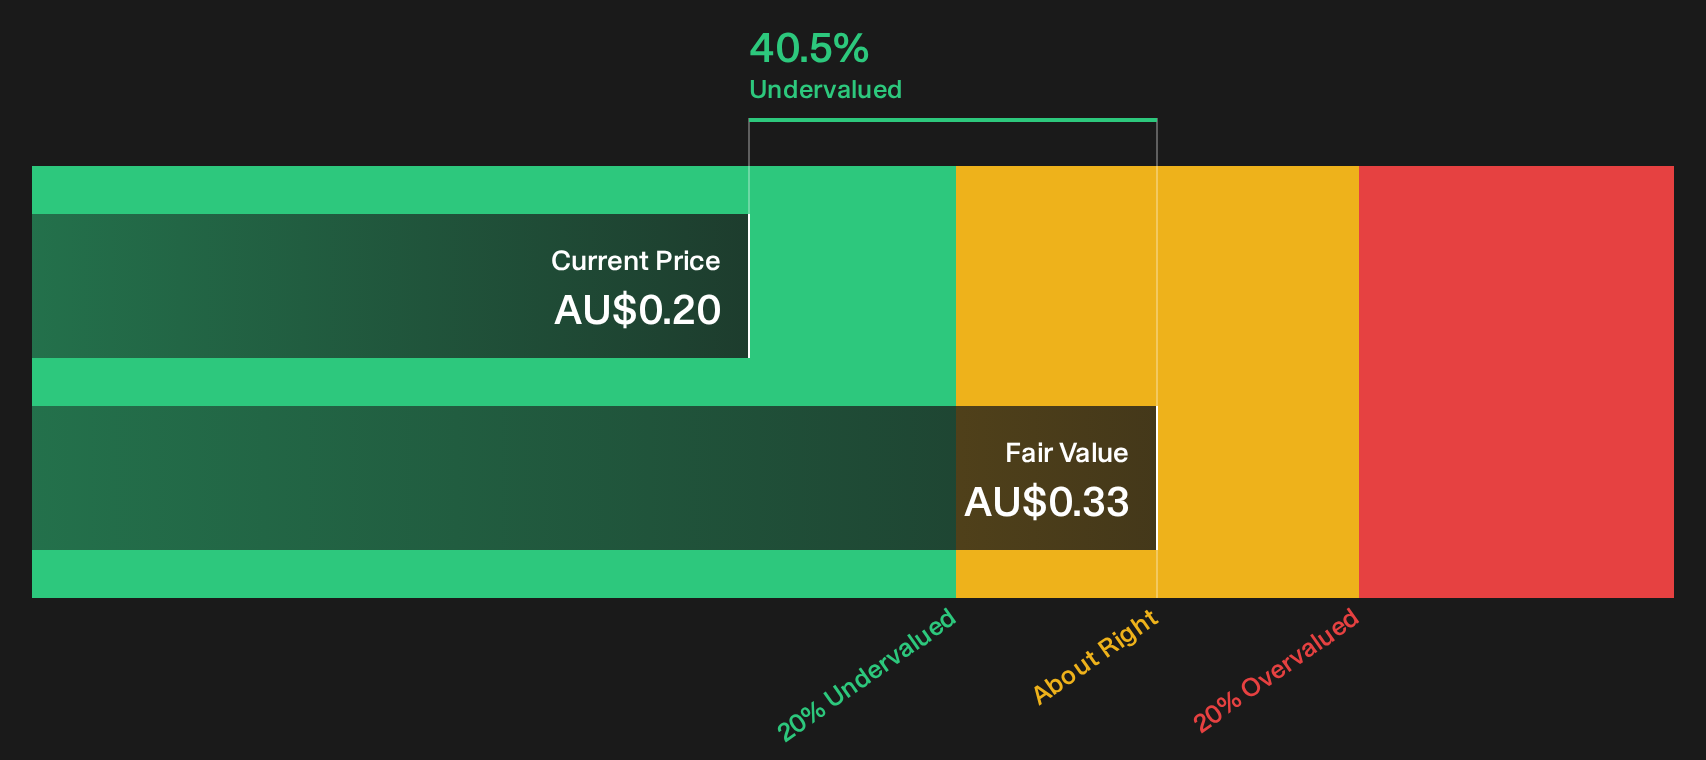
CAR Group (ASX:CAR)
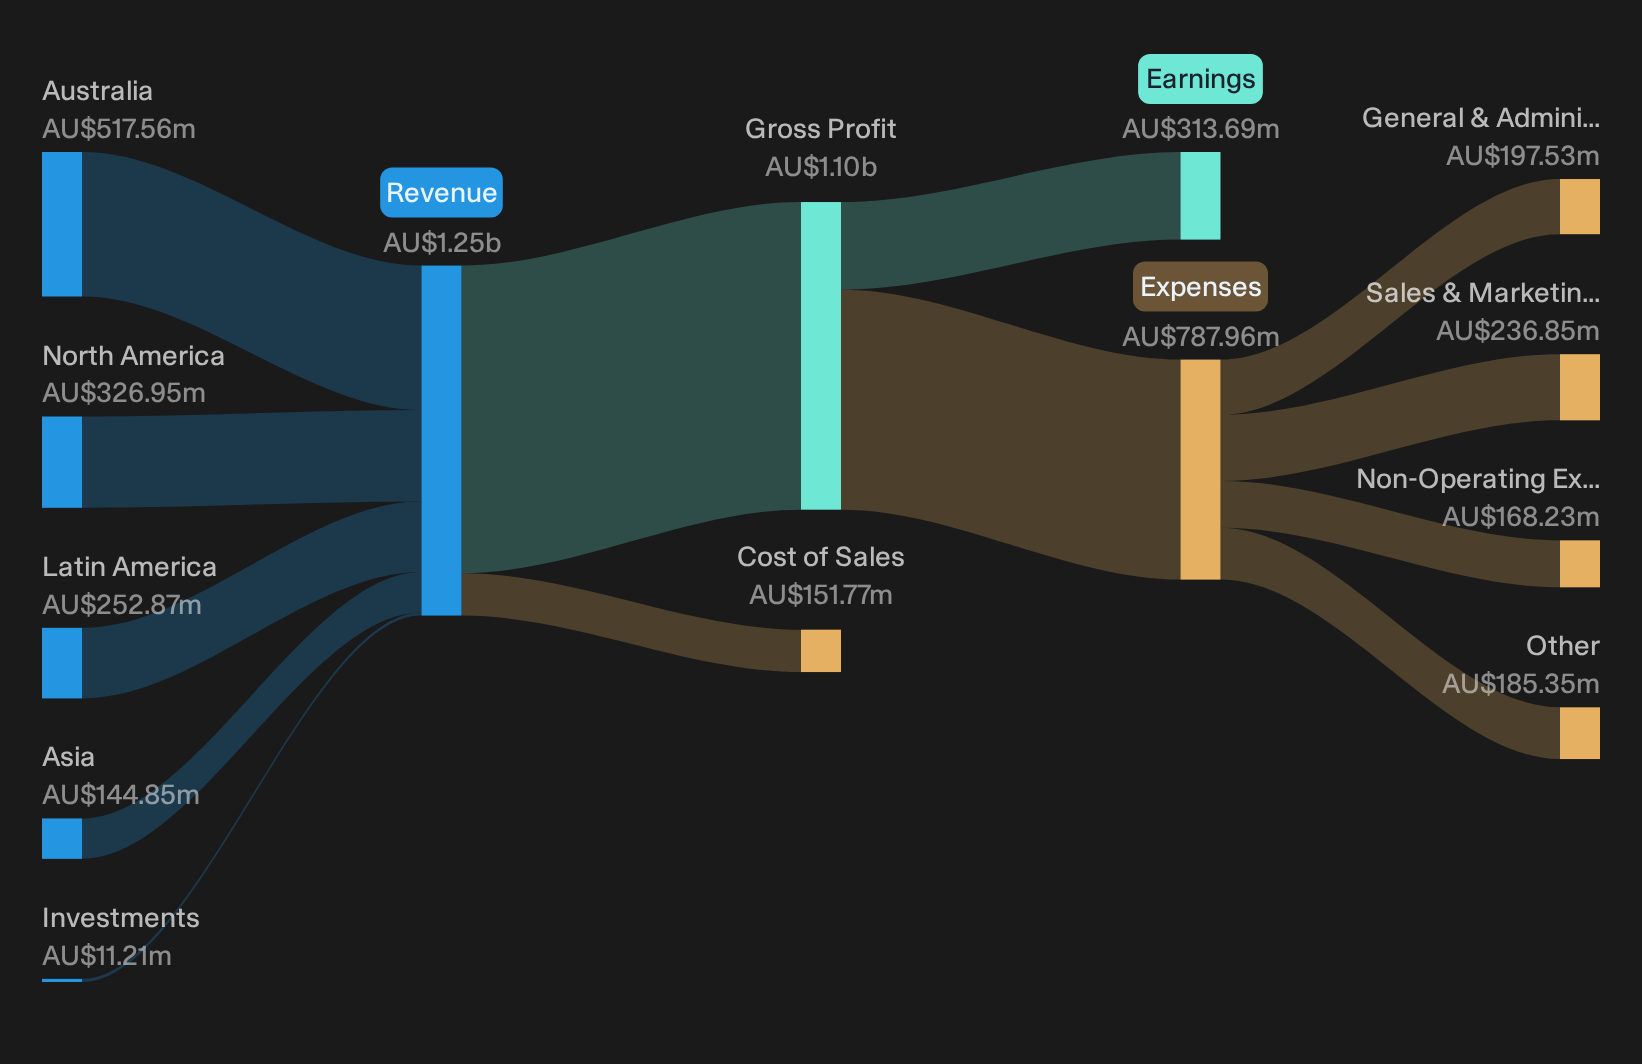
CAR Group runs online vehicle marketplaces around the world and layers on AI driven valuation, inspection, and data products. It generated about A$518 million from Australia, A$327 million from North America, A$253 million from Latin America, A$145 million from Asia, and has a market cap near A$8.2b.
For investors focused on AI infrastructure inside real world marketplaces rather than pure software plays, CAR Group offers a useful case study in how machine learning can shape pricing, recommendations, and advertising yield without relying on a single bet the company project.
"Per-share compounding as Encar / webmotors / US non-auto scale; deleveraging (ND/EBITDA ~2.1x to lower) shifts EV to equity."
Future outcomes depend on how one underappreciated pressure around funding those AI heavy services ultimately feeds through to margins and dividend headroom.
That funding tension is exactly where CAR Group gets interesting, and the full narrative for CAR Group examines how deleveraging, cash generation and AI spending may be decoupling investor expectations.
Ai-Media Technologies (ASX:AIM)
Ai-Media Technologies delivers AI powered captioning, transcription, and translation tools through its LEXI suite, tying directly into the ChatGPT era of automated speech to text and language services. It generated about A$60 million from internet software and services and has a market cap near A$54 million.
For Ai-Media Technologies, the AI story is less about headline grabbing chatbots and more about quietly wiring LEXI into how broadcasters, governments and enterprises handle speech, translation, and compliance at scale.
"The transition from human-in-the-loop services to an AI native workflow with the LEXI suite and encoders is increasing the share of higher margin SaaS in the mix, which directly supports gross margin and EBITDA outcomes."
What really moves the needle for Ai-Media now is how quickly that newer mix reshapes pricing power and long term demand across its customer base.
If that shift in pricing power is what you care about, read the full narrative for Ai-Media Technologies to see whether Ai-Media’s story is accelerating or still overlooked.

Seeking Alternatives Before The Crowd?
Fresh breakouts and under the radar momentum rarely stay quiet for long. Screen faster than the herd, spot quality while it matters, then get in early.
- Chase early moves in quality turnarounds by scanning 16 high quality undiscovered gems that pair resilient balance sheets with pricing that has not yet caught wider attention.
- Track cash rich compounders using the list of solid balance sheet and fundamentals (11 results) so you are focusing on businesses that can fund growth without scrambling for capital when markets tighten.
- Position ahead of potential capital rotations by reviewing 7 resilient stocks with low risk scores that aim to hold up when volatility picks up and sentiment drops.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com