


Eisai (TSE:4523) Wins Two Key Approvals On A Valuation Debate
Eisai (TSE:4523) just picked up two fresh approvals that matter for oncology and neurology investors. The FDA cleared an oral WELIREG plus LENVIMA combo for advanced renal cell carcinoma, while Japan approved the at home LEQEMBI Pen for early Alzheimer’s disease.
Eisai’s recent approvals land against a backdrop of mixed performance, with a strong 90 day share price return of 19.54% and only a 0.30% total shareholder return over one year, so the recent oncology and neurology catalysts come as momentum is rebuilding from a weak multi year record.
Scan other drugmakers riding similar oncology and neurology catalysts by filtering for 10 healthcare AI stocks that could be next in line for meaningful product approvals.
Eisai shares have jumped almost 20% over 90 days, while longer term returns have barely moved. Has the recent rally already captured the oncology and Alzheimer’s news, or does the valuation still leave room for more optimism?
Most Popular Narrative: 10.5% Overvalued
Against Eisai's last close of ¥4,955, the most followed valuation narrative points to a fair value of ¥4,482, suggesting the recent oncology and Alzheimer’s catalysts sit slightly ahead of what the discounted cash flow work supports at a 4.91% rate.
Heavy reliance on a few key drugs, global pricing pressure, regulatory uncertainty, and rising competition threaten Eisai's earnings growth and long-term diversification.
Pipeline productivity and diversification challenges persist, as strong current growth is predominantly driven by the "3Ls" (LEQEMBI, LENVIMA, DAYVIGO); sluggish advancement or setbacks in other therapeutic areas (for example, a slow ramp for Eisai's narcolepsy candidate or heavy competition in oncology/CNS markets) risk stagnating new product launches and constraining long-term profit expansion.
See why 4 investors see Eisai as 11% overvalued.
Result: Fair Value of ¥4,482 (OVERVALUED)
Still, pricing pressure on LEQEMBI and heavy reliance on a small group of drugs leave Eisai exposed if reimbursement outcomes or competitive data move against the company.
Find out about the key risks to this Eisai narrative.
Another View: Eisai Looks Cheap on Cash Flows
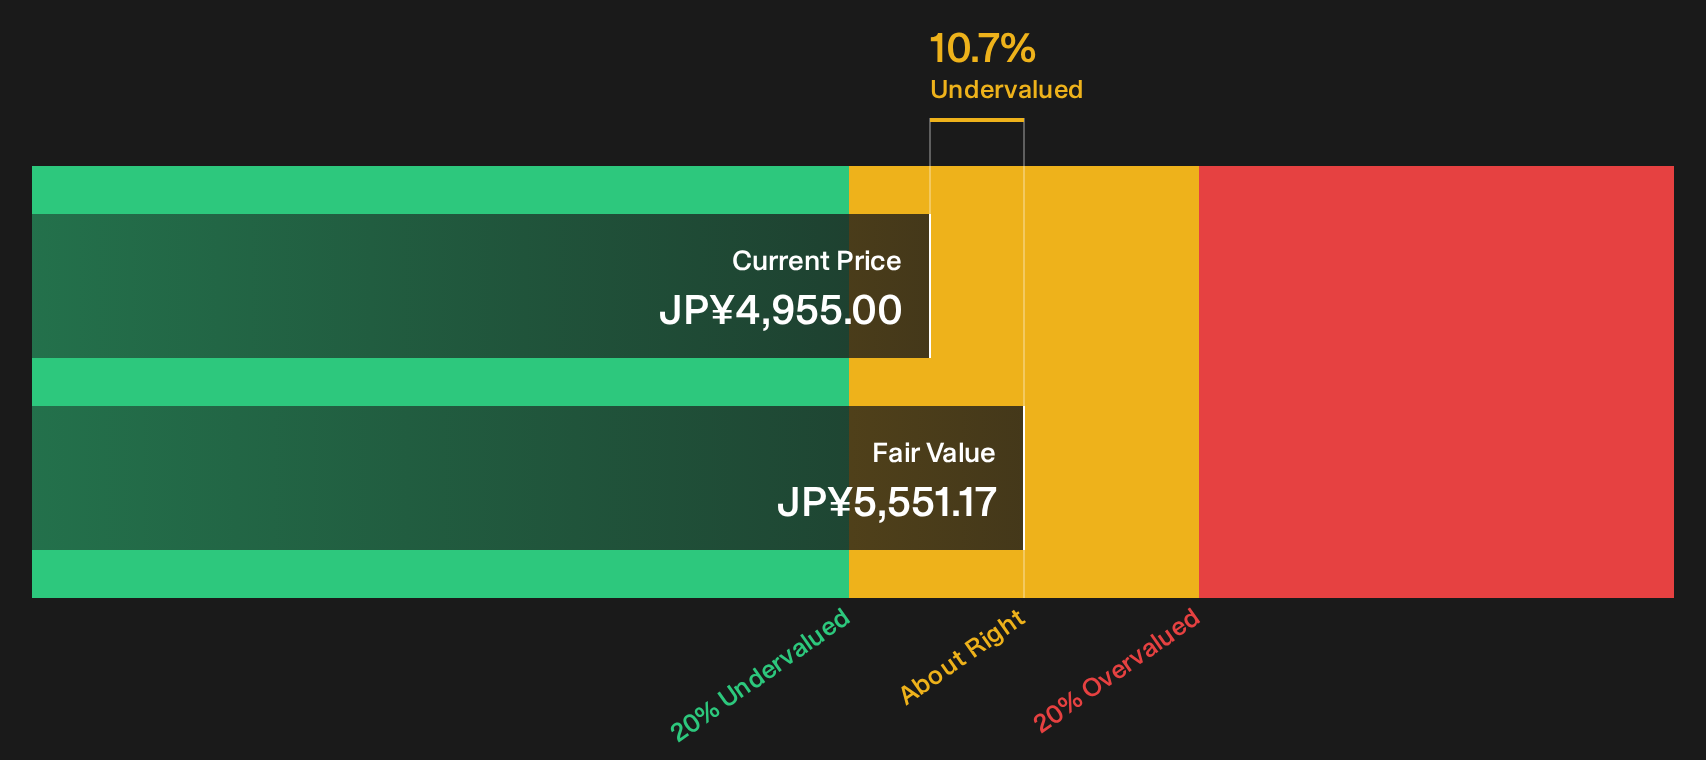
The fair value narrative pegs Eisai at ¥4,482 and calls the stock 10.5% overvalued. A second lens tells a very different story. Our DCF model points to a future cash flow value of ¥5,551.17 per share, with the current ¥4,955 price sitting below that estimate and implying undervaluation.
Two tools, two answers. If analyst targets say one thing and the SWS DCF model says another, which set of assumptions do you trust when you are weighing oncology and Alzheimer’s exposure through Eisai, and which risks matter most to you right now.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Eisai for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Eisai's valuation and risk reward profile. If you want to move fast and frame your own stance, start by weighing the following: 2 key rewards and 1 important warning sign
Looking for more Eisai sized investment ideas?
You have seen how quickly the Eisai story can shift. Do not stop here. Use the same tools to uncover other opportunities before the crowd does.
- Explore potential value by scanning companies that appear mispriced on quality and fundamentals through the 19 high quality undervalued stocks.
- Review a curated set of higher yielding payers using the 14 dividend fortresses.
- Consider dialing down portfolio risk by focusing on resilient businesses with stronger financial footing using the 21 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com