


Did Cost Cuts Just Shift Grifols' (BME:GRF) Investment Narrative?
- Grifols is currently trading at a P/E ratio well below many biotech peers, while working on cost controls, deleveraging, and normalizing operations, which analysts describe as supporting a healthier financial footing.
- The wide gap between Grifols' earnings-based valuation and sector averages is drawing attention to how much of the firm's operational progress is already reflected in its current pricing.
- We will now look at how this focus on disciplined cost management could influence Grifols' broader investment narrative for long term holders.
Compare Grifols' valuation reset with other potential deep value ideas by scanning our hand picked 184 high quality undervalued stocks, which also combine disciplined cost control with solid balance sheets.
Grifols Investment Narrative Recap
For a shareholder in Grifols, the core belief is that demand for plasma derived therapies, together with tighter cost control, can support healthier earnings over time. The recent focus on a low P/E only really matters if operating improvements in plasma collection, pricing discipline, and product mix keep feeding into cash generation.
Right now the key short term swing factor is execution on efficiency and deleveraging, since interest costs are not fully covered by earnings and still constrain flexibility. The main operational risk sits in any disruption or higher expense across plasma centers, or sharper pricing pressure in markets like China that would hit margins.
Recent commentary around disciplined cost management and deleveraging links directly to that risk reward trade off. Grifols carries meaningful debt and interest coverage is described as tight, so any progress in trimming costs, improving margins, or lifting free cash flow can matter quickly for balance sheet resilience.
For you as an investor, the key consideration is how this renewed emphasis on operational discipline interacts with analyst forecasts of potential earnings growth of 21.03% per year. The more the business can turn margin gains into reliable debt reduction, the more room it may have later for R&D, new therapies, and shareholder returns.
Grifols' current earnings are €415.0 million, with analysts forecasting €882.1 million by 2029. This implies an earnings increase of about 2.1x and is based on an assumed 5.6% yearly revenue growth rate to reach about €8.8 billion of sales in the same year.
Discover why Grifols' fair value suggests a 50% potential upside relative to its current price before that discount begins to narrow.
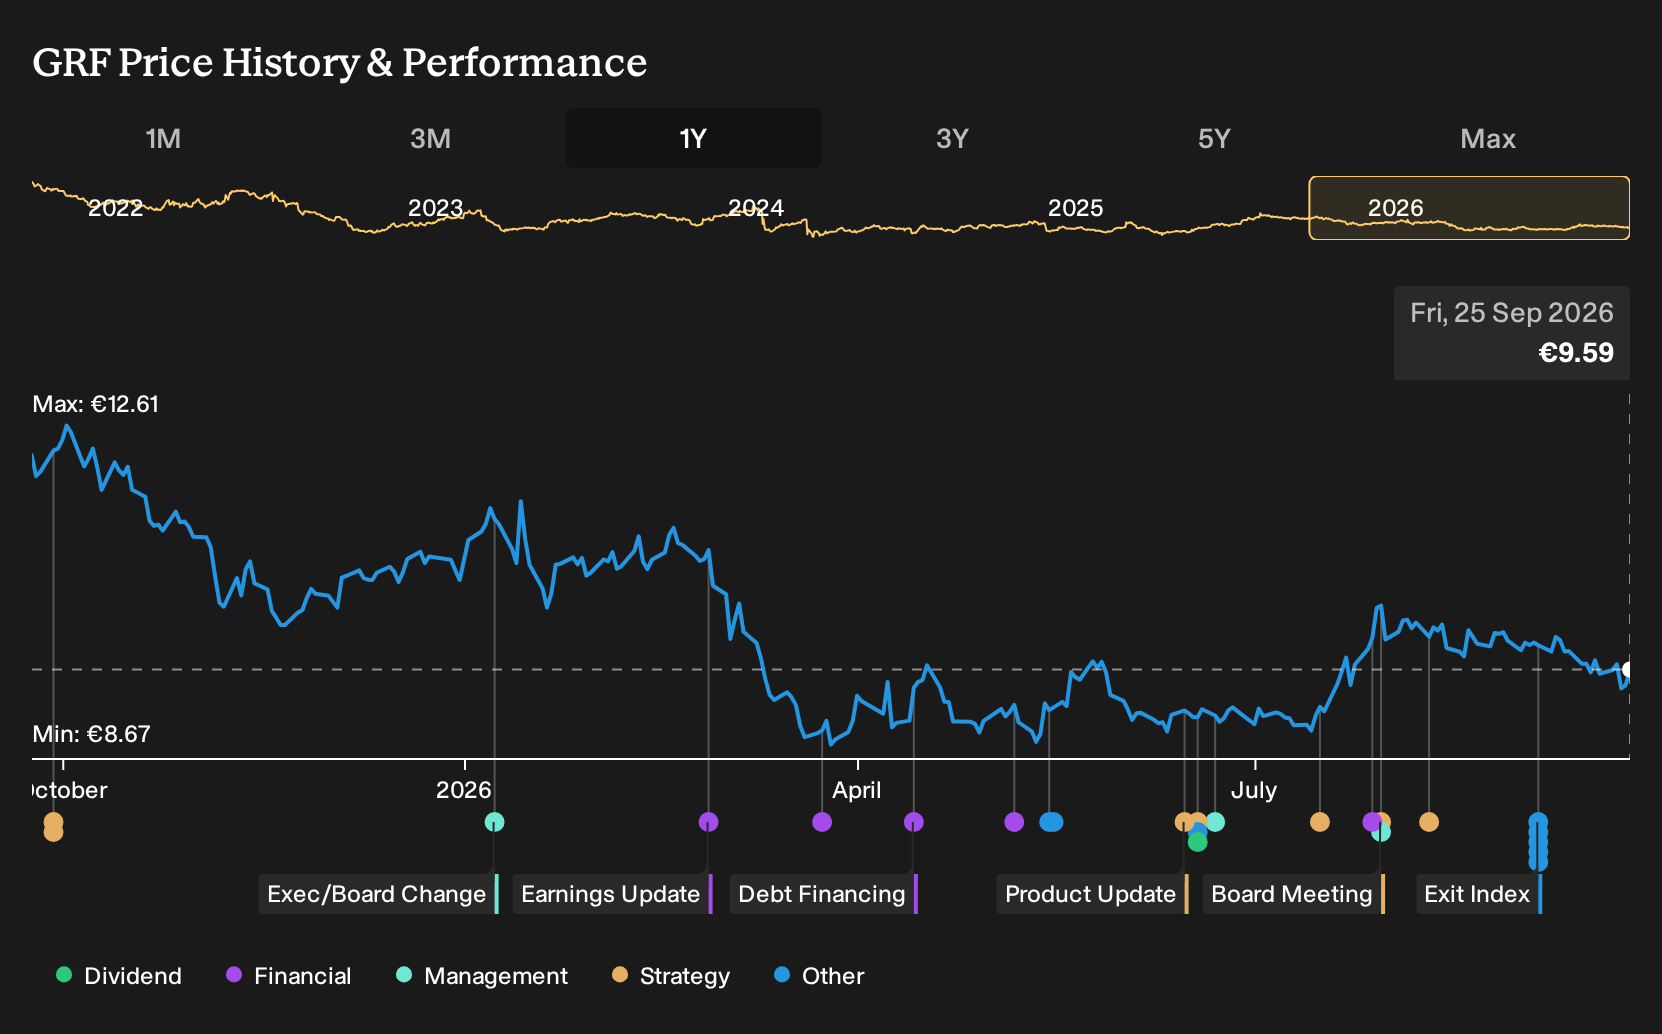
Exploring Other Perspectives
One alternate view on Grifols leans heavily on a revenue catalyst. The most optimistic analysts were modeling about €9.0b of sales and €1.1b of earnings by 2029. That is far above consensus, and those projections were set before this latest news, so you may see those optimistic stories shift as new information lands.
Explore 3 other Grifols fair value estimates, including one that suggests as much as 237% potential upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Grifols research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Grifols. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Grifols' overall financial health at a glance.
Looking For More Ideas Beyond Grifols?
If the Grifols story has sharpened your focus on valuation, balance sheet strength, and risk, it can help to line it up against other potential ideas using the Simply Wall St Screener.
- For investors hunting for mispriced quality, scan a curated pocket of potential deep value opportunities through the 184 high quality undervalued stocks.
- If capital preservation sits high on your list, narrow your search to businesses with stronger financial footing by reviewing the list of solid balance sheet and fundamentals (201 results).
- When income stability matters most, filter for companies offering higher yields with a focus on durability using the 160 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com