


Embedded Systems Growth Might Change The Case For Investing In NXP Semiconductors (NXPI)
- NXP Semiconductors has attracted attention for its cash generation after a discounted cash flow review suggested the current valuation aligns with projected free cash flow, supported by demand in embedded systems across automotive and industrial automation.
- The focus on embedded systems highlights how NXP Semiconductors' positioning in automotive and industrial automation links directly to investor views on its long term cash flow profile.
- We will now look at how NXP Semiconductors' embedded systems driven cash flow outlook could influence the broader investment narrative for the business.
NXP Semiconductors Investment Narrative Recap
Owning NXP Semiconductors means believing its embedded systems focus in automotive, industrial and IoT can keep turning design wins into durable cash generation. The big near term swing factor is how quickly automotive customers rebuild inventories toward NXP Semiconductors' 10 to 12 week target, because that is where visibility and free cash flow confidence can improve.
The key risk sits on the other side of that same coin. A drawn out inventory correction in China or slower auto orders could pressure revenue and keep the recent share price gains fragile. Any large edge AI transaction, such as the mooted Ambarella deal, would add integration and balance sheet execution risk on top.
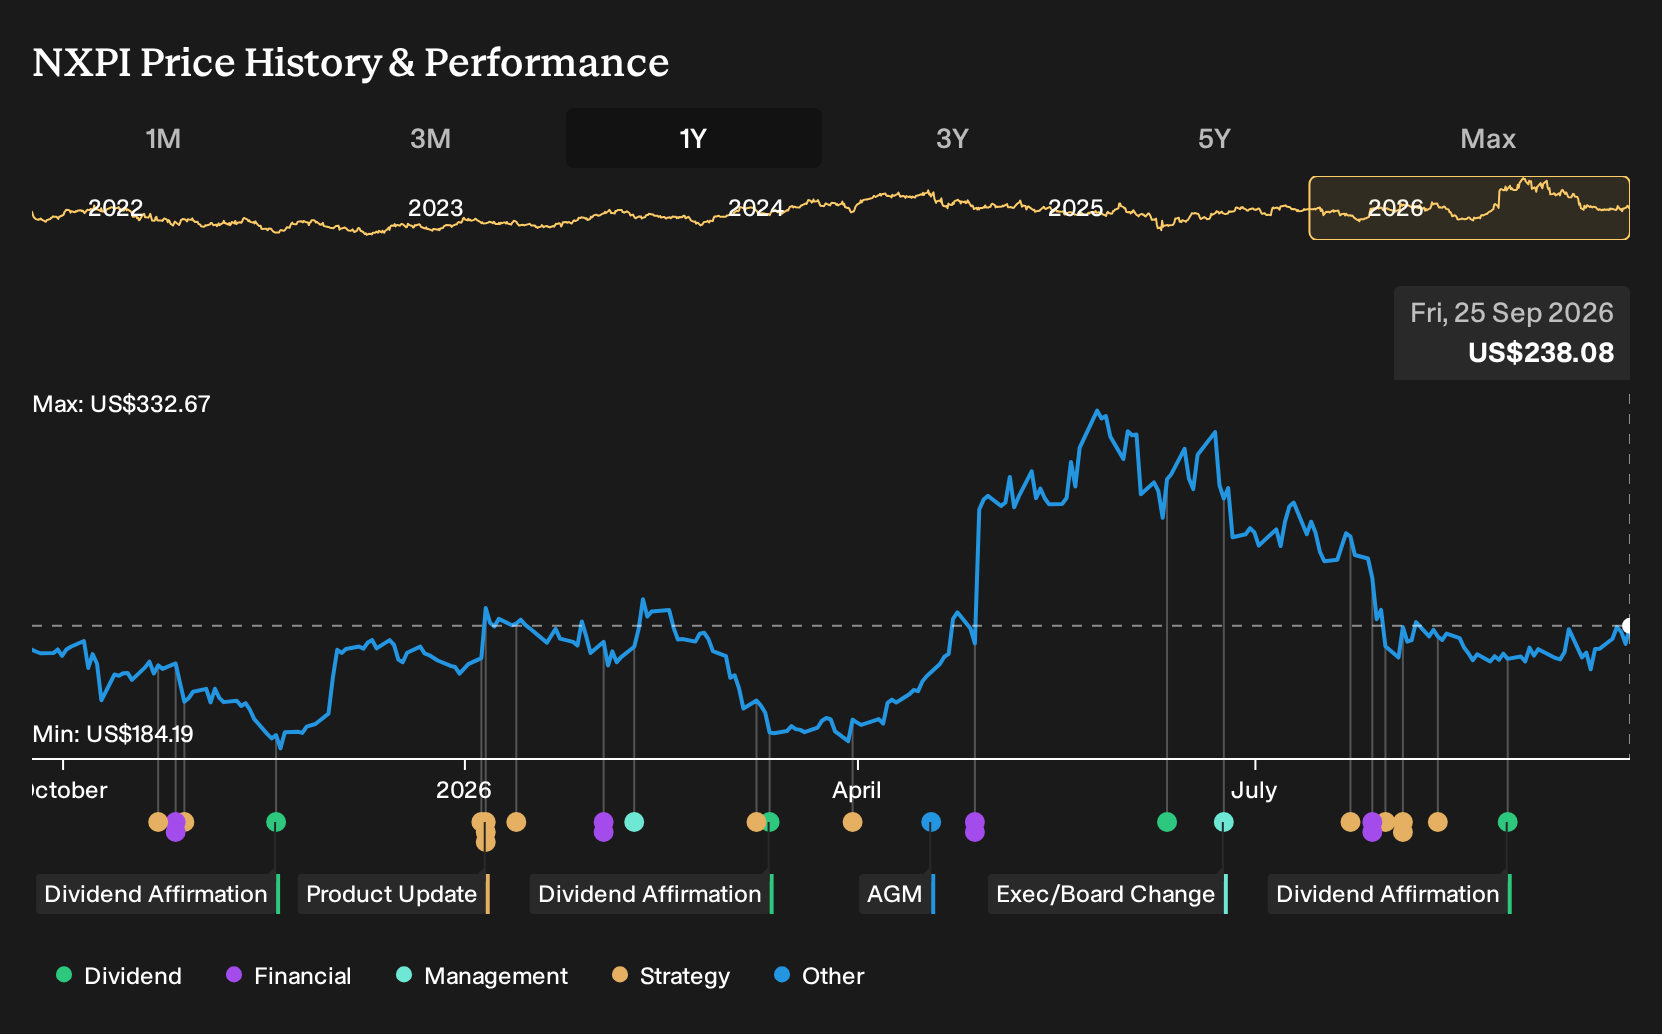
With no fresh company announcements tied directly to this DCF discussion, the most relevant reference point is still NXP Semiconductors' recent quarter with record US$3.5b revenue and solid margins followed by an 18.5% share price drop. That reaction underlined how much weight investors put on Q3 guidance ranges and long dated earnings ambitions rather than backward looking results.
For you as a shareholder, that context matters. The operational catalysts around auto inventory normalisation, industrial and IoT processor uptake and an asset light manufacturing mix remain intact on the company side. Market focus on wide guidance and perceived AI data center exposure adds volatility risk, even when the embedded systems cash flow story appears broadly aligned with current valuation work.
NXP Semiconductors' narrative points to revenues of US$17.6b and earnings of US$4.7b by 2029, based on analysts assuming about 10.2% yearly revenue growth and an earnings increase of roughly US$1.7b from US$3.0b today.
Uncover why NXP Semiconductors' fair value indicates a 31% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on NXP Semiconductors places far more weight on macro risk and the CEO transition. The most cautious analysts were working with revenues of about US$16.4b and earnings of US$4.1b by 2029 before this news, which supports a lower price target and illustrates how sharply opinion can differ. Use this as a prompt to compare several narratives, then decide which assumptions seem most realistic to you.
Explore 5 other NXP Semiconductors fair value estimates, including one that suggests it could be worth just $232.66.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NXP Semiconductors research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NXP Semiconductors. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NXP Semiconductors' overall financial health at a glance.
Looking For More Investment Ideas Beyond NXP Semiconductors?
If the NXP Semiconductors story has sharpened your view on cash generation, balance sheets and long term earnings power, it can help to compare that framework across a wider watchlist. The Simply Wall St Screener offers a quick way to filter the market using the same kind of fundamentals you have just assessed here.
- For investors who want potential upside without ignoring quality and balance sheet strength, scan through 16 high quality undiscovered gems that might not yet be widely followed.
- If capital preservation and steadier profiles matter more to you than rapid gains, focus your search on 30 resilient stocks with low risk scores that screen well on resilience.
- For readers who care about strong finances and clean fundamentals before anything else, build a shortlist using a list of solid balance sheet and fundamentals (24 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com