


3 Indian Value Stocks To Watch In September 2026
Interest rates in the US have moved to a 3.75% to 4% range, which makes borrowing more expensive and puts cash flow under the spotlight for many Indian companies. When money carries a higher price, dependable cash generation can matter more than fast growth stories. This article highlights three Indian stocks that our cash flow focused value screen currently flags as trading below their assessed fair value.
The three stocks below are just a starting sample from this cash flow value idea. The full screen also surfaced 3 more Indian companies with equally compelling stories that are not covered in this article. To identify and analyze those additional opportunities, head straight into the Undervalued Stocks Based On Cash Flows screener.
WPIL (BSE:505872)
Overview: WPIL designs and delivers engineered pumps and pumping systems for water, irrigation and municipal projects, earning recurring service and maintenance cash flows.
Operations: WPIL generates about ₹10,710 million from Pumps and Accessories and ₹9,055 million from project contracts, with revenue weighted toward international markets.
Market Cap: ₹42.0b
WPIL matters for this cash flow focused screener because its core water and irrigation pump projects often come with years of follow-on service work that can keep money coming in long after the initial equipment is installed.
"Rising global focus on water infrastructure, including river linking, wastewater and municipal water projects, is feeding into WPIL's consolidated project and product order backlog of about ₹5,200 crores."
What really shapes the upside for WPIL is how one pressure on future margins and cash conversion ultimately plays out.
That margin question is exactly what the full narrative for WPIL unpacks, showing where cash conversion could accelerate and what might be masking WPIL’s underlying earning power.
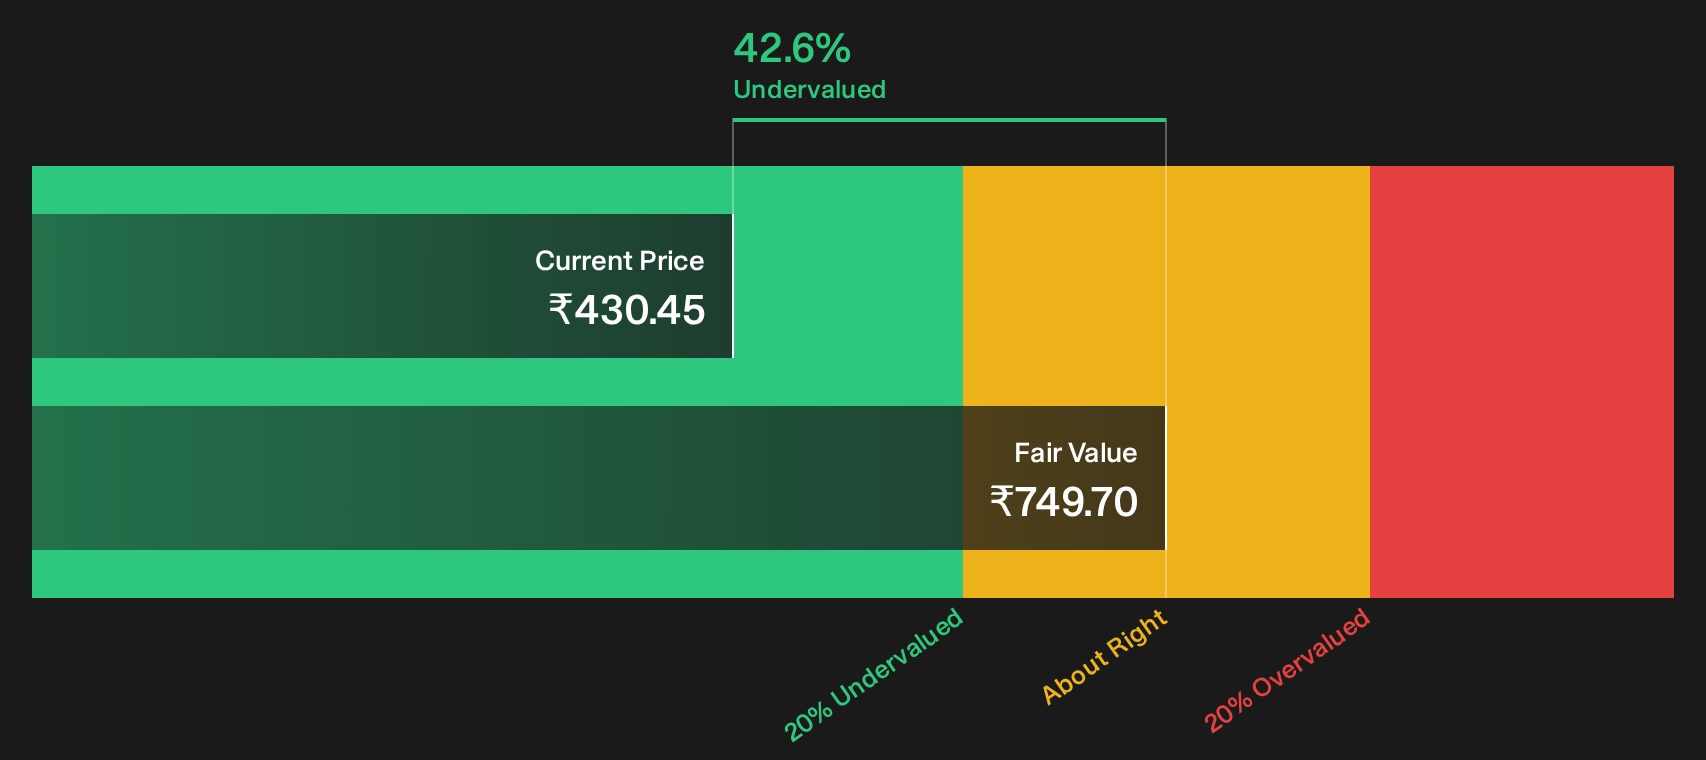
Flair Writing Industries (NSEI:FLAIR)
Overview: Flair Writing Industries manufactures and sells pens, stationery and allied products, creating recurring cash flows from everyday writing and school needs.
Operations: Flair Writing Industries generates about ₹12,808 million in revenue from writing instruments and other allied products across its stationery portfolio.
Market Cap: ₹25.0b
Flair Writing Industries matters for this cash flow focused list because its everyday stationery franchise turns small, frequent purchases into repeatable cash generation.
"Scaling of high growth, higher margin creative and steel bottle and houseware portfolios, which together already contribute about 30% of revenue versus 15% last year, is expected to structurally lift consolidated revenue growth above prior guidance and sustain EBITDA margins near or above 18%."
What really shapes the eventual payoff for Flair Writing Industries is how one pressure on demand and pricing power ultimately plays out.
If that pricing power question is on your mind, the full narrative for Flair Writing Industries maps how cash generation, product mix and valuation could be quietly decoupling from headline stationery demand.

TeamLease Services (NSEI:TEAMLEASE)
Overview: TeamLease Services runs large scale temporary and permanent staffing, payroll and HR solutions that convert workforce demand into recurring cash flows.
Operations: TeamLease Services generates about ₹110.1b from General Staffing, ₹7.0b from Specialised Staffing and ₹2.5b from Other HR Services.
Market Cap: ₹19.7b
TeamLease Services matters for this cash flow focused screen because its staffing and payroll engine turns large, ongoing headcount needs into fee based income that can compound as client volumes grow.
"The rapid growth of apprenticeship adoption, accelerating government skilling initiatives, and TeamLease's unique partnerships with 22 universities position it as the clear national leader in work-integrated learning, paving the way for a new, high-growth, higher-margin revenue stream that is underappreciated in current earnings estimates."
What really decides how powerful that new cash stream becomes is whether one quiet pressure on future profitability ultimately breaks in its favor.
If that profitability pressure is what you care about, the full narrative for TeamLease Services highlights where cash generation could accelerate and which risks might currently be overstated.

Seeking Alternatives Before The Crowd
Fresh ideas move first. Stocks building quiet momentum often break out while most investors are caught watching old stories. Scan what is still under the radar for now and look to get in early.
- Spot cash rich businesses staying resilient while others wobble by running the list of solid balance sheet and fundamentals (201 results) that filters for financial strength and cleaner fundamentals.
- Follow structural themes with companies wiring the future of electricity distribution by tracking the curated 40 power grid technology and infrastructure stocks that focuses on grid technology and infrastructure plays.
- Explore long term income streams from companies screened as 159 dividend fortresses for a list of established payers with strong balance sheets and a history of distributing cash to shareholders.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com