


Asahi Kasei (TSE:3407) Launches Virus Filtration Platform As Fair Value Debate Heats Up
Asahi Kasei (TSE:3407) has drawn fresh attention after two product-focused moves: a new VANTIJ SU-VFC Benchtop virus filtration platform for cell and gene therapy workflows, and ongoing investment in advanced battery separator materials.
Recent enthusiasm around Asahi Kasei’s virus filtration and battery separator efforts comes after a mixed stretch for the shares, with a 1-day share price return of 2.43% lifting the stock to ¥1,645.5, while the 90-day share price return declined 8.28%.
Over a longer horizon, the picture looks more supportive for patient holders. The 1-year total shareholder return of 40.01% and the 3-year total shareholder return of 89.87% suggest these kinds of product updates are being watched closely by the market.
Scan for other material and healthcare stocks pursuing similar themes in virus filtration and energy storage by checking our curated list of 85 AI infrastructure stocks today.
Asahi Kasei appears to be a solid operator in virus filtration and battery materials, yet the recent share move to ¥1,645.5 raises a sharper question. Is this strength still offered at a sensible price?
Most Popular Narrative: 18% Overvalued
Against the last close of ¥1,645.5, the most followed narrative anchors fair value for Asahi Kasei at ¥1,400, implying a valuation that leans ahead of those expectations while recent returns stay strong.
The current valuation implies investors are already paying for Asahi Kasei to successfully scale its battery and semiconductor materials businesses, fully realize expected income from acquisitions like Aicuris, and maintain share price levels after a 59.6% total return over the past year despite the recent 8.8% pullback.
See why 0 investors see Asahi Kasei as 18% overvalued.
Result: Fair Value of ¥1,400 (OVERVALUED)
Still, if Asahi Kasei secures stronger uptake for its battery technologies or turns the Aicuris deal into a meaningful healthcare platform, this bearish narrative could soften.
Find out about the key risks to this Asahi Kasei narrative.
Another View On Asahi Kasei’s Value
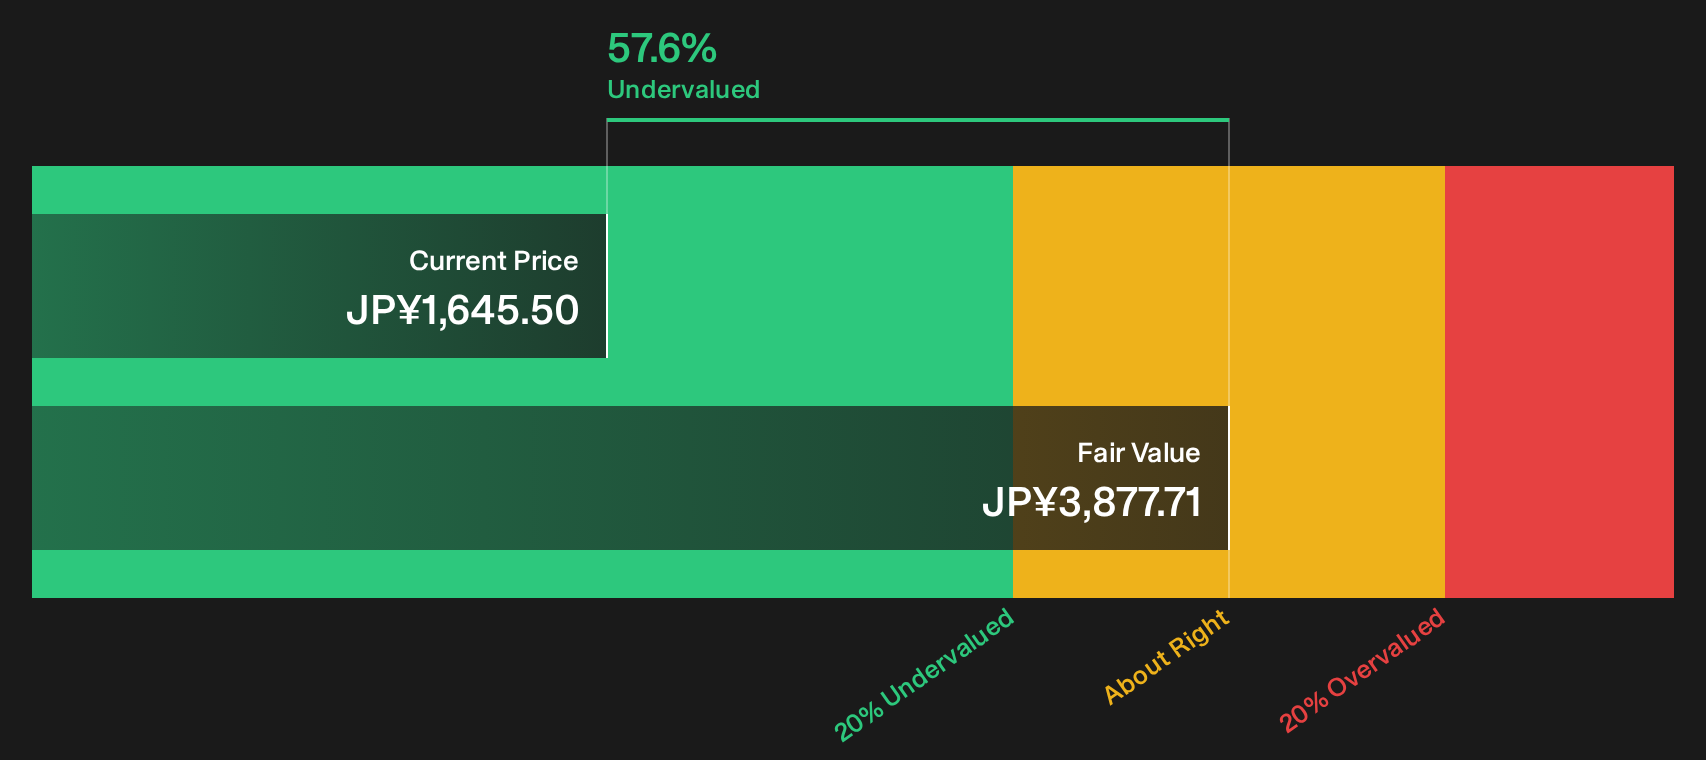
While the most followed narrative pins fair value for Asahi Kasei at ¥1,400 and calls the stock overvalued, the SWS DCF model points in the opposite direction. On that measure, ¥1,645.5 screens as cheap against an estimated future cash flow value of ¥3,877.71. Which lens do you trust more when cash flows and earnings stories disagree?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
After all this mixed sentiment around Asahi Kasei, the next move really sits with you. Move quickly, pull up the data, and weigh the 5 key rewards
Looking for more Asahi Kasei investment ideas?
If Asahi Kasei has sharpened your focus, do not stop here. Broaden your watchlist with targeted stock ideas that fit your risk and return preferences.
- Target resilient balance sheets and steadier fundamentals by scanning our list of solid balance sheet and fundamentals (22 results).
- Hunt for quality businesses that the market may be overlooking with the help of our 74 high quality undiscovered gems.
- Prioritise strong income potential and payment resilience by reviewing our hand picked 14 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com