


Micronics Japan And 2 More Japanese Insider Backed Growth Stocks
Japan has just moved away from ultra cheap money, with the Bank of Japan lifting interest rates to 1.25% for the first time in decades. Higher borrowing costs tend to reward businesses that can fund expansion from their own cash flow and committed insiders rather than constant debt. This article looks at three fast growing Japanese stocks where management has substantial skin in the game and explains why that mix can matter for long term investors.
The three examples below are just a starting sample. The full screen surfaces around 100 more Japanese businesses where growth and insider conviction line up in equally compelling ways that are not covered here.
If you want to identify and analyze those extra high conviction ideas for yourself, head straight into the Fast Growing Stocks With High Insider Ownership screener
Micronics Japan (TSE:6871)
Micronics Japan is a semiconductor test equipment specialist whose probe cards and related tools, at ¥84.9b in revenue versus ¥1.4b from its TE business, anchor its link to fast growing chip manufacturing and testing. The ¥536.2b market cap reflects a sizeable position in this niche.
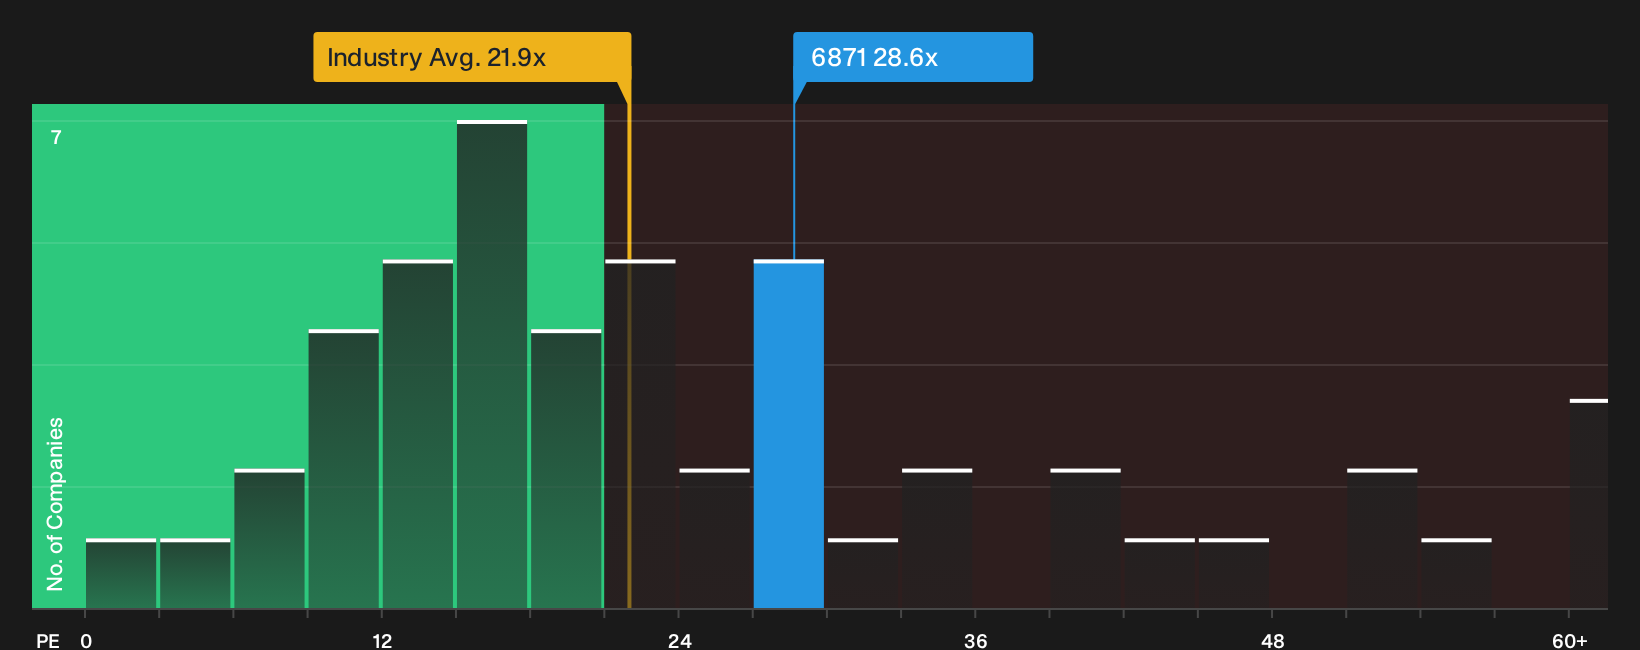
Micronics Japan ties into the fast growing stocks with high insider ownership theme because its main profit engine is probe cards and other test gear used as chipmakers ramp production. Earnings and revenue are forecast to rise, though the premium P/E and share price volatility leave a lot riding on how shifts in demand and pricing develop.
With so much hinging on that rich P/E and demand cycle, review the 2 key rewards and 1 important major warning sign to see what might amplify gains or upset the story.
JX Advanced Metals (TSE:5016)
JX Advanced Metals develops copper and rare metal materials for electronics, recycling and industrial uses. Its Semiconductor Materials arm is directly plugged into chip fabrication through sputtering targets and high purity metals. The group carries a market value of about ¥3,380.3b.
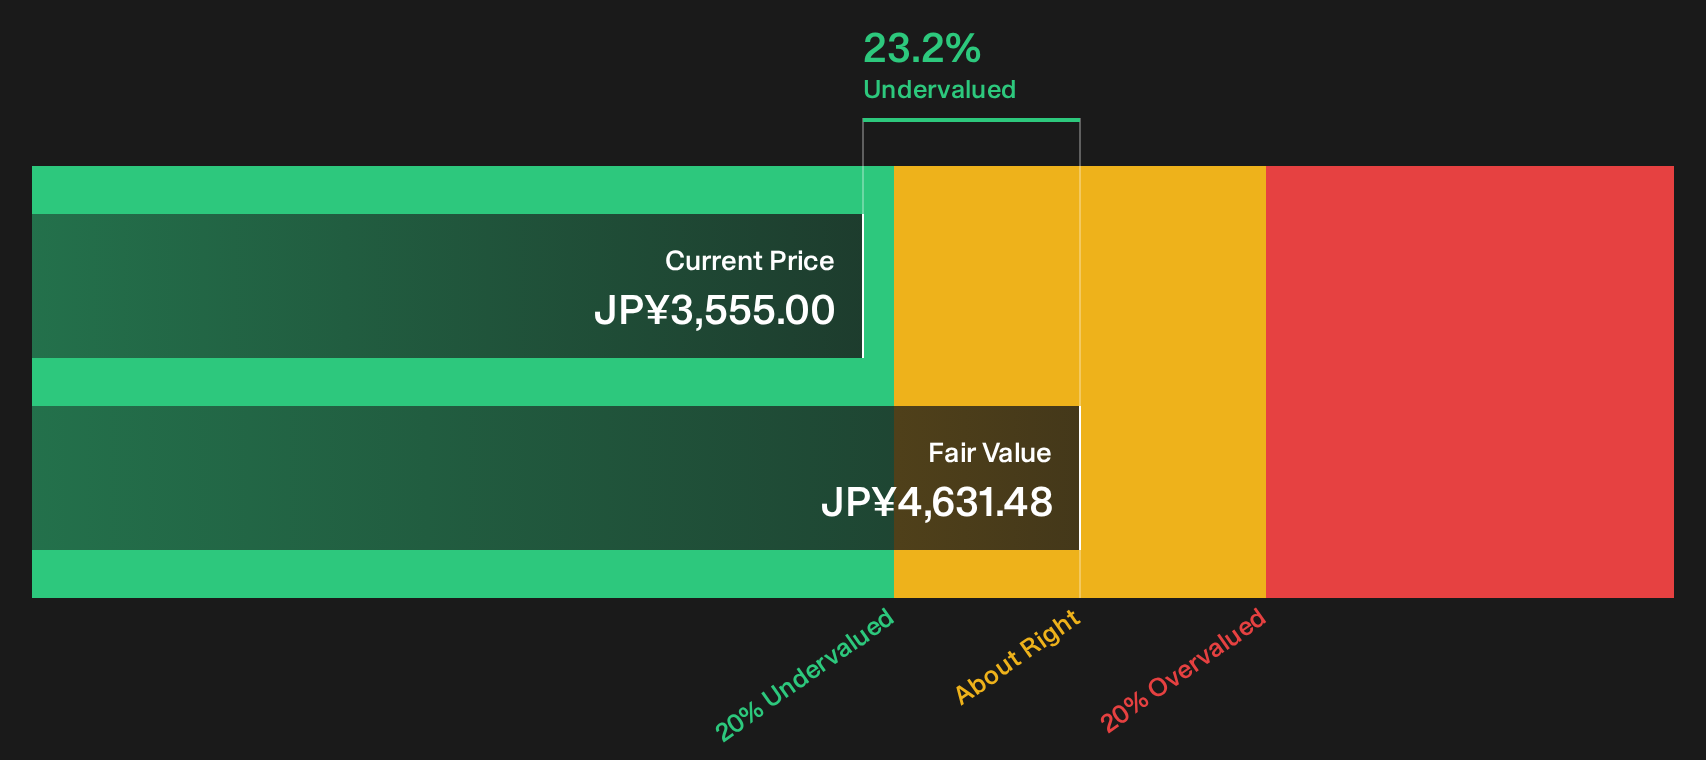
JX Advanced Metals ties closely into this screener because its semiconductor materials are connected to chip and AI data center demand, while earnings recently rose 91.8% and are projected to grow about 13.28% a year. That mix of higher profitability and below estimated fair value could look very different if a single key assumption around demand shifts.
That hinge point is exactly why the fuller 3 key rewards and 1 important major warning sign could flag where JX Advanced Metals’ story accelerates or stalls next.
Rakuten Group (TSE:4755)
Rakuten Group integrates e-commerce, FinTech and mobile services, and its push into cashless payments through Rakuten Pay and Rakuten Card is the clearest fit with this screener’s focus on fast growing, insider-backed financial platforms.
Rakuten Group runs e-commerce platforms, content and mobile services. Its FinTech arm, which includes payments and credit cards, generates about ¥1.1t of revenue alongside ¥1.4t from Internet Services and ¥513b from Mobile, underpinned by a market value near ¥1.5t.
"AI-driven operational efficiencies, targeting a 31% reduction in customer support costs, are anticipated to improve net margins by boosting profitability across Rakuten's operational segments."
What you make of Rakuten Group now largely hinges on how one still unresolved shift in its profitability profile actually plays out.
If that profitability pivot is what you care about, read the full narrative for Rakuten Group to see how Rakuten Group’s ambitions, risks and cash flows could be decoupling.

Seeking Alternatives Before The Crowd
Fresh ideas do not stay under the radar for long. Momentum can change quickly, potential breakouts are often identified rapidly, and attractive entry points may not last. Careful research and preparation are important for investors evaluating new opportunities.
- Identify resilient cash generators early and review the curated list of solid balance sheet and fundamentals (22 results) while conducting your own analysis of valuations and company fundamentals.
- Monitor structural demand in infrastructure and follow the hand-picked 40 power grid technology and infrastructure stocks as part of a broader assessment of the grid upgrade theme.
- Evaluate opportunities in commodities and consider the targeted 36 elite gold producer stocks alongside independent research into business quality and sector conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com