


Somnigroup International (SGI) Draws Fresh Upgrade Interest, Is It Still 29% Undervalued?
Somnigroup International (SGI) is back on investors’ radar after a fresh round of analyst upgrades and higher fair value estimates, prompting a closer look at how recent share gains compare with weaker recent returns.
Recent gains have come after a tough stretch, with Somnigroup International’s share price up 2.63% over the last day but still down 27.94% year to date and 18.17% over three months. However, the 3-year total shareholder return of 51.79% shows that the longer-term story has been far more resilient than the recent pullback implies.
Compare Somnigroup International’s recent pullback with other potential rebound candidates by reviewing our hand picked list of 32 high quality undervalued stocks that pair stronger fundamentals with more attractive pricing.
Somnigroup International has bounced sharply off recent lows, yet the share price is still well below where it started the year. Do you lean into the rebound now, or hold out for a deeper discount as the valuation picture unfolds next?
Most Popular Narrative: 29% Undervalued
Somnigroup International’s most followed valuation storyline puts fair value at $90.56 versus the last close at $63.95, so the gap between price and narrative fair value is wide and clearly defined for anyone weighing the rebound.
The integration of Mattress Firm is already generating meaningful sales and cost synergies, with $100 million in annual net cost synergies projected and sales synergies ahead of schedule. These operational improvements are set to expand EBITDA and enhance net margins moving into 2026 and beyond.
See why 5 investors see Somnigroup International as 29% undervalued.
Result: Fair Value of $90.56 (UNDERVALUED)
Still, the Somnigroup International story can break if weaker bedding demand or tougher digital competition erode margins faster than analysts currently factor in.
Find out about the key risks to this Somnigroup International narrative.
Another View: Somnigroup International Through The P/E Lens
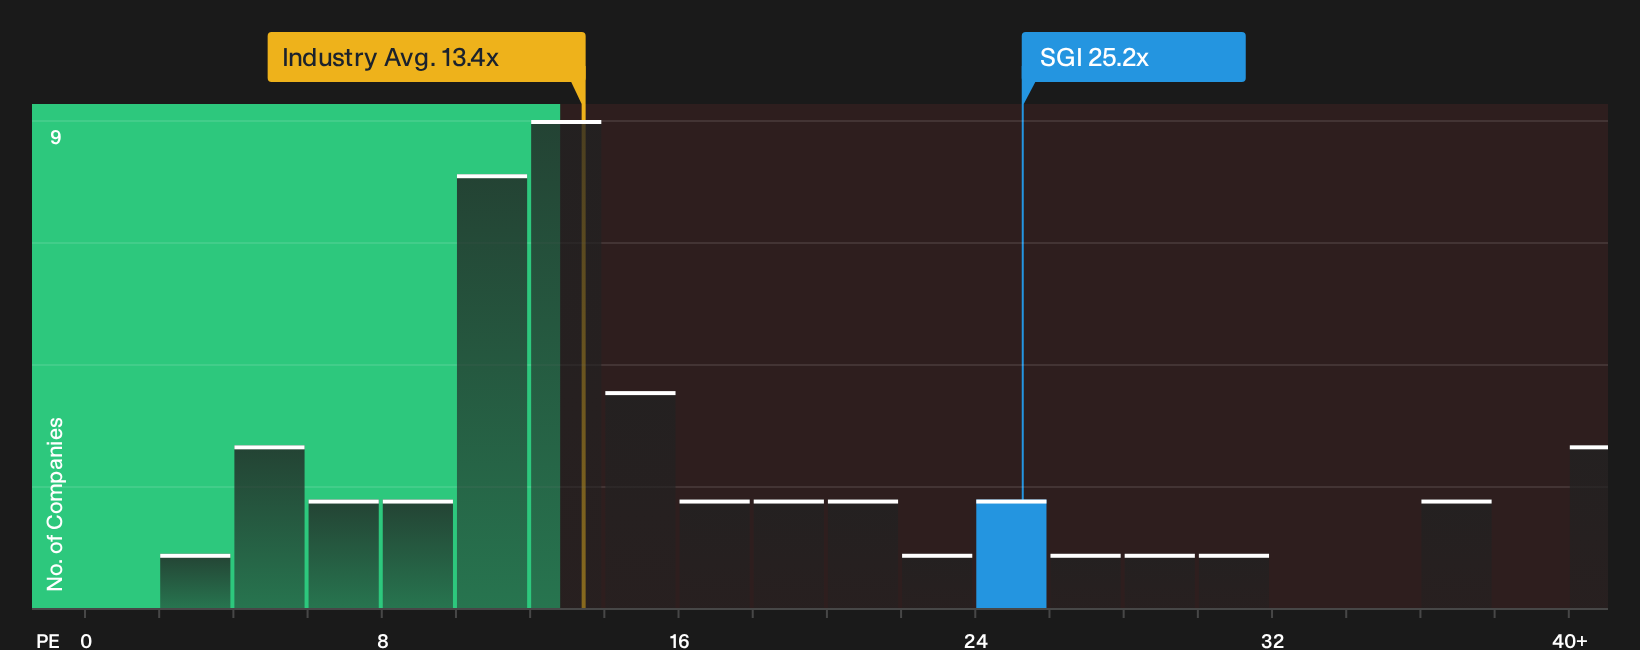
Somnigroup International may screen as undervalued on fair value estimates, yet its current P/E of 25.2x is far richer than the US Consumer Durables average of 13.4x and the peer average of 15.8x, and only slightly below its fair ratio of 25.8x. That mix of apparent discount on one method and premium on another raises a simple question for you as an investor: Are you more focused on upside potential, or on the valuation risk that comes with paying a higher multiple than the broader group?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals on Somnigroup International leave you torn, move quickly to review the full picture for yourself and weigh both sides. Start with the 4 key rewards and 1 important warning sign.
Looking for more Somnigroup International style opportunities?
If Somnigroup International has sharpened your focus on valuation and quality, broaden your watchlist now using targeted stock ideas that match your preferred risk and return profile.
- Zero in on potential mispriced opportunities by scanning a focused set of 16 high quality undiscovered gems that many investors may be overlooking.
- Strengthen your portfolio’s foundation by reviewing a list of solid balance sheet and fundamentals (24 results) that can help you prioritize financial resilience when conditions get tougher.
- Dial back downside risk by filtering for a 30 resilient stocks with low risk scores that highlights companies with more defensive characteristics before the next bout of volatility hits.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com