


ASX Growth Stocks To Watch With Up To 28% Insider Ownership
In the current Australian market landscape, a weaker overnight session in the US has cast a shadow over technology and growth-sensitive sectors on the ASX, though potential stability in miners and energy stocks could offer some relief. Amid these fluctuations, identifying growth companies with significant insider ownership can be appealing as it often signals confidence from those closest to the business.
Top 10 Growth Companies With High Insider Ownership In Australia
| Name | Insider Ownership | Earnings Growth |
| Wisr (ASX:WZR) | 10.3% | 94.2% |
| Starpharma Holdings (ASX:SPL) | 19.3% | 92% |
| SKS Technologies Group (ASX:SKS) | 19.3% | 27.7% |
| Pure One (ASX:P1E) | 11.3% | 78.2% |
| PDI Gold (ASX:PDI) | 10.4% | 64.9% |
| Forrestania Resources (ASX:FRS) | 24.8% | 72.9% |
| Elsight (ASX:ELS) | 12.5% | 58.5% |
| Austral Resources Australia (ASX:AR1) | 24% | 28.2% |
| Adveritas (ASX:AV1) | 17.6% | 99.9% |
| Advanced Engineered Materials (ASX:AEM) | 35.1% | 58.7% |
Let's take a closer look at a couple of our picks from the screened companies.
Beetaloo Energy Australia (ASX:BTL)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Beetaloo Energy Australia Limited, along with its subsidiaries, is involved in the production and sale of oil and natural gas in Australia, with a market capitalization of A$406.81 million.
Operations: Beetaloo Energy Australia Limited generates revenue through its operations in the oil and natural gas sectors within Australia.
Insider Ownership: 14.9%
Beetaloo Energy Australia exhibits strong growth potential with high insider ownership, as insiders have been buying more shares than selling over the past three months. The company is expected to achieve profitability within three years, with revenue projected to grow significantly faster than the market at 103% annually. Despite recent losses of A$8.3 million for the half-year ended June 2026, Beetaloo's inclusion in the S&P Global BMI Index signals positive recognition.
- Click to explore a detailed breakdown of our findings in Beetaloo Energy Australia's earnings growth report.
- Upon reviewing our latest valuation report, Beetaloo Energy Australia's share price might be too optimistic.

Duratec (ASX:DUR)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Duratec Limited, listed as ASX:DUR, provides assessment, protection, remediation, and refurbishment services for steel and concrete infrastructure in Australia with a market cap of A$611.84 million.
Operations: Duratec's revenue segments include Energy (A$91.56 million), Defence (A$157.75 million), Buildings & Facades (A$138.84 million), and Mining & Industrial (A$114.34 million).
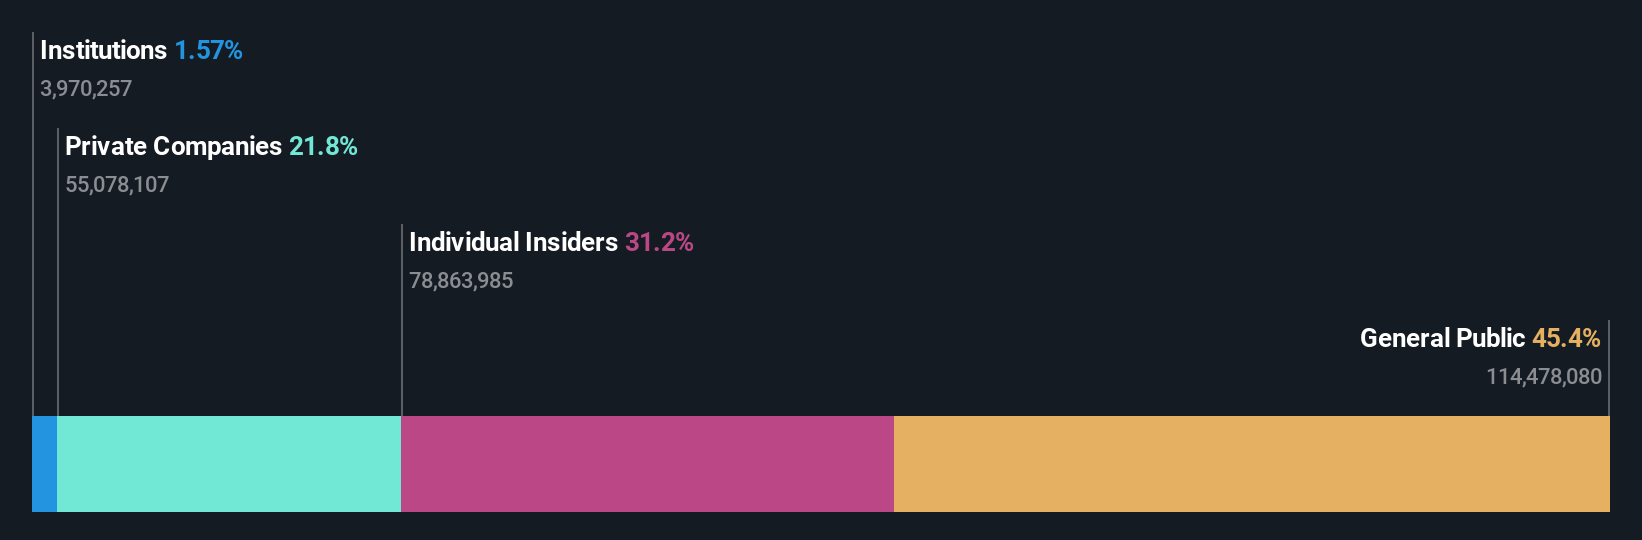
Insider Ownership: 28.0%
Duratec demonstrates growth potential with high insider ownership, despite no substantial insider trading recently. Earnings are forecast to grow 15.4% annually, surpassing the Australian market's 11.3%. Revenue is also expected to outpace the market at 9.6% per year. The company has a robust cash position of A$78.8 million and is actively seeking acquisitions to enhance capabilities and diversify earnings, supported by a strong balance sheet and strategic expansion plans into larger projects.
- Navigate through the intricacies of Duratec with our comprehensive analyst estimates report here.
- According our valuation report, there's an indication that Duratec's share price might be on the expensive side.
HMC Capital (ASX:HMC)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: HMC Capital Limited, along with its subsidiaries, owns and manages real estate-focused funds in Australia and has a market capitalization of approximately A$1.23 billion.
Operations: HMC Capital generates revenue through its various segments, including Digital (A$51.20 million), Real Estate (A$88.60 million), Private Credit (A$40.60 million), Corporate (A$0.20 million), and Private Equity (A$1.30 million).
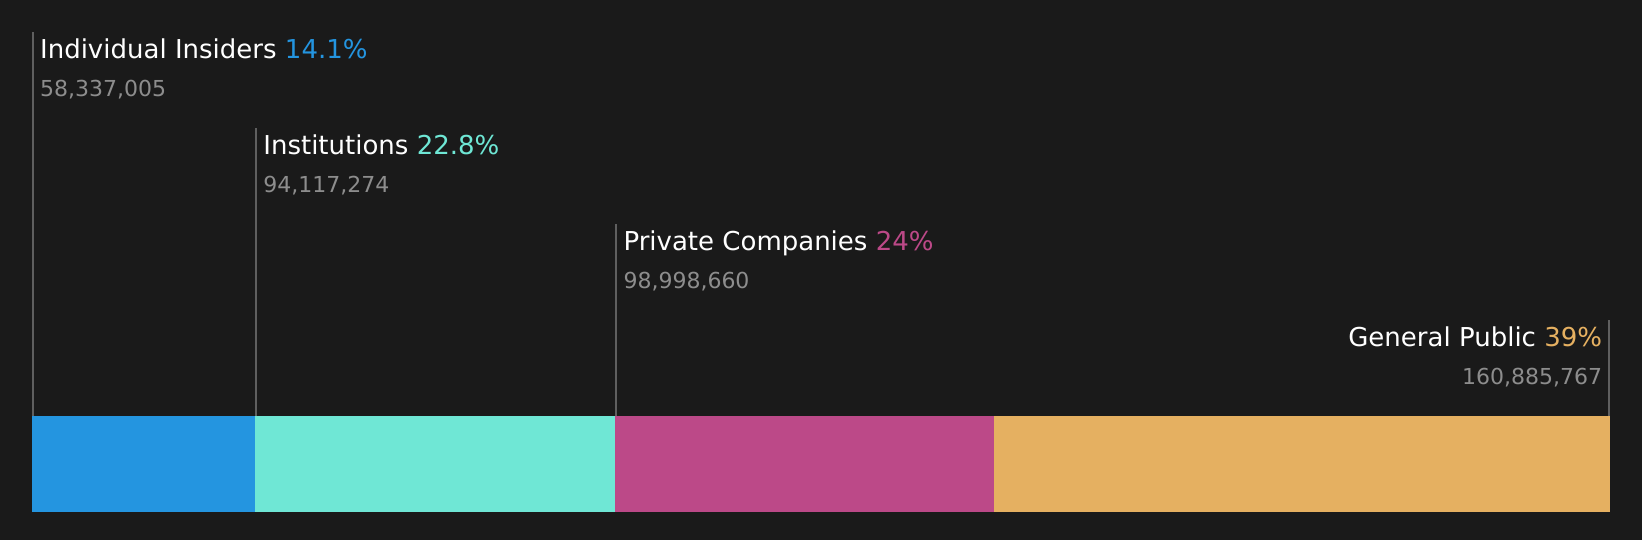
Insider Ownership: 14.1%
HMC Capital, with significant insider ownership, is poised for substantial earnings growth at 23.8% annually, outpacing the Australian market. However, revenue growth is slower at 8.6% per year and below expectations for a high-growth company. Despite trading well below its estimated fair value and planning a 25% dividend increase supported by recurring earnings growth, recent financials show a net loss of A$49.1 million with reduced profit margins compared to last year.
- Get an in-depth perspective on HMC Capital's performance by reading our analyst estimates report here.
- Our expertly prepared valuation report HMC Capital implies its share price may be too high.
Make It Happen
- Embark on your investment journey to our 114 Fast Growing ASX Companies With High Insider Ownership selection here.
- Ready To Venture Into Other Investment Styles? We've found 8 US stocks that are forecast to pay a dividend yeild of over 6% next year. See the full list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com