


Did Dividend Declaration Just Shift Ryman Hospitality Properties (RHP) Investment Narrative?
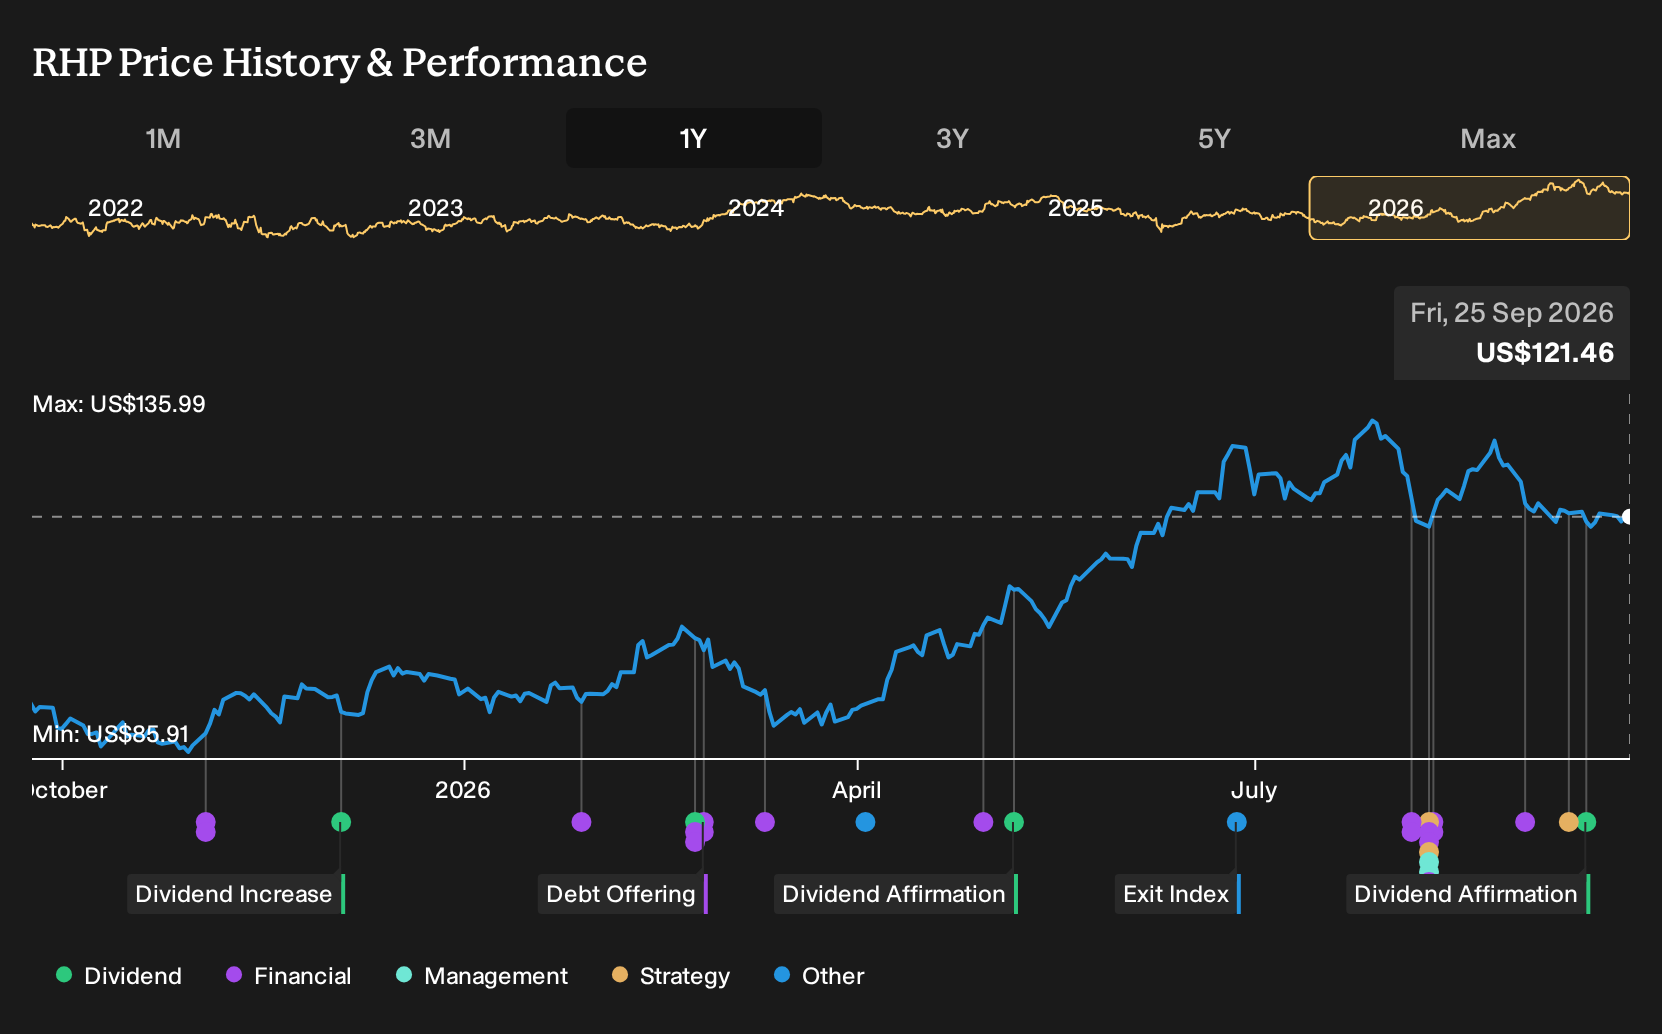
- Ryman Hospitality Properties declared a third quarter cash dividend of $1.20 per share, payable on October 15, 2026, to investors of record on September 30, 2026.
- The size and timing of this payout reflect management’s current cash generation and balance sheet priorities in a capital intensive resort and entertainment portfolio.
- This latest $1.20 dividend declaration also informs the broader investment narrative around the company’s cash flows.
Ryman Hospitality Properties Investment Narrative Recap
Ryman Hospitality Properties asks you to believe that large group travel, conventions and experiential entertainment will keep filling its nearly 14,000 rooms and 3 million square feet of meeting space. The business leans heavily on a concentrated set of markets and high fixed costs, so the real swing factor near term is how consistently group bookings and leisure demand convert into steady cash generation.
The fresh US$1.20 dividend declaration signals confidence in current cash flows, but it does not fundamentally change the near term story. Interest costs still press on coverage, capital needs remain hefty and competition in key destinations can weigh on pricing. Together, these factors keep financing flexibility and dividend sustainability key watchpoints.
The most relevant development is that US$1.20 third quarter dividend. It directly ties into the income narrative, especially given commentary about an unstable dividend record and interest payments that are not well covered by earnings. You are effectively being asked to weigh appealing income against those balance sheet and coverage flags.
For catalysts, the payout sits alongside existing drivers like recent resort acquisitions, group booking strength into 2026 and 2027 and growing entertainment revenue from Opry Entertainment Group. The dividend reinforces that Ryman Hospitality Properties is positioning itself as a cash returning REIT, while execution around debt servicing, labor costs and capital spending remains critical to keeping that income stream attractive.
Ryman Hospitality Properties' narrative projects US$3.7b revenue and US$477.5 million earnings by 2029. This assumes 10.2% yearly revenue growth and an earnings increase of about US$205.6 million from US$271.9 million today.
Uncover why Ryman Hospitality Properties' fair value indicates a 14% potential upside to its current price. This discount could close sooner than income investors expect.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$139 to US$228 per share for Ryman Hospitality Properties, which shows how far apart private investors can be. When you set that against risks around competition, interest costs and capital spending, it encourages you to explore multiple viewpoints before leaning on the dividend story.
Explore another Ryman Hospitality Properties fair value estimate, including one that suggests there could be as much as 88% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ryman Hospitality Properties research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ryman Hospitality Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ryman Hospitality Properties' overall financial health at a glance.
Looking For More Investment Ideas Beyond Ryman Hospitality Properties?
If Ryman Hospitality Properties has sharpened your income lens but you want a broader watchlist, use the Simply Wall St Screener to line up other stocks that match your preferred mix of dividends, balance sheet strength and upside potential.
- For investors who want income without ignoring quality, consider a curated set of high yielding payers by reviewing 8 dividend fortresses.
- If capital preservation sits high on your list, you could focus on financially resilient companies through the 30 resilient stocks with low risk scores.
- When you want to spot potential future leaders before they are widely followed, you can scan the market using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com