


Brookfield Infrastructure Partners (BIP) Tests Its AI Power Narrative After A Sharp Pullback
Brookfield Infrastructure Partners (NYSE:BIP) has drawn fresh attention after recent trading left the units down about 9% over the past month and roughly 5% over the past 3 months, despite a positive 1-year total return.
Recent trading suggests momentum is fading for Brookfield Infrastructure Partners, with the 7-day share price return down 3.63% and the 30-day share price return down 8.77%. At the same time, the 1-year total shareholder return of 10% and 3-year total shareholder return of 37.96% point to a stronger long-term record and shifting views on both its growth potential and risk profile.
Scan for other infrastructure focused opportunities showing mixed momentum, similar to Brookfield Infrastructure Partners, by lining up the 40 power grid technology and infrastructure stocks against its recent performance.
The recent pullback leaves Brookfield Infrastructure Partners trading well below a wide band of value estimates, from its analyst target to intrinsic models. Is that gap a warning sign or a genuine pricing opportunity?
Most Popular Narrative: 26% Undervalued
Brookfield Infrastructure Partners last closed at $34.76, while the most popular narrative places fair value nearer to $47.10. This frames today’s weakness against a much higher long term cash flow outlook built on AI focused data and power assets.
A high proportion of inflation linked and regulated or contracted cash flows in utilities, transport and midstream, which has supported FFO growth alongside 6 to 9% organic expansion and a 6% increase in the 2026 distribution, provides a base for future earnings and margin resilience even as new AI projects are added.
See why 36 investors see Brookfield Infrastructure Partners as 26% undervalued.
Result: Fair Value of $47.10 (UNDERVALUED)
Still, the bullish Brookfield Infrastructure Partners narrative can be knocked off course if AI data center projects face tighter permitting or if behind-the-meter power margins disappoint.
Find out about the key risks to this Brookfield Infrastructure Partners narrative.
Another View: Brookfield Infrastructure Partners Looks Expensive On Earnings
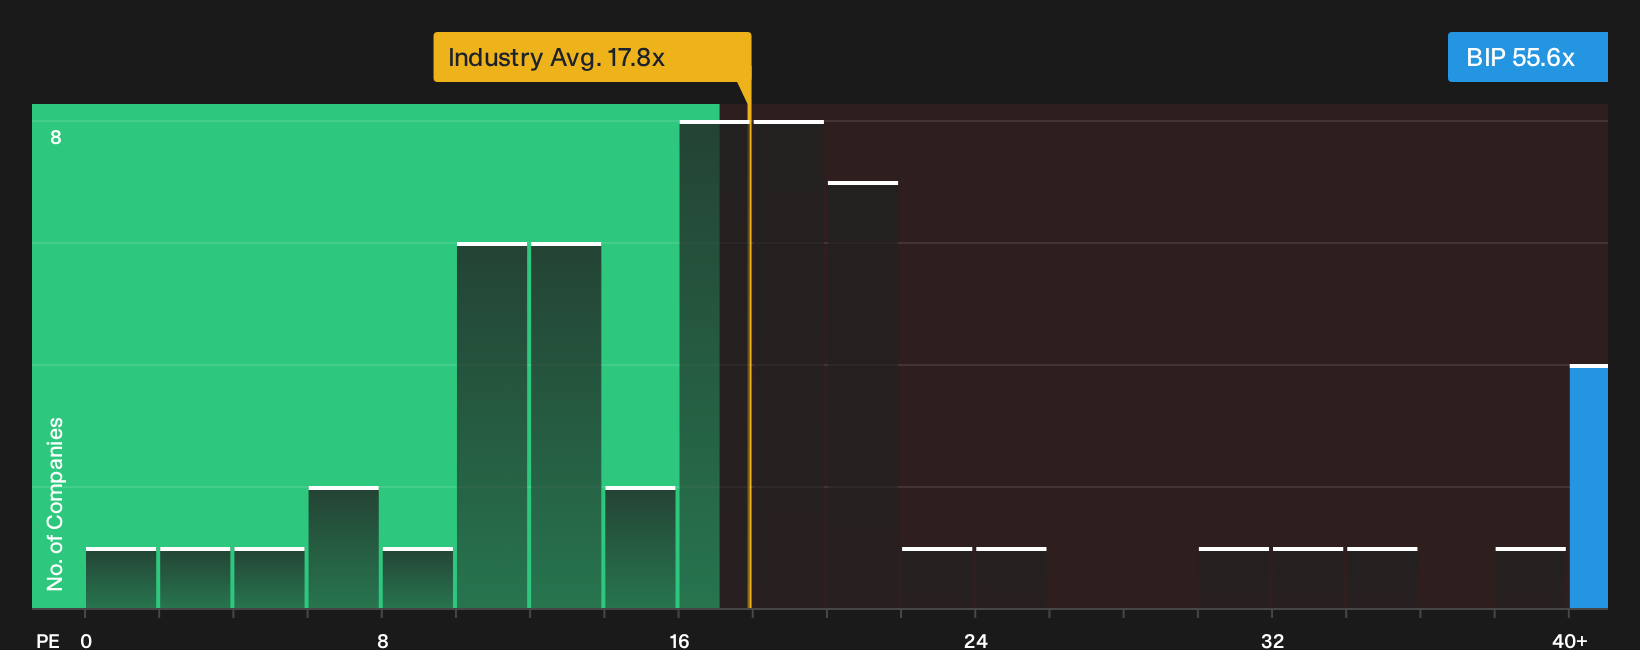
The cash flow story around Brookfield Infrastructure Partners is one thing. On earnings, it is very different. The units trade on a P/E of 55.6x, compared with about 17.8x for the global integrated utilities group and a peer average near 20.3x.
The fair ratio sits far lower at 2.4x, which signals a wide gap between current pricing and where the multiple could move if sentiment cools or earnings forecasts reset. Is that gap a source of opportunity, or a reminder that expectations already carry plenty of valuation risk?
See what the numbers say about this price in more detail by checking the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Brookfield Infrastructure Partners can feel confusing, so move quickly from sentiment to substance by weighing the 3 key rewards and 3 important warning signs against your own read of the numbers.
Looking for more Brookfield Infrastructure Partners style investment ideas?
If Brookfield Infrastructure Partners has sharpened your focus on risk, income and value, do not stop here. Use the Simply Wall Street Screener to uncover fresh opportunities aligned with your goals.
- Target resilient cash generators by scanning our list of solid balance sheet and fundamentals (24 results) that pair sturdy finances with business models built to handle shocks.
- Hunt for mispriced potential using the 16 high quality undiscovered gems and spot quality companies that fewer investors are watching.
- Prioritise steadier ride potential by checking 30 resilient stocks with low risk scores before the crowd prices in their lower volatility profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com