


3 Canadian Stocks With Up To 44% Fair Value Upside
The Federal Reserve’s push toward higher for longer interest rates has pulled attention toward U.S. Treasuries and cash-like yields, which leaves many Canadian stocks quietly repriced on fear rather than fundamentals. That is where companies generating solid cash flows yet priced below estimated fair value can matter. This article walks through three Canadian stocks flagged by our cash flow discount screener that appear mispriced when viewed through this metric-heavy lens.
The stocks highlighted below are only a starter set from this idea, while the full screen surfaced 2 more businesses with equally compelling cash flow stories that are not covered here. To identify and analyze your own highest conviction opportunities from this theme, head straight into the Undervalued Stocks Based On Cash Flows screener.
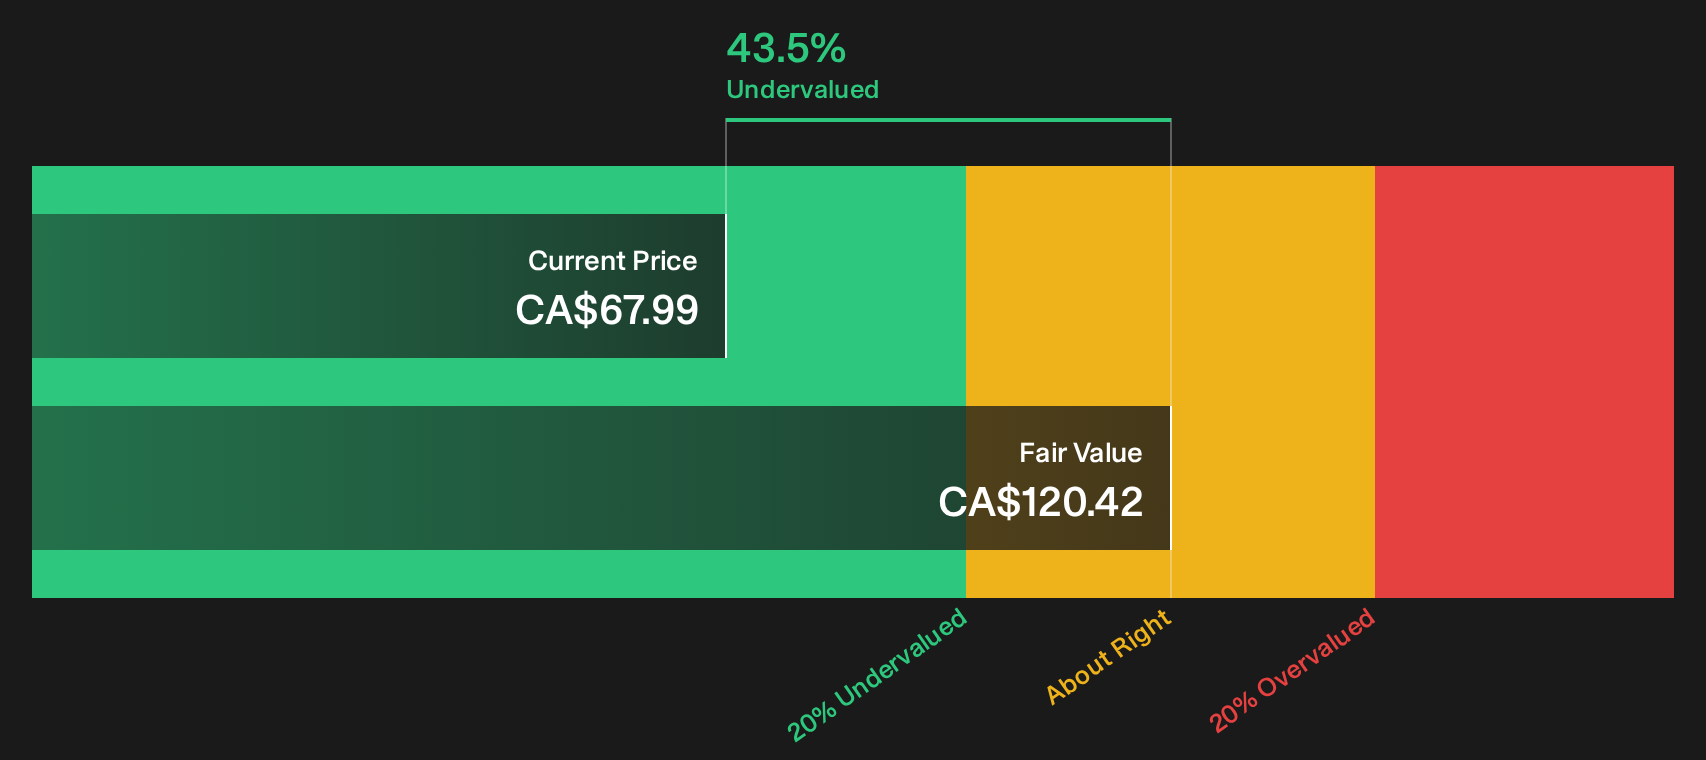
Pan American Silver (TSX:PAAS)
Pan American Silver is a precious metals producer across the Americas, with cash flows anchored in silver and gold output that feeds directly into discounted cash flow estimates used for this screener’s value signal.
Pan American Silver runs silver mines like La Colorada and Cerro Moro alongside gold operations such as Jacobina, El Peñon and Timmins. Revenue is spread across assets that each contribute hundreds of millions of dollars in annual sales and support a market value of about CA$28.4b.
"Integration of Juanicipio, with its low cash costs and contribution to attributable silver production and income, refines the cost base and can support higher segment margins and free cash flow generation."
The real swing factor is how one large growth project reshapes future cash generation if its development and cost profile track current plans.
That turning point is exactly where the full narrative for Pan American Silver picks up, mapping how project execution, metal prices and capital allocation could reshape the Pan American Silver investment case.
OceanaGold (TSX:OGC)
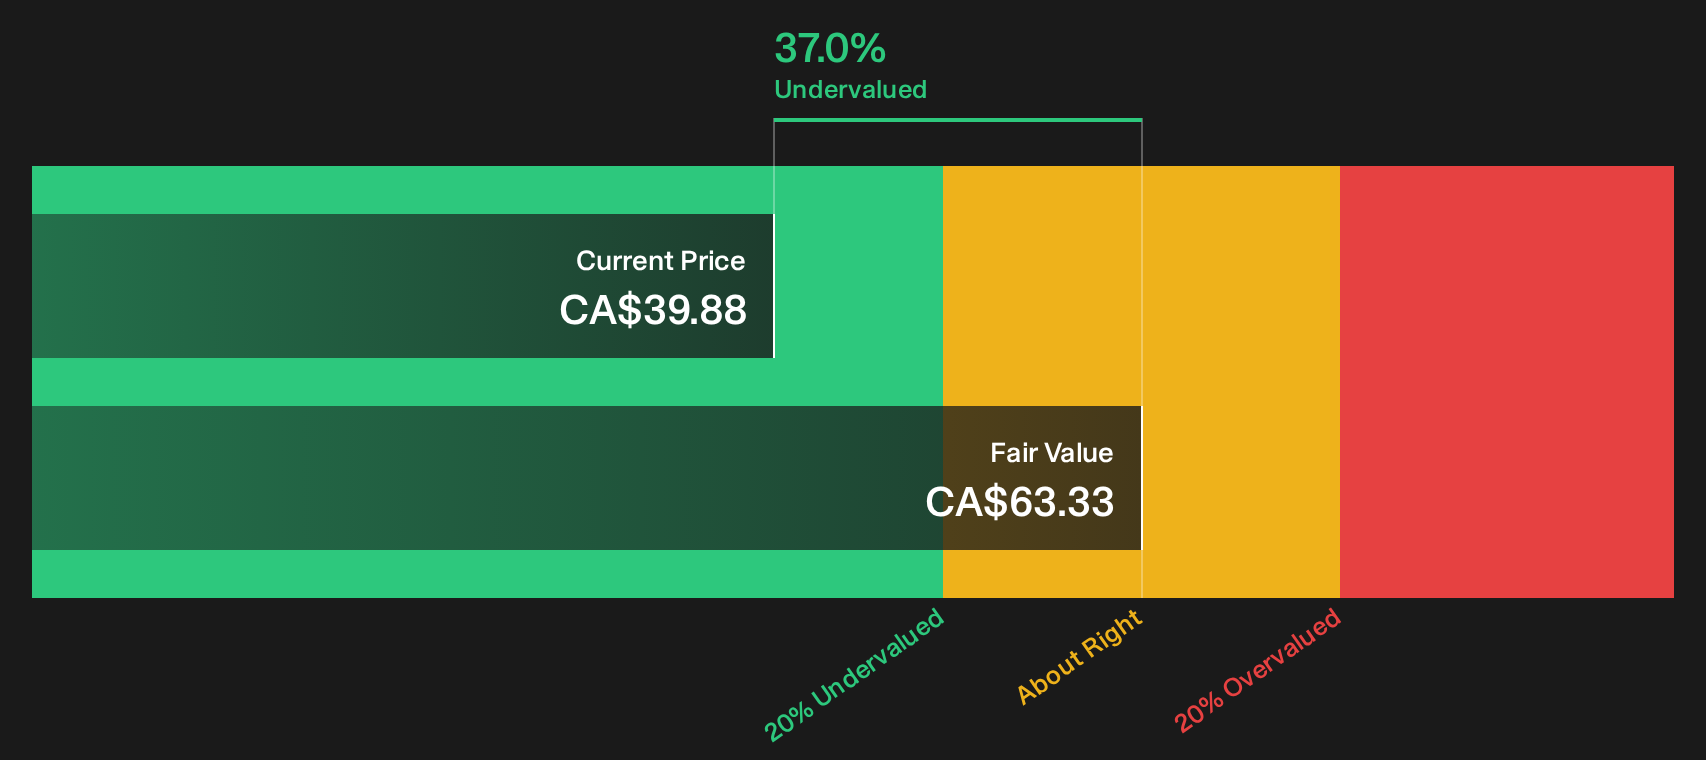
OceanaGold is a Vancouver based gold and copper producer whose cash flow story is built on producing mines that feed directly into discounted cash flow valuation work.
Across its Haile, Macraes, Didipio and Waihi operations, OceanaGold generates revenue of about $796 million, $781 million, $549 million and $338 million respectively, supporting a market value near CA$8.9b.
For value focused investors, OceanaGold matters because its portfolio of long life mines provides the cash flows used to judge whether the current share price fairly reflects that production profile.
"Optimization and expansion at Didipio, including restoration of normal underground rates and a targeted 2.5 million tonne annual mining rate by 2026, should increase copper and gold output from an already low cost asset, enhancing consolidated cash flow and margins."
This raises the question of what happens if one key assumption about how efficiently those future ounces translate into earnings and buybacks shifts even slightly.
If that efficiency story is what matters most, the full narrative for OceanaGold explains where OceanaGold’s cash flows could be accelerating, stalling, or quietly masking upside.
Suncor Energy (TSX:SU)
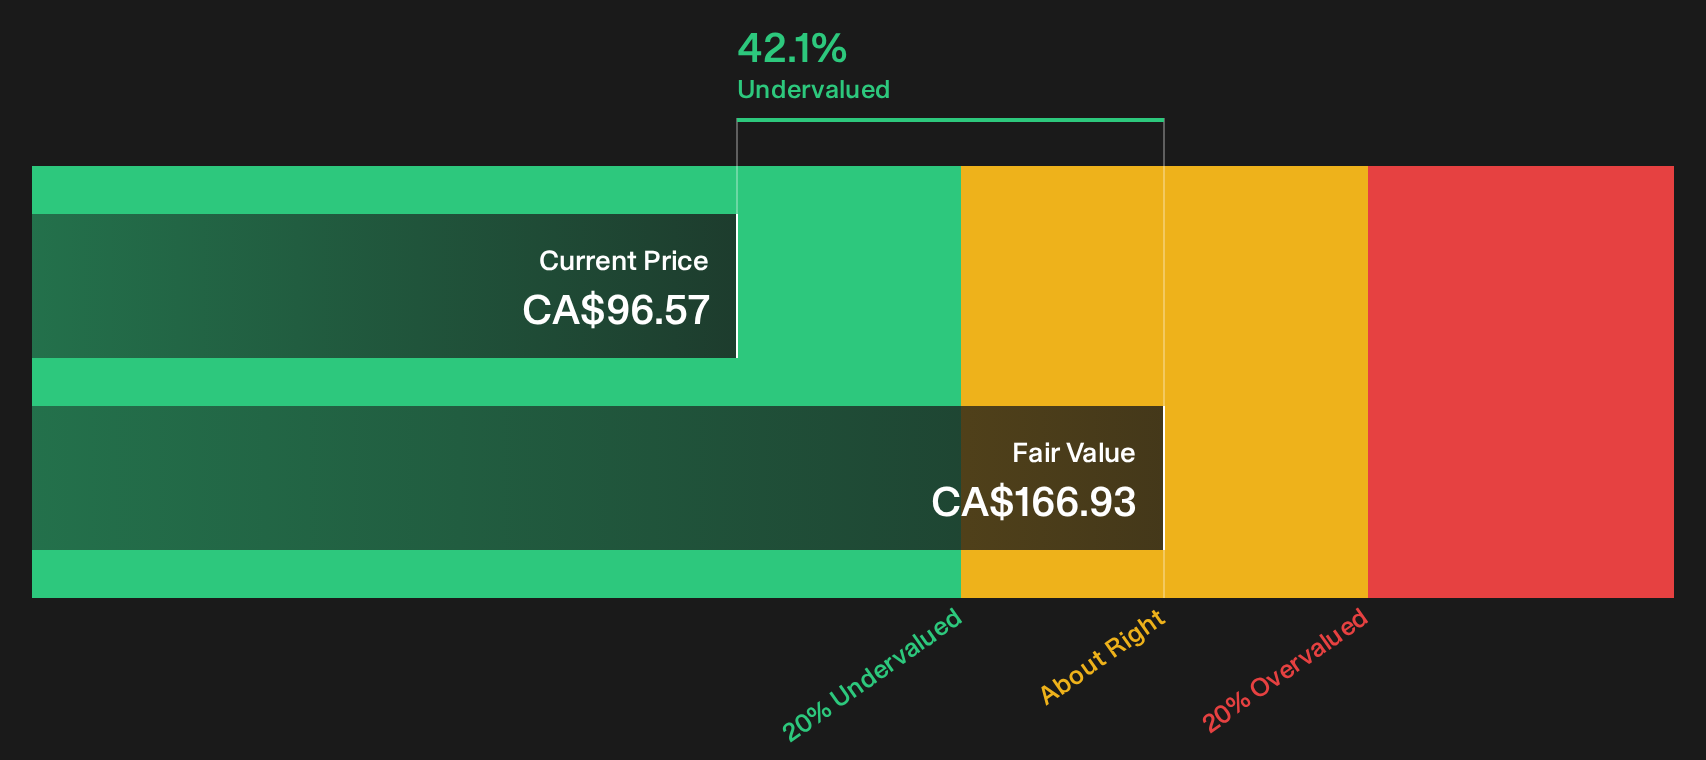
Suncor Energy is a Calgary based integrated energy group that mines oil sands, produces crude and refines it into fuel, with the cash heavy Oil Sands arm linked directly to this screener’s DCF signal. It generated about CA$26.9b from Oil Sands, CA$36.8b from Refining and Marketing and CA$2.5b from Exploration and Production, within a roughly CA$113b market value.
Suncor Energy matters here because its oil sands production and sizeable refining footprint both feed into the cash flows that sit behind this discounted valuation signal, giving investors a way to tie the theme to a specific integrated operating model.
"Reliance on very high utilization of existing oil sands and refining assets, including refinery runs consistently at or above 100% and upgrader utilization above 100%, leaves little unused capacity to offset unplanned outages, which could pressure volumes and compress margins if reliability slips from current record levels."
What happens to that cash flow story depends on how one less visible pressure on future profitability and returns eventually plays out.
If that pressure point is what you care about, the full narrative for Suncor Energy explains in detail how reliability, capital plans and cash returns could be quietly decoupling.
Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. By the time momentum shows on charts, early entries are gone, caught by investors who used targeted screeners while it matters. Getting in early can be important.
- Identify income workhorses designed for staying power by scanning the 1 dividend fortresses before yields change and more investors focus on the same payers.
- Look for potential multi-baggers hiding in plain sight with the curated 9 high quality undiscovered gems before their next breakout attracts broad momentum-focused money.
- Monitor the infrastructure behind AI’s surge using the focused 85 AI infrastructure stocks before these building block stocks attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com