


Profit Gains Might Change The Case For Investing In MillerKnoll Stock (MLKN)
- MillerKnoll reported first quarter 2026 results with sales of US$923.4 million, net income of US$26.6 million, and diluted EPS of US$0.38, compared with the prior-year period.
- The company produced higher net income and earnings per share despite lower sales, which points to tighter cost control or leaner operations in the quarter.
- We will look at how MillerKnoll's investment narrative is affected when profitability improves even as quarterly sales move lower.
See how MillerKnoll's tighter cost control compares with other efficient operators by reviewing our hand-picked list of list of solid balance sheet and fundamentals (24 results).
MillerKnoll Investment Narrative Recap
Owning MillerKnoll means believing the furniture group can keep translating design reach into solid earnings even when sales soften. The latest quarter fits that idea. Sales were US$923.4 million compared with US$955.7 million a year earlier, yet net income and EPS were higher. That points you toward a story centered on mix, pricing, and cost discipline rather than pure volume.
For the near term, the key catalyst is whether management can keep protecting margins while demand is affected by tariffs and macro shifts, especially in North America Contract and Global Retail. The biggest risk stays the same. Debt is not well covered by operating cash flow, so any hit to profitability or fresh asset impairments could quickly matter for equity holders.
The most relevant fresh data point is this first quarter 2026 earnings report itself. It confirms that MillerKnoll is now reporting cleaner profitability, with net income at US$26.6 million compared with US$20.2 million a year ago, and diluted EPS at US$0.38 compared with US$0.29. For you, the question is whether this quality of earnings is repeatable as the year unfolds.
Those numbers sit against a backdrop of earlier restructuring of reporting segments, ongoing Global Retail expansion, and a pricing approach that aims to offset tariff related cost pressure. If management keeps executing on those operational levers, the earnings profile implied by analyst forecasts becomes more plausible. If asset impairments, weaker orders, or tariff driven cost inflation reappear, that catalyst weakens and the balance sheet risk comes back into focus.
MillerKnoll's narrative projects US$4.4b revenue and US$188.1 million earnings by 2029. Analysts assume 4.3% yearly revenue growth and an earnings increase of about US$96.6 million from US$91.5 million today.
Discover why MillerKnoll's fair value suggests a 74% potential upside to its current price before the market closes that gap.
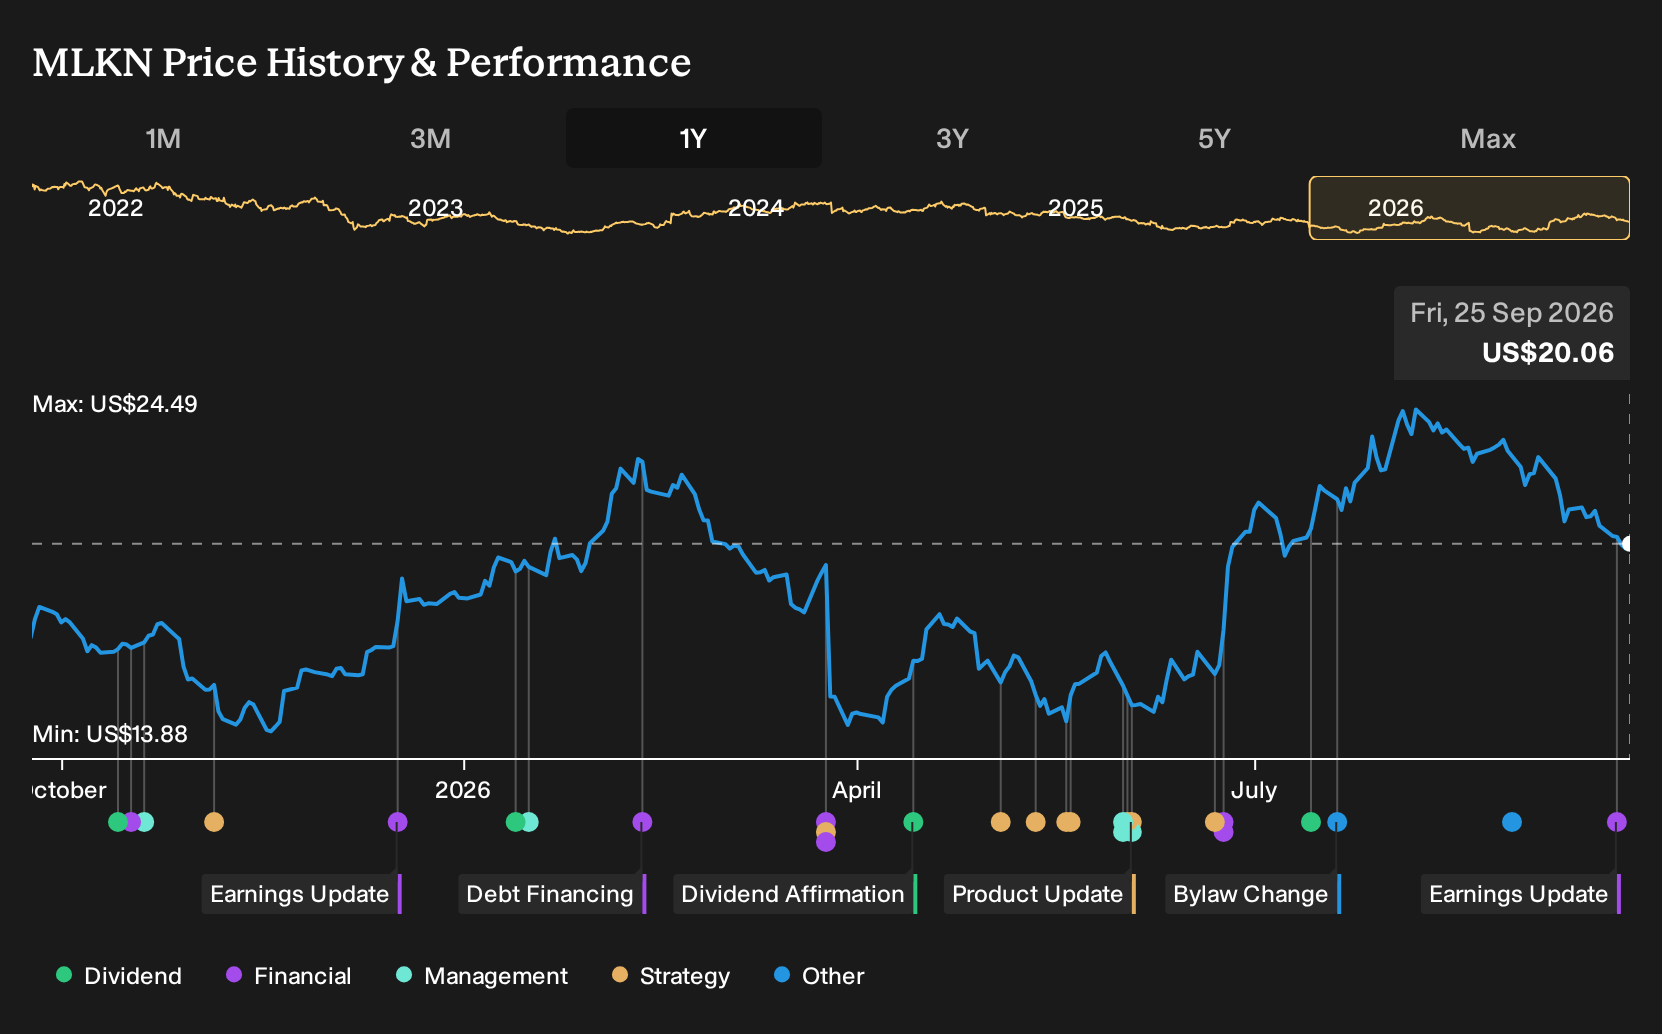
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community cluster between about US$27.17 and US$35, so you see a tight but still meaningful spread. Those retail viewpoints sit beside tariff risk, asset impairments, and pricing moves that can all shift MillerKnoll’s earnings path. It may be helpful to explore several angles before committing capital.
Explore another MillerKnoll fair value estimate, including one that suggests it could be worth just $27.17!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your MillerKnoll research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MillerKnoll. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MillerKnoll's overall financial health at a glance.
Looking For More Investment Ideas Beyond MillerKnoll?
If MillerKnoll's story has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you surface other stocks that fit different objectives and risk levels.
- If capital preservation matters most, focus on resilience and see which companies make it into the 30 resilient stocks with low risk scores.
- If you want potential mispricing opportunities, scan the 32 high quality undervalued stocks that pair quality fundamentals with attractive valuations.
- If you are hunting for future leaders before the crowd, review the 16 high quality undiscovered gems with strong underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com