


How Investors Are Reacting To ALK Abello Stock New EVP Appointment
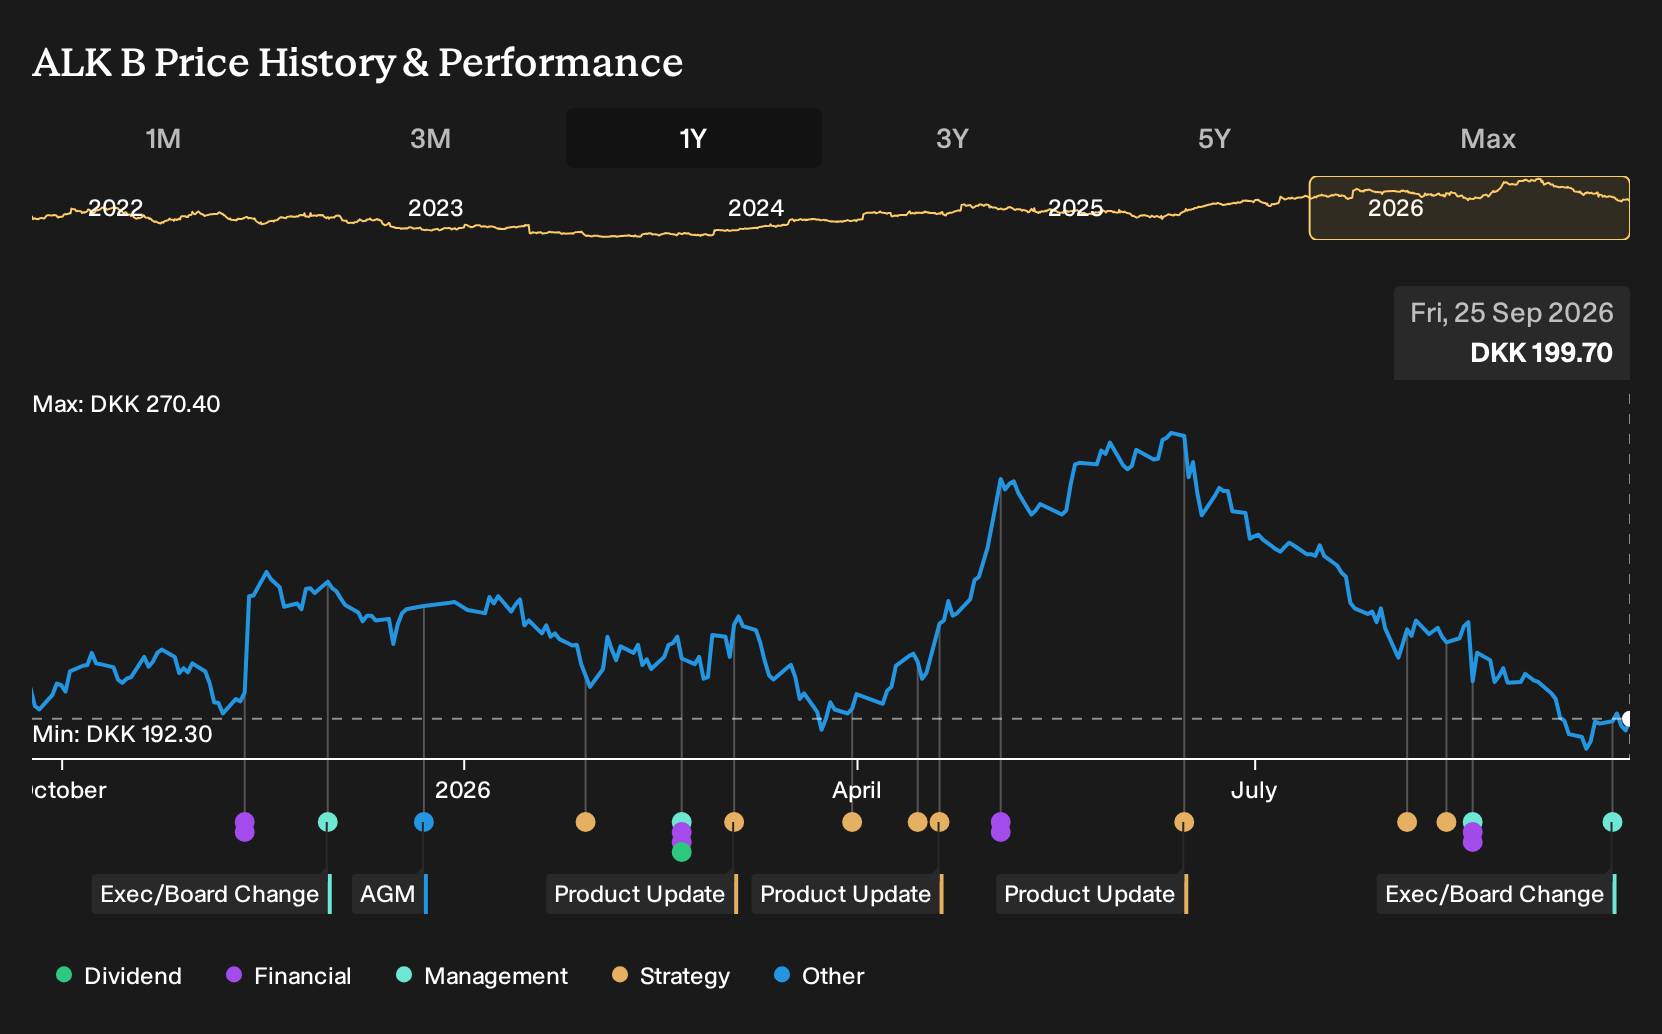
- ALK-Abelló has appointed Tina Abild Olesen as Executive Vice President for Corporate, Portfolio and Product Strategy, effective 1 October 2026, succeeding Jacob Glenting after his move to lead Research & Development.
- Her almost 30-year track record in commercial leadership at GlaxoSmithKline and Novo Nordisk, including building a global diabetes franchise, may inform how ALK-Abelló approaches portfolio focus, product positioning and global execution.
- We will now examine how ALK-Abelló's investment narrative could be influenced by Tina Abild Olesen's appointment to lead portfolio strategy.
Scan how leadership-driven execution stories like ALK-Abelló compare with other healthcare-focused operators by zeroing in on our hand picked 135 healthcare AI stocks.
ALK-Abelló Investment Narrative Recap
To own ALK-Abelló you need to be comfortable with a focused allergy platform that leans heavily on a few key therapies, from tablet immunotherapies to neffy, and on continued solid execution in pediatrics and anaphylaxis. The appointment of Tina Abild Olesen does not, by itself, alter the near term story. It still revolves around product uptake and geographic expansion.
The most important short term catalyst remains how quickly newer products such as neffy and pediatric tablets build usage as habits shift from legacy treatments. The main risk stays the same. A concentrated portfolio plus higher R&D and capacity spending could weigh on cash generation if adoption or pricing falls short of expectations.
The most relevant recent development for this news is ALK-Abelló’s broader push behind neffy and its allergy tablet portfolio, where commercialization speed and prescription patterns matter. A seasoned commercial leader who has worked across markets and channels could influence how aggressively the business sequences launches, allocates promotion and prioritizes markets.
For you, the link is simple. The key operational swing factors, such as neffy penetration, pediatric tablet uptake and scaling in markets like China and Japan, depend on disciplined portfolio choices and product positioning. This appointment puts one person in charge of that trade off between breadth, focus and execution risk at a time when spending and uptake need to stay in balance.
ALK-Abelló's current analyst storyline points to DKK 9.6 billion in revenue and DKK 2.0 billion in earnings by 2029, based on an assumed 13.6% yearly revenue growth rate and an earnings increase of about DKK 0.7 billion from DKK 1.3 billion today.
Uncover why ALK-Abelló's fair value indicates a 49% potential upside to its current price, a gap that could narrow quickly as expectations reset.
Exploring Other Perspectives
Some of the lowest ALK-Abelló forecasts focus on margin risk rather than product uptake. That bearish group saw revenue at about DKK 9.8b and earnings near DKK 1.9b by 2029, only slightly below consensus. You can treat Tina Abild Olesen’s appointment as a fresh prompt to compare these different margin stories and decide which feels more realistic.
Explore 3 other ALK-Abelló fair value estimates, including one that suggests it could be worth just DKK 193.47.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ALK-Abelló research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for ALK-Abelló. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ALK-Abelló's overall financial health at a glance.
Looking For More Ideas Beyond ALK-Abelló?
If ALK-Abelló has sharpened your thinking about concentrated healthcare bets and execution risk, it can be useful to line it up against other opportunities with very different profiles.
- For investors who care most about valuation support and quality, scan a curated pool of candidates screened for both fundamentals and pricing through 184 high quality undervalued stocks.
- If resilience matters more to you than headline growth, focus on steadier operators that score well on risk metrics with the help of 226 resilient stocks with low risk scores.
- When you want balance sheet strength and solid foundations, narrow your watchlist to companies filtered for robust finances by using the list of solid balance sheet and fundamentals (201 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com