


Is Martin Marietta Materials (MLM) A Bargain Following Its Premier Magnesia Deal?
Martin Marietta Materials (MLM) is back in focus after fresh data highlighted its role supplying crushed stone, sand, gravel, and other heavy building materials across US and international construction markets.
The share price of Martin Marietta Materials has pulled back, with a 30-day share price return down 8.8% and the 90-day move lower by 16.7%. However, the 5-year total shareholder return of 41.1% still points to a materially positive longer-term outcome, so recent weakness suggests momentum has cooled as investors reassess both growth potential and risk around the business.
Scan beyond Martin Marietta Materials and benchmark it against a curated 40 power grid technology and infrastructure stocks focused on infrastructure buildouts that also depend on aggregates, concrete, and heavy construction spending.
After a pullback that leaves Martin Marietta Materials well below its recent highs, the real choice is simple. Does it make more sense to step in at today’s price or wait for an even cheaper shot?
Most Popular Narrative: 27% Undervalued
Martin Marietta Materials last closed at $484.30, while the most followed narrative pegs fair value at about $662.65. This frames today’s pullback as a discount that hinges on how durable future demand and margins really are.
The acquisition of Premier Magnesia broadens Martin Marietta's magnesia product platform, providing higher-margin, cycle-resilient cash flows and new revenue streams that complement the core aggregates business, supporting greater earnings resilience and long-term EPS growth.
See why 10 investors see Martin Marietta Materials as 27% undervalued.
Result: Fair Value of $662.65 (UNDERVALUED)
Still, the bullish story around Martin Marietta Materials can crack if government infrastructure funding slows, or if higher costs and regulation pressure margins more than expected.
Find out about the key risks to this Martin Marietta Materials narrative.
Another View: Martin Marietta Materials On Rich Earnings Multiples
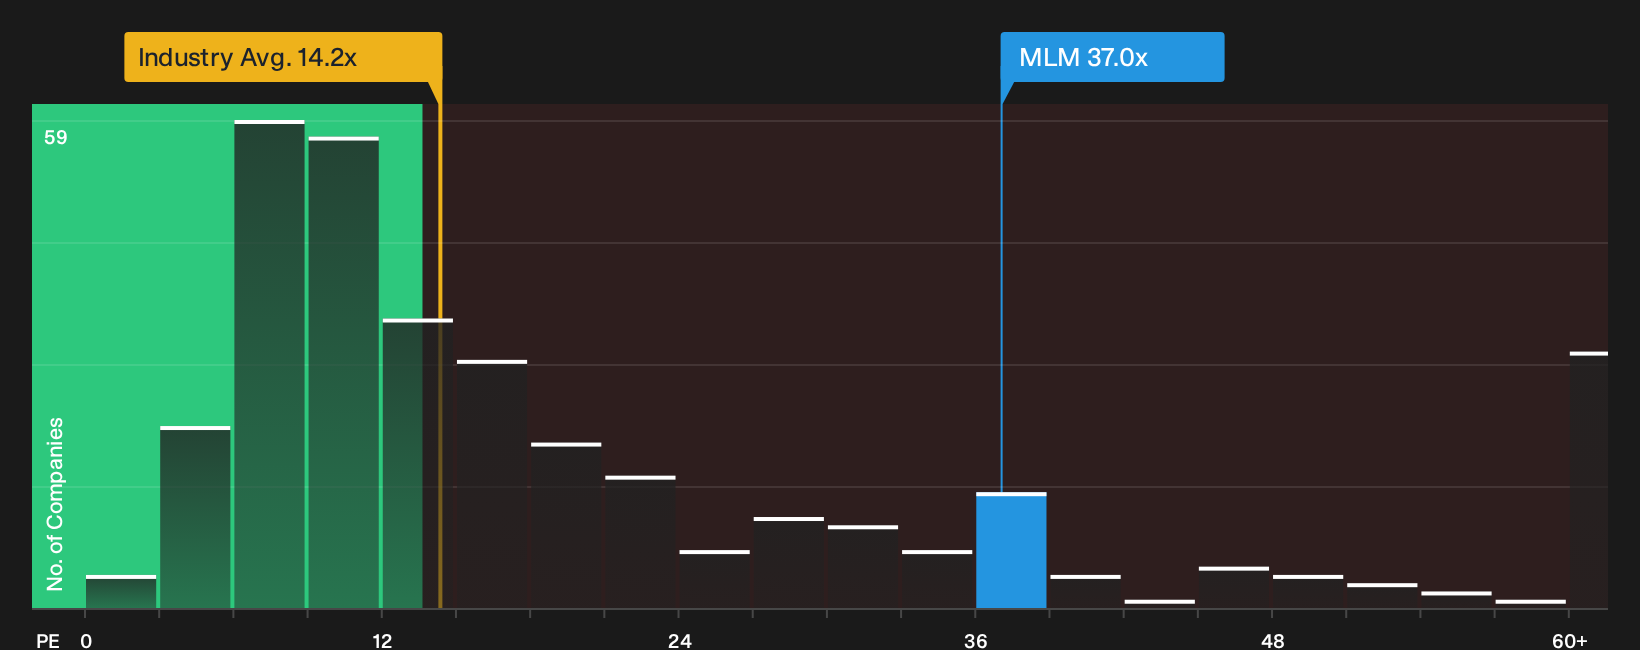
The DCF and narrative point to Martin Marietta Materials looking undervalued, yet the earnings multiple tells a different story. The stock trades on a P/E of 37x versus 19.8x for peers and a fair ratio of 25.8x. That gap could mean investors are paying up for quality or simply overpaying. Which side do you think it is?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Martin Marietta Materials often create the best moments to sharpen your own view instead of following the loudest narrative. Move fast, stress test both sides of the story, and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Martin Marietta Materials?
Do not stop with Martin Marietta Materials. Give yourself options by testing different angles and uncovering opportunities that might better fit your risk tolerance and income goals.
- Target potential upside in mispriced businesses by scanning a focused set of 32 high quality undervalued stocks that already combine quality fundamentals with attractive entry points.
- Strengthen portfolio resilience by hunting through a list of solid balance sheet and fundamentals (24 results) so you are not caught off guard when conditions turn tougher.
- Get ahead of the crowd by reviewing a curated pool of 16 high quality undiscovered gems before wider attention chases the same ideas.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com