


How Wider AI Use At WEX (WEX) Has Changed Its Investment Story
- WEX is increasing the use of artificial intelligence across credit decisions, claims processing, and internal workflows, aiming to lift efficiency and support future margin improvement while keeping debt within its stated leverage range.
- Management plans to direct most near term adjusted free cash flow into share repurchases, reinforcing an existing focus on earnings per share growth alongside a return on equity of 18.2%.
- Investors will be watching how WEX's heavier AI deployment across its platform influences the current investment narrative around digital payments.
Scan beyond WEX and consider other payment and AI driven opportunities with a curated set of 37 profitable AI stocks that aren't just burning cash.
WEX Investment Narrative Recap
To own WEX, you need to believe the payments platform can keep turning its diversified footprint in Mobility, Corporate Payments, and Benefits into steady earnings while AI tools push efficiency higher. The latest update on wider AI deployment and margin ambitions ties directly to that view. The near term swing factor is whether those efficiency gains can offset softer transaction volumes without stretching the balance sheet.
The biggest risk right now sits with leverage and competitive pressure. Debt is funded from higher risk sources and management still intends to prioritize buybacks, so investors are relying on tight risk controls and consistent cash generation. If fuel related activity, regulatory costs, or fintech rivals pressure volumes or pricing, that could limit how much AI driven savings actually show up in profits.
The most relevant piece of recent news is WEX committing more heavily to AI across credit decisions, claims processing, and internal workflows while targeting margin expansion in 2026. That matters because it touches every major operating segment and directly connects to earnings per share focus and the 18.2% return on equity the business currently delivers.
For catalysts, this AI push sits alongside earlier growth drivers such as the BP fleet agreement and expanding Benefits exposure as HSA eligibility widens. Together, those factors frame the operational path to higher utilization of WEX’s platform. Execution risk is clear. Management must keep service quality high, manage data and regulatory obligations, and hold debt within its leverage range while buybacks and AI spending continue.
WEX's analyst narrative points to about $3.1b in revenue and $519.6 million in earnings by 2029, based on 3.3% yearly revenue growth and an earnings increase of roughly $168.9 million from $350.7 million today.
Uncover how WEX's fair value indicates a 9% potential upside to its current price before the discount to WEX closes.
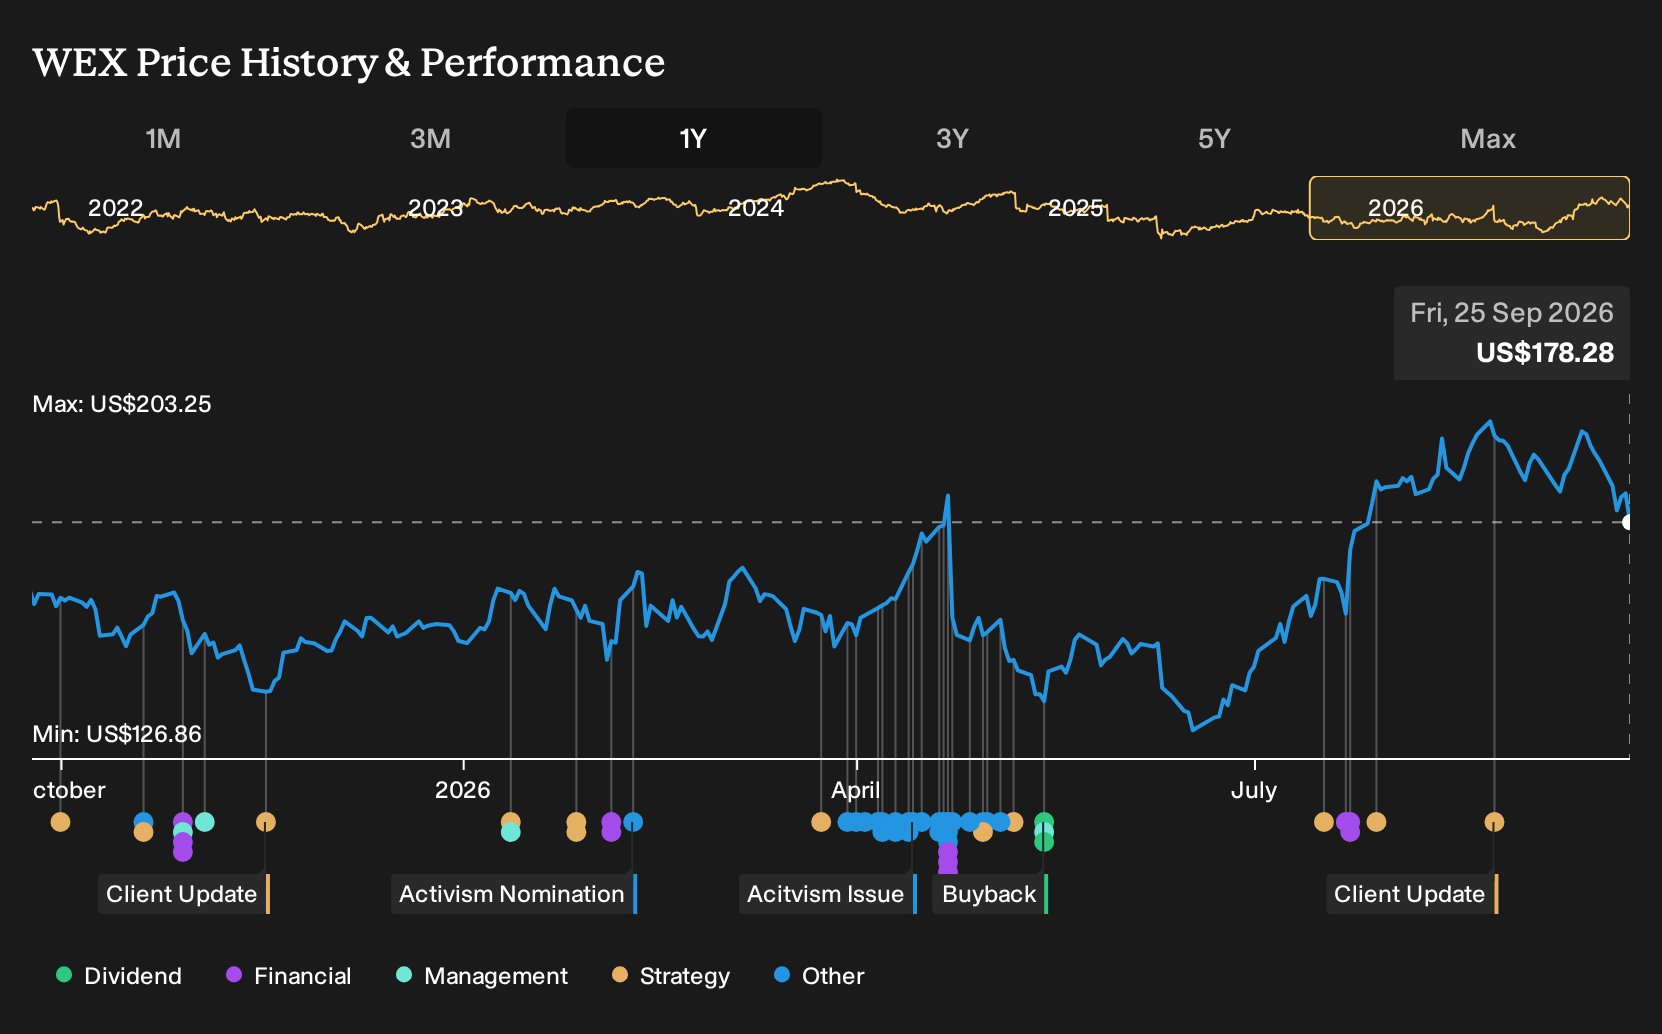
Exploring Other Perspectives
One alternate view leans hard into WEX’s digital payments push. The most optimistic analysts were working off faster top line expansion of 5.4% a year and earnings of about $518.0 million by 2029, before this AI news. That crowd already expected richer margins. This update could either reinforce or challenge that story, so consider both possibilities.
Explore 3 other WEX fair value estimates, including one that suggests potential upside of up to 172% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your WEX research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for WEX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate WEX's overall financial health at a glance.
Looking for more WEX style investment ideas?
If the WEX story has sharpened your thinking about quality, risk, and capital allocation, you can use the Simply Wall St Screener to widen your watchlist with stocks that fit different profiles and return drivers.
- For investors who want undervaluation with quality fundamentals, start with a focused set of 32 high quality undervalued stocks that already clear basic balance sheet and cash flow hurdles.
- If capital preservation and stability matter more to you than seeking the highest possible return, consider a group of 30 resilient stocks with low risk scores that score well on earnings consistency and financial resilience.
- For those who prefer strong finances as a foundation for any thesis, build a shortlist from a list of solid balance sheet and fundamentals (24 results) where debt levels and liquidity metrics are already screened for you.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com